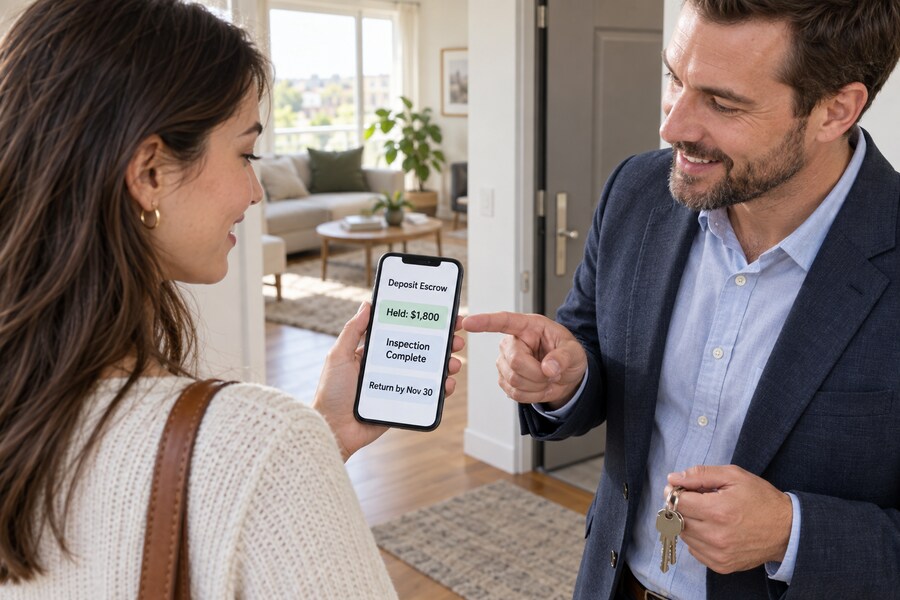
There is a specific kind of quiet resentment that builds in the months after a renter hands over a security deposit. The money leaves a checking account in a single transaction, often the largest one a tenant makes that year besides the rent itself, and then it simply vanishes into the landlord’s own bank account, mixed in with rent payments, maintenance reserves, and whatever else the landlord happens to be holding. From that point forward, the renter has almost no visibility into what happens to their money. They do not know whether it is sitting in a dedicated account, whether it is earning interest they are legally owed, or whether it is still there at all by the time they move out. All they have is a lease clause promising the deposit will be returned “less any deductions for damages” within some number of days after move-out, a number that varies by state and that landlords do not always honor even when it is written into law. This arrangement asks tenants to extend a great deal of trust to a landlord they may have met only once, for a sum of money that can represent real financial hardship if it is delayed, disputed, or simply never returned.
Landlords, for their part, are not entirely comfortable with the traditional arrangement either, even though they hold the money and appear to have the upper hand. A landlord who genuinely follows the rules — keeping deposits in a separate account, itemizing every deduction, returning the balance within the statutory window — still has to prove they did all of that if a tenant disputes the return, often in small claims court, where the burden of documentation falls heavily on whoever kept the sloppier records. Landlords with large portfolios face a different but related problem: reconciling dozens or hundreds of individual deposits, each subject to slightly different state rules on interest and holding periods, is a genuine administrative burden that consumes staff time and creates room for exactly the kind of error that turns into a costly dispute later. Neither side of this relationship is well served by a system built on one party unilaterally holding another party’s money with limited outside verification, and neither side would design it this way if they were starting from scratch.
This is the specific gap that blockchain-based escrow for security deposits is attempting to close. Instead of a landlord holding a tenant’s deposit directly, or even a traditional third-party escrow company holding it under a conventional paper-based agreement, a smart-contract escrow system places the deposit under the custody of a programmed, rule-based ledger that neither party unilaterally controls. The funds are locked according to terms both parties agreed to at lease signing, and they are released — in full, in part, or according to a documented dispute process — only when those pre-agreed conditions are met and recorded. Neither the landlord nor the tenant can quietly move the money, and because the rules for release are written into the contract itself and the resulting transactions are recorded on a tamper-evident ledger, both sides can see the same record of what happened rather than relying on each other’s word or on a private bank statement neither of them can independently verify.
It is worth being direct from the outset about how early this specific application still is. Long-term residential security deposits are a genuinely thin niche within the broader world of blockchain real estate technology, and there is no single, large-scale, long-running deployment of blockchain-based escrow built specifically and exclusively for multi-year residential tenancy deposits that has published years of independently verified results the way some adjacent real estate technologies have. What does exist, and what this article draws on, is a small number of verifiable, well-documented deployments of the same underlying mechanism — neutral, smart-contract-based escrow that holds funds and releases them according to pre-agreed, transparent rules — applied to closely related transactions: home-purchase escrow and short-term rental settlement. This article walks through how that mechanism actually works, what happens to a deposit at each stage of a smart-contract escrow, who benefits and how, what the verified case studies actually show and do not show, and where the real limitations and open questions remain before this becomes a mainstream way to handle a renter’s deposit.
The Problem: Why Security Deposits Breed Disputes
The security deposit dispute is one of the most common categories of landlord-tenant conflict in residential rental markets, and understanding why requires looking at how deposits are actually held under conventional practice rather than how the underlying laws idealize the process. In most jurisdictions, the law requires a landlord to keep a tenant’s security deposit in some form of separate or trust account, distinct from the landlord’s own operating funds, precisely because lawmakers recognized early on that a deposit sitting in a landlord’s general account is functionally indistinguishable from the landlord’s own money and is therefore vulnerable to being spent, especially by a landlord under financial pressure. In practice, enforcement of this separation is inconsistent. Small landlords managing one or two properties often do not maintain a truly segregated account at all, either out of ignorance of the requirement or because opening and maintaining a separate account is an administrative step that is easy to skip when no one is checking. Even larger property management companies, which are more likely to follow the letter of the law, typically pool deposits from many different tenants into a single omnibus trust account, which satisfies the separation requirement but still leaves an individual tenant with no way to verify that their specific deposit, as opposed to the pooled balance generally, is actually intact.
A second structural source of friction is the patchwork of state and local rules governing what a landlord must do with a deposit once it is collected. Some states require landlords to pay tenants interest on deposits held for longer than a specified period, calculated at a statutory or passbook-savings rate; others impose no interest requirement at all. Holding periods for returning a deposit after move-out vary from as little as two weeks in some jurisdictions to as long as forty-five days in others, and the penalties for a landlord who misses that window, or who fails to provide an itemized list of deductions within it, range from minor to severe, including in some states a requirement that the landlord return the entire deposit regardless of legitimate damage claims if the itemization deadline is missed. A tenant who moves between states over the course of a rental history is effectively navigating a different set of rules every time, with no consistent expectation of what “normal” deposit handling looks like, which makes it hard for renters to recognize when a landord’s behavior is actually a violation rather than simply an unfamiliar but legal practice.
The most emotionally charged part of the process, and the part most likely to end in a genuine dispute, is the itemized deduction at move-out. A landlord who believes a tenant caused damage beyond normal wear and tear has to document that damage, estimate or obtain a repair cost, and communicate that itemization to the tenant within the statutory window, all based on a comparison to the unit’s condition at move-in that may have been recorded inconsistently, incompletely, or not at all. Tenants, for their part, frequently believe that landlords inflate damage claims specifically to justify withholding some or all of the deposit, using the itemization process less as an honest accounting and more as a negotiating tactic against a party who has already moved out and has limited leverage to contest the claim. Whether or not this belief is fair to any individual landlord, the incentive structure genuinely does reward opacity: a landlord who overstates damage costs, understates the deposit balance owed, or simply delays the return past the legal deadline faces, in practice, a tenant who is unlikely to pursue a small claims case over what is often a few hundred or at most a few thousand dollars, given the time, cost, and uncertainty of formal legal action.
What ties these problems together is the absence of a neutral, mutually visible record that both landlord and tenant can trust without relying entirely on each other’s honesty or on a court’s after-the-fact intervention. The deposit sits in an account only the landlord can see, subject to rules that vary by jurisdiction and are inconsistently enforced, released according to an itemization process that one party controls and the other party can only contest after the fact. This is precisely the structural gap that neutral, rule-based escrow — whether built on blockchain infrastructure or some other tamper-evident technical foundation — is designed to close, by moving custody of the deposit away from either interested party and replacing a private, after-the-fact dispute process with a transparent, pre-agreed set of release conditions that both sides can verify in real time.
What Blockchain Escrow Actually Means for a Security Deposit
At its core, blockchain-based escrow replaces a single custodian — typically the landlord, sometimes a traditional third-party escrow company — with a shared, tamper-evident ledger and a smart contract, which is simply a program that automatically executes pre-agreed instructions once specified conditions are verifiably met. Applied to a security deposit, this means the tenant’s funds are transferred not into the landlord’s bank account but into a smart contract’s custody at lease signing, where they remain until the conditions both parties agreed to at the outset — typically an undisputed move-out inspection, an expiration of a claim-filing window, or a resolved dispute process — are satisfied and recorded. Because the record of that custody and its eventual release lives on a ledger designed to make after-the-fact alteration difficult, neither the landlord nor the tenant can unilaterally change what the record shows once an entry has been made and confirmed, which is the same fundamental property that gives blockchain-based systems their appeal in other financial contexts.
It is worth being precise about what this property does and does not solve, since a considerable amount of vague enthusiasm has been attached to “blockchain” as a general-purpose fix for landlord-tenant distrust without much attention to its actual, narrower capabilities. A smart contract can guarantee that funds placed into its custody cannot be withdrawn by either party outside the rules both parties agreed to in advance, and it can guarantee that the record of what triggered a release — a timestamp, an uncontested inspection outcome, an expired response window — cannot be silently rewritten later. It cannot independently determine whether a landlord’s damage claim is legitimate, whether a stain on a carpet constitutes normal wear and tear or tenant-caused damage, or whether a photo submitted as evidence is accurate and current. Those are judgment calls that still require human evidence, human review, and in genuinely contested cases, some form of human or institutional arbitration standing outside the contract itself. The technology solves the custody and record-integrity problem; it does not solve the underlying, and often harder, problem of evaluating a disputed factual claim about property condition.
Given that limitation, the actual value of blockchain escrow for a security deposit comes from combining tamper-evident custody with a clearly defined, pre-agreed set of release rules that both parties consent to before any dispute exists, rather than negotiating those rules for the first time under the pressure of an active disagreement. A well-designed system does not let either the landlord or the tenant simply declare that funds should be released; it structures the process so that a release requires either mutual, cryptographically verifiable agreement — both parties confirming the deposit should be returned or partially withheld — or the passage of a defined response window during which one party had the opportunity to contest a claim and did not. This shifts the moment of negotiation from an emotionally charged post-move-out standoff to a calmer, pre-agreed structure established when both parties still had roughly equal incentive to agree on fair terms.
In practice, essentially every serious proposal or working implementation of blockchain-based rental escrow uses what is called a permissioned or semi-permissioned architecture rather than a fully open, anonymous cryptocurrency network, which is an important distinction given how much confusion exists between “blockchain” and “cryptocurrency speculation” in popular understanding. On a permissioned system built for this purpose, the parties to a specific lease — the tenant, the landlord or their property manager, and in some designs a neutral arbitrator or the platform operator itself — are the only accounts authorized to initiate or approve a release, while the underlying custody and record-keeping infrastructure runs on blockchain rails specifically to prevent quiet, unilateral tampering by whichever party happens to have technical access to the system. A tenant interacting with such a system generally does not need to understand cryptocurrency wallets, private keys, or blockchain terminology at all; in the platforms that have actually been built, the tenant’s experience is a familiar-looking web or app interface for funding the deposit, viewing its status, and responding to any claim, with the ledger mechanics handled entirely behind the scenes. The tradeoff, as with any permissioned system, is that its trustworthiness still depends on the operator’s technical architecture genuinely preventing after-the-fact edits and on the underlying funds — whether held in a stablecoin or converted to and from traditional currency — being managed with real custodial and regulatory discipline, rather than on the fully decentralized, trustless design that public cryptocurrency networks are built around.
How Funds Move In, Are Held, and Are Released
The lifecycle of a blockchain-escrowed deposit begins at lease signing, when the tenant transfers the agreed deposit amount into the smart contract’s custody rather than into the landlord’s own account. This initial funding transaction is the first entry in the deposit’s permanent record, establishing the amount, the date, and the identities of both parties in a form that neither can later dispute or quietly alter. From this point forward, the deposit sits in a state that neither the landlord nor the tenant can access unilaterally; the smart contract itself, not either human party, is the custodian, which is the central structural difference from a conventional arrangement where the landlord’s bank simply treats the deposit as another balance in the landlord’s own account.
During the tenancy itself, the deposit typically remains untouched, though some system designs allow for partial, pre-agreed releases in specific circumstances, such as an early move-out settlement negotiated and confirmed by both parties well before the lease term naturally ends. At move-out, the process that determines the deposit’s final disposition begins: an inspection occurs, ideally documented with timestamped photographs or video that both parties can access, and the landlord, if they believe deductions are warranted, files an itemized claim against the escrowed funds within whatever window the smart contract’s rules specify, often mirroring the statutory itemization deadlines that already exist under state law. If the landlord files no claim within that window, the full deposit releases automatically to the tenant, which is a meaningful improvement over conventional practice, where a landlord’s simple failure to act within the legal deadline still often requires the tenant to actively assert their rights, sometimes through legal action, rather than triggering an automatic return.
If the landlord does file a claim, the tenant receives notice and a defined window to respond, either accepting the proposed deduction, in which case the smart contract releases the disputed portion to the landlord and the remainder to the tenant, or contesting it, in which case the system routes the dispute to whatever resolution mechanism the platform has built in, which in the designs that have actually been implemented ranges from a structured evidence-submission and negotiation process to escalation to a neutral third-party arbitrator or, in unresolved cases, the traditional small claims court system that would have handled the dispute anyway under a conventional deposit arrangement. What changes in this scenario is not that disputes disappear, since genuine disagreements about property condition will always require some form of human judgment, but that the underlying facts feeding into that judgment — when the deposit was funded, what claim was filed and when, what evidence was submitted and by which party, whether a response window was met or missed — are no longer contested facts themselves, because they live on a tamper-evident record both parties and any arbitrator can independently verify.
The practical consequence of this design is that a genuinely disputed security deposit case under blockchain escrow starts from a narrower, more factual disagreement than a conventional case typically does. Rather than a tenant and landlord disagreeing about basic procedural facts — did the landlord actually itemize the deductions in writing, was it done within the legal deadline, was the tenant properly notified — which conventional disputes frequently turn on due to poor record-keeping on one or both sides, a blockchain-escrowed dispute has already settled those procedural questions through the tamper-evident record, leaving only the substantive question of whether the claimed damage genuinely exceeds normal wear and tear. That substantive question still requires human judgment, but it is a narrower and more tractable one than the combined procedural-and-substantive disputes that clog small claims dockets under the conventional system.
What Renters, Landlords, and Property Managers Each See
For the renter, the underlying smart contract and ledger infrastructure is largely invisible; what they interact with is typically a dashboard or app view showing the deposit amount currently in escrow, the date it was funded, and, as the lease approaches its end, a clear timeline of what happens next and by when. Because this information is drawn directly from the same record that governs the actual movement of funds rather than a summary the landlord could selectively present, a tenant checking this view has a genuinely verifiable answer to the question that traditional deposit arrangements leave frustratingly opaque: is my money actually still there, and under what terms will I get it back. Some implementations extend this transparency further by allowing tenants to see, in real time, whether their landlord has filed any claim against the deposit as soon as it happens, rather than waiting for a letter to arrive near the statutory deadline.
For landlords and property managers, the value of the same system looks different but is no less significant: instead of manually tracking which of potentially dozens or hundreds of individual deposits are subject to which state’s interest and holding-period rules, a landlord using a well-built escrow platform can see every deposit’s status, funding date, and applicable release rules on a single dashboard, with the platform itself, rather than a property manager’s memory or a spreadsheet, tracking compliance deadlines and interest accrual. This matters considerably for larger portfolio operators, where a single missed itemization deadline on even one unit, multiplied across a portfolio of hundreds of leases, represents a real and recurring compliance risk; a system that automatically flags approaching deadlines and, in the case of an uncontested deposit, releases funds without requiring manual intervention removes a meaningful source of operational error rather than simply making an existing manual process marginally faster.
Property managers operating on behalf of individual property owners gain a related but distinct advantage: because the record of every deposit’s custody, claims, and releases is maintained independently of the property manager’s own internal bookkeeping, an owner who wants to verify that their property manager has handled tenant deposits properly, keeping them separate from operating funds and returning them according to the applicable rules, has an auditable, third-party-verifiable record to check against, rather than having to trust the property manager’s own accounting entirely. This is a meaningful accountability benefit in an industry where property management companies handling deposits improperly, whether through negligence or outright misappropriation, is a real and recurring source of owner and tenant harm.
Taken together, these different interfaces — a simple, reassuring balance-and-timeline view for the tenant, a compliance and portfolio-management dashboard for the landlord or property manager, and an independently auditable record for the property owner overseeing a manager — are what a neutral escrow system actually looks like in daily use, regardless of how much of the underlying architecture is a strict blockchain versus another tamper-evident record-keeping design built along similar principles. What unites all three views is that they draw from the same underlying record rather than from separate, potentially conflicting private accounts, which is the structural change that neutral escrow is fundamentally built to deliver.
Benefits Across the Rental Relationship
For renters, the most immediate and tangible benefit of neutral, rule-based escrow is a meaningful reduction in the uncertainty that defines the conventional deposit experience. A tenant no longer has to simply trust that a landlord kept their deposit in a proper account, is aware of and following the applicable interest and holding-period rules, or will actually itemize deductions honestly rather than treating the move-out process as an opportunity to recover unrelated costs. Instead, the tenant has a continuously visible, independently verifiable record of exactly where their money is and what conditions govern its return, and in the common case where no dispute arises, an automatic release the moment the response window closes rather than a return that depends on the landlord proactively following through on a legal obligation. This shift, from passively hoping a landlord behaves properly to having a system that enforces the agreed rules regardless of either party’s individual conduct, is the single largest quality-of-life improvement neutral escrow offers renters, independent of whether the underlying technology is ever something the tenant thinks about directly.
Landlords benefit in a way that is less intuitive but genuinely significant: a neutral, well-documented escrow record protects a landlord acting in good faith just as much as it protects a tenant, by giving the landlord an unambiguous, timestamped account of exactly when a claim was filed, what evidence was submitted, and whether the tenant was given proper notice and opportunity to respond, all of which matters enormously if a dispute ultimately escalates to small claims court, where a landlord’s ability to produce clean, contemporaneous documentation often determines the outcome regardless of the underlying merits of the claim. Landlords who currently maintain careful paper or spreadsheet records already get some of this benefit, but a shared, tamper-evident ledger removes the tenant’s ability to argue, as sometimes genuinely happens, that a landlord’s records were altered or fabricated after the fact, because the ledger’s structure makes that kind of after-the-fact alteration far harder to credibly claim happened, let alone actually carry out.
Property management companies, who operate at a portfolio scale where manual compliance tracking becomes genuinely difficult, gain a distinct operational benefit: a system that automatically tracks interest accrual, holding-period deadlines, and itemization windows across hundreds or thousands of individual leases removes a category of compliance risk that currently depends on individual staff members remembering and correctly applying rules that vary by jurisdiction and change periodically as state legislatures amend their landlord-tenant codes. This matters financially as well as operationally, since missed deadlines and improperly handled deposits expose management companies to statutory penalties that in some states include multiples of the deposit amount, a genuine deterrent that a well-built automated system directly addresses by simply not missing deadlines the way a busy human staff member occasionally will.
Insurers and the broader dispute-resolution system that currently absorbs the cost of unresolved deposit disagreements gain a less direct but still meaningful benefit from the same underlying shift. Small claims courts in many jurisdictions see security deposit disputes as one of their most common case types, consuming judicial resources on disagreements that, as described earlier in this article, often turn on procedural questions of record-keeping and notice rather than genuine substantive disagreement about property condition. A system that resolves the procedural questions automatically through a verifiable record, leaving only the narrower substantive dispute for human or arbitrated review when one genuinely exists, reduces the caseload burden on a court system that was never particularly well suited to efficiently resolving disputes over a few hundred or a few thousand dollars in the first place. Across every stakeholder in this relationship, the underlying benefit is structurally consistent: a single, neutral, mutually visible record substitutes for the asymmetric trust relationship that has defined security deposits for as long as the modern landlord-tenant system has existed, and that substitution reduces friction differently for each party while adding up to a faster, less adversarial process overall.
Documented Case Studies in Smart-Contract Escrow
Long-term residential security deposits specifically are, as this article has already acknowledged, a genuinely thin niche within blockchain real estate applications, and it would be dishonest to present a large-scale, long-running, independently verified deployment built exclusively for multi-year rental deposits as though one already exists at real scale. What does exist, and what deserves careful, honest examination, are two verifiable, well-documented deployments of the identical underlying mechanism — neutral custody of funds released according to pre-agreed, transparent conditions rather than one party’s unilateral control — applied to closely related but distinct transactions. Neither of these cases is a rental security deposit. One is a home-purchase escrow, and the other is a short-term rental booking settlement. Both are included here specifically because they demonstrate the same smart-contract-escrow mechanism operating at genuine, independently reported transactional scale, which is the strongest available evidence for whether the underlying technology actually works under real market conditions rather than only in a conceptual pilot or a whitepaper.
Finding examples that meet a high verification bar for this specific niche takes real effort, because the amount of promotional and conceptual writing about “blockchain for rental deposits” considerably exceeds the number of systems that have actually processed real money at meaningful scale with independently reported results. Various startups and research projects have proposed or built early-stage rental-deposit smart contracts, and academic and industry writing on the concept is not hard to find, but the great majority of this material describes a proposed architecture or a small internal pilot rather than a deployment with published, independently verifiable transaction volume. The two cases examined here were chosen specifically because they clear that higher bar: both have identifiable companies behind them, both have independently reported dates and figures rather than vague claims of transformation, and both are documented in trade press coverage independent of the sponsoring company’s own marketing materials.
Propy Title & Escrow: Smart-Contract Escrow at Real Transactional Scale
In May 2022, the real estate technology company Propy launched Propy Title & Escrow, a title and escrow product built specifically to use smart contracts, rather than a conventional third-party escrow company, to hold and release funds during a residential home purchase. Propy founder and chief executive Natalia Karayaneva described the underlying design to trade publication Inman at launch as replacing manual escrow processes with smart contracts that automatically gather, display, and process the closing information both buyer and seller need to see, moving the transaction closer to what she called a “click-to-close” experience. The service launched in three states — Arizona, Colorado, and Florida — with Propy stating publicly at the time that it planned to expand availability across the rest of the United States over the following two years.
The specific value this product demonstrated centers on the same core mechanism this article has described for rental deposits: rather than a single party, whether a traditional escrow company or one side of the transaction, unilaterally holding and controlling the buyer’s funds until closing, Propy’s smart-contract escrow places those funds under the custody of a programmed contract that releases them only when the pre-agreed closing conditions are satisfied and verifiably recorded. Karayaneva specifically framed the value proposition around eliminating wire fraud, a serious and costly problem in conventional real estate closings where criminals impersonate a title company or escrow agent to redirect a buyer’s closing funds to a fraudulent account, arguing that a smart-contract-based escrow structure removes the vulnerable manual wire-transfer step that this type of fraud specifically exploits.
By the end of 2022, Propy reported in its own year-end company update that Propy Title & Escrow had closed more than one hundred million dollars in deals processed seamlessly and securely on blockchain, a figure that sat alongside the company’s broader report of one billion dollars in total transaction volume across its full platform for the year. This specific figure — over one hundred million dollars in blockchain-processed title and escrow transactions in a single calendar year, operating across three states with real home buyers and sellers rather than a simulated pilot environment — represents genuine evidence that smart-contract escrow can handle real transactional volume involving substantial sums of money without the system breaking down or requiring a return to conventional escrow processes.
It is essential to be precise about what this case study does and does not establish for the rental security deposit application specifically. Propy Title & Escrow is built for one-time home-purchase closings, where a large sum moves once, under a single, well-defined set of closing conditions negotiated by sophisticated parties — buyers, sellers, real estate agents, and title professionals — typically with legal counsel or at minimum an experienced agent involved on each side. A rental security deposit is a different kind of transaction: a smaller sum, held for months or years rather than released within days of closing, governed by consumer-protection statutes specifically designed to protect a less sophisticated party, and released according to a subjective damage assessment rather than an objective closing checklist. Propy’s achievement demonstrates that smart-contract escrow works at real scale for the home-purchase use case; it does not, by itself, demonstrate that the same architecture, largely unmodified, would handle the different demands of a long-term rental deposit equally well. What it does demonstrate, credibly and at real scale, is that the foundational mechanism — neutral custody, programmed release conditions, and a tamper-evident record accessible to all parties — functions in a live, regulated, real-money transactional environment, which is the necessary starting point for any rental-deposit-specific application that might build on it.
Dtravel: Smart-Contract Settlement for a Booking Deposit
In August 2022, the Web3 hospitality platform Dtravel completed what it and independent trade publications, including CoinDesk and Skift, described as the first short-term rental booking paid and settled entirely through a smart contract rather than a traditional platform intermediary. The booking involved a two-thousand-dollar stay, paid in the stablecoin USDC, at a London property listed by a host who had joined Dtravel’s direct-booking pilot program, with the funds held and released through the smart contract governing the transaction rather than passing through a centralized booking platform’s own payment processing and payout system the way a booking on a conventional short-term rental marketplace would.
The mechanism Dtravel demonstrated is directly relevant to the deposit-escrow question this article examines, because a short-term rental booking on its platform functions similarly to a security deposit in miniature: the guest’s payment is placed under smart-contract custody rather than being immediately and irreversibly transferred to the host, and release of those funds is governed by the pre-agreed terms of the booking rather than by either party’s unilateral discretion. Because the transaction runs directly between guest and host on the underlying blockchain network, without a centralized booking platform acting as the intermediary holding and eventually disbursing funds, both parties are relying on the smart contract’s programmed rules rather than on a third company’s internal payment processes and dispute-resolution policies, which is structurally the same shift this article has described for a rental security deposit moving from landlord custody to neutral smart-contract custody.
In January 2023, Dtravel announced a significant technical upgrade to this underlying system, moving its smart-contract infrastructure to a v3 architecture built on the Polygon proof-of-stake network, a blockchain chosen specifically for its low transaction costs and fast settlement times compared to earlier infrastructure. As part of this upgrade, individual bookings were represented as non-fungible tokens on the Polygon network, allowing a guest holding a confirmed booking to transfer or resell that reservation through a peer-to-peer marketplace if their plans changed, a capability that would have been considerably harder to implement cleanly without the underlying tokenized, smart-contract-based architecture. This upgrade is independently documented in trade coverage from outlets including CryptoSlate and ShortTermRentalz, giving the progression from the original August 2022 booking to the January 2023 architectural upgrade a verifiable public record spanning roughly six months of continued, reported development rather than a single announcement that was never followed up on.
As with the Propy case, it is important to state clearly what this example does and does not demonstrate for long-term rental security deposits. Dtravel’s smart contracts govern short-term vacation and hospitality bookings, typically lasting days rather than months or years, where the funds at stake are the cost of the stay itself rather than a separate damage deposit held against a much longer tenancy, and where the guest and host relationship, governed largely by platform terms rather than the kind of state landlord-tenant statutes that apply to residential leases, is legally and practically distinct from a long-term rental arrangement. What Dtravel’s verified history does show is that smart-contract-based custody and release of real money, in a real consumer-facing hospitality transaction rather than only a conceptual demonstration, has operated continuously and been meaningfully upgraded over time, which is meaningful evidence that the underlying mechanism is durable enough to build on rather than a one-time technical stunt that quietly disappeared after its initial announcement.
Limitations, Costs, and Open Questions
The most fundamental limitation facing blockchain-based escrow for rental security deposits specifically, as opposed to the home-purchase and short-term booking use cases already demonstrated at scale, is that residential landlord-tenant law is deeply state-specific, consumer-protection-oriented, and not something a smart contract can simply code around. A system built for a home purchase can rely on a relatively standardized closing process and sophisticated parties on both sides; a system built for a rental deposit has to correctly implement dozens of different state and sometimes municipal rules governing maximum deposit amounts, mandatory interest payments, permissible holding periods, and required itemization procedures, each of which can change as state legislatures amend their codes. A smart contract that gets any of these jurisdiction-specific rules wrong does not merely produce an inconvenient error; it can put a landlord or platform operator in violation of consumer-protection statutes specifically designed to protect the party with less bargaining power in the relationship, which is a considerably higher-stakes failure mode than a delayed transaction confirmation.
A second significant obstacle involves the practical mechanics of holding a deposit’s value stable and legally accessible over what can be a multi-year tenancy. Both of the case studies examined in this article settled quickly, within days for a home purchase closing and effectively instantly for a short-term booking, which sidesteps a genuinely hard question a long-term rental deposit escrow has to answer: whether funds should be held in a stablecoin pegged to a fiat currency, converted to and from traditional currency at deposit and release, or handled through some hybrid custodial arrangement, and who bears the operational and regulatory responsibility for that custody over a holding period that could span several years. Stablecoins reduce the price-volatility risk associated with holding value in a more traditional cryptocurrency, but they introduce their own dependency on the issuing company’s reserves and redemption practices remaining sound over the full multi-year holding period, a risk that traditional bank-held trust accounts, for all their other shortcomings, do not carry in the same form.
Cost and integration burden present a related challenge, and one that falls unevenly across the rental market in a way that could work against the smaller, independent landlords who arguably have the least sophisticated existing deposit-handling practices and might benefit proportionally the most from a well-built neutral system. Large property management companies operating hundreds or thousands of units can more easily absorb the cost of integrating a smart-contract escrow platform into their existing leasing and accounting systems, while an individual landlord renting out one or two units, who is statistically the segment of the market most likely to commingle deposits improperly or miss statutory deadlines in the first place, has the least incentive and the least technical capacity to adopt a new platform voluntarily. This creates a genuine risk that neutral, transparent escrow becomes available mainly to renters dealing with well-resourced, already reasonably compliant institutional landlords, while renters dealing with smaller, less formal landlords, who arguably need the protection most, continue operating under the conventional system with all its existing weaknesses.
There is also an unresolved and genuinely difficult question of who arbitrates a real, substantive dispute once the procedural questions a tamper-evident record can settle are taken off the table. As this article has described, a well-designed system removes disagreement over whether a claim was filed on time or whether proper notice was given, but it cannot mechanically determine whether a stain on a carpet constitutes ordinary wear and tear or tenant-caused damage requiring compensation. Different platform designs answer this differently: some route unresolved disputes to a designated third-party arbitrator built into the platform’s terms, others fall back to the same small claims court process that would have handled the dispute under a conventional deposit arrangement, and it remains genuinely unsettled which approach renters and courts will ultimately trust as fair, particularly if a platform’s arbitration mechanism is perceived as favoring the landlords and property managers who are typically the platform’s paying customers.
Finally, there is the ordinary challenge of achieving meaningful adoption in a residential rental market made up of millions of individual landlords and property managers, the large majority of whom have no particular reason to change an existing deposit-handling process that, however imperfect, is not actively causing them visible problems. The clearest path forward, based on how the adjacent use cases examined in this article actually developed, likely runs through large, well-resourced institutions — sizable property management companies, purpose-built proptech platforms, or established real estate technology providers already offering blockchain-based escrow for other transaction types — absorbing the initial cost and regulatory complexity of building a genuinely compliant, multi-jurisdiction rental deposit product, rather than expecting the technology to spread organically from individual landlord to individual landlord. Whether neutral, blockchain-based deposit escrow eventually becomes a mainstream feature of residential leasing will likely depend less on whether the underlying smart-contract mechanism works, which the home-purchase and short-term booking cases already suggest it does, and more on whether an institution with the scale and legal resources to solve the jurisdiction-specific compliance problem decides the long-term rental market is worth that investment.
Final Thoughts
Neutral escrow for security deposits addresses a problem that is fundamentally about trust asymmetry rather than about technology for its own sake. A landlord holding a tenant’s money has always had the practical ability to treat it as their own, delay its return, or inflate a damage claim, not necessarily out of bad faith but because the traditional system gives them unilateral control and leaves the tenant with limited practical recourse short of a small claims filing that many renters never pursue. What smart-contract-based escrow offers, at its most honest, is not a replacement for honest dealing between landlords and tenants but a structural correction to a relationship that has historically given one party disproportionate control over the other party’s money. That correction has value independent of whether the underlying infrastructure is described as blockchain, a distributed ledger, or simply a well-built neutral escrow platform, because the core shift, moving custody away from either interested party and replacing private discretion with pre-agreed, transparent rules, is what actually addresses the source of the distrust.
The broader significance of this shift extends beyond the convenience of any individual tenant getting their deposit back a few weeks sooner or with less argument. Financial precarity disproportionately affects renters relative to homeowners, and a security deposit, though modest in absolute terms compared to a mortgage down payment, often represents a genuinely significant portion of a renter’s available savings, particularly for lower-income tenants who are already paying a larger share of their income toward housing costs than higher-income renters typically do. A system that returns deposits more reliably, more quickly, and with a clearer evidentiary basis for any deduction has a real, if unglamorous, financial-inclusion dimension: it reduces the number of renters who experience a wrongful or delayed deposit withholding as a genuine financial emergency, and it reduces the burden on renters least equipped to fight a drawn-out small claims dispute over money they may need immediately for their next security deposit and first month’s rent elsewhere. This is a case where a comparatively unglamorous piece of financial infrastructure has a disproportionate effect on the people with the least financial cushion to absorb its current failures.
None of this should be mistaken for a claim that the underlying technology has already solved the security deposit problem for renters broadly. The case studies examined in this article are real and verifiable, but they are also, honestly, adjacent rather than direct evidence for the long-term rental deposit use case specifically: a home-purchase escrow product that processed genuine volume but serves a different kind of one-time, sophisticated-party transaction, and a short-term booking settlement system that operated and was meaningfully upgraded over time but governs stays of days rather than a multi-year tenancy. The jurisdiction-specific compliance burden facing a genuine long-term rental deposit product remains a real and largely unsolved legal challenge, not a minor implementation detail, and the question of who fairly arbitrates a genuinely disputed damage claim once the procedural facts are settled remains open regardless of how tamper-evident the record is. What has genuinely changed, and what these two cases credibly demonstrate, is that the foundational mechanism, neutral custody with programmed release conditions, works in live financial transactions involving real money, rather than existing only as a conceptual proposal. Whether that mechanism reaches the harder problem of long-term residential security deposits at real scale depends less on the technology itself and more on whether an institution with the resources to solve the underlying legal complexity decides this corner of the rental market is worth building for.
FAQs
- What does “blockchain escrow” actually mean for a security deposit?
It means the tenant’s deposit is placed under the custody of a neutral, programmed smart contract at lease signing rather than sitting directly in the landlord’s own account. The funds are released — to the tenant, to the landlord, or split between them — only when pre-agreed, transparent conditions are met, such as an uncontested move-out inspection or the expiration of a claim-filing window, and the resulting record is difficult for either party to alter after the fact. - Does blockchain escrow guarantee a security deposit dispute will never happen?
No. A neutral ledger can guarantee that procedural facts, such as when a claim was filed and whether proper notice was given, are recorded accurately and cannot be silently changed later. It cannot determine whether a specific damage claim is fair, since that still requires human judgment or arbitration. What it does is narrow disputes to genuine, substantive disagreements rather than the procedural record-keeping arguments that dominate many conventional deposit disputes. - Are there real, working examples of blockchain-based escrow, or is this still mostly theoretical for rentals?
Long-term rental security deposits specifically remain an early-stage niche without a large, long-running deployment built exclusively for that use case. However, the same underlying smart-contract-escrow mechanism has operated at real scale in adjacent transactions: Propy Title & Escrow closed more than one hundred million dollars in home-purchase deals on blockchain in 2022, and Dtravel settled a two-thousand-dollar short-term rental booking entirely through a smart contract in August 2022, later upgrading that system in January 2023. - Is Propy’s blockchain escrow the same thing as a rental security deposit system?
No. Propy Title & Escrow is built for one-time home-purchase closings involving buyers, sellers, and title professionals, not for holding a tenant’s deposit over a multi-year lease. It is included in discussions of rental deposit escrow because it demonstrates the same neutral, smart-contract-based custody mechanism working at genuine transactional scale, which is a meaningful proof point even though the specific transaction type differs. - How is Dtravel’s booking settlement relevant to long-term rental deposits?
Dtravel settles short-term hospitality bookings, typically lasting days, through smart contracts rather than a centralized platform intermediary, which is structurally similar to how a deposit escrow would hold and release a tenant’s funds. It is not a long-term tenancy product, and the legal framework governing a short stay differs considerably from residential landlord-tenant law, but it is a documented, verifiable example of the same custody mechanism operating continuously in a real consumer transaction. - Why do security deposits cause so many disputes under the traditional system?
Traditional deposits sit in an account only the landlord controls, subject to state rules on interest and holding periods that vary widely and are inconsistently enforced, and released according to an itemized deduction process the landlord largely controls unilaterally. Tenants have limited practical recourse beyond small claims court, which many renters never pursue given the time and cost involved relative to the amount typically at stake. - What are the biggest obstacles to blockchain-based rental deposit escrow becoming common?
The two most significant are the deeply state-specific and consumer-protection-oriented nature of landlord-tenant law, which a smart contract cannot simply code around without careful jurisdiction-by-jurisdiction implementation, and the uneven cost of adoption, which makes these systems easiest to deploy for large property management companies and hardest for the smaller, independent landlords who make up a large share of the rental market. - Who decides a dispute if a landlord and tenant genuinely disagree about damage after a blockchain-escrowed deposit claim is filed?
This depends on the specific platform’s design. Some systems route unresolved disputes to a designated third-party arbitrator built into the escrow agreement, while others fall back to the same small claims court process that would otherwise handle the dispute. Neither approach is universally settled as the fairest option, particularly since a platform’s built-in arbitration mechanism could be perceived as favoring its paying landlord customers. - Will blockchain escrow eliminate the need for security deposit laws and regulations?
No. If anything, a rental-deposit-specific escrow system has to correctly implement existing state and local deposit laws, including interest requirements, maximum amounts, and itemization deadlines, rather than replace them. The technology changes how custody and release are enforced; it does not remove the underlying legal framework that defines what a fair deposit process actually requires. - What should a renter actually expect to change if their landlord adopts blockchain-based deposit escrow?
A renter using such a system can generally expect continuous visibility into their deposit’s status, an automatic full return if the landlord files no claim within the agreed window, and a clearer, timestamped record if a dispute does arise, rather than relying entirely on the landlord’s word or a private bank statement. The underlying ledger technology itself remains mostly invisible to the renter, who experiences it as a more transparent and faster version of the deposit process they already go through.