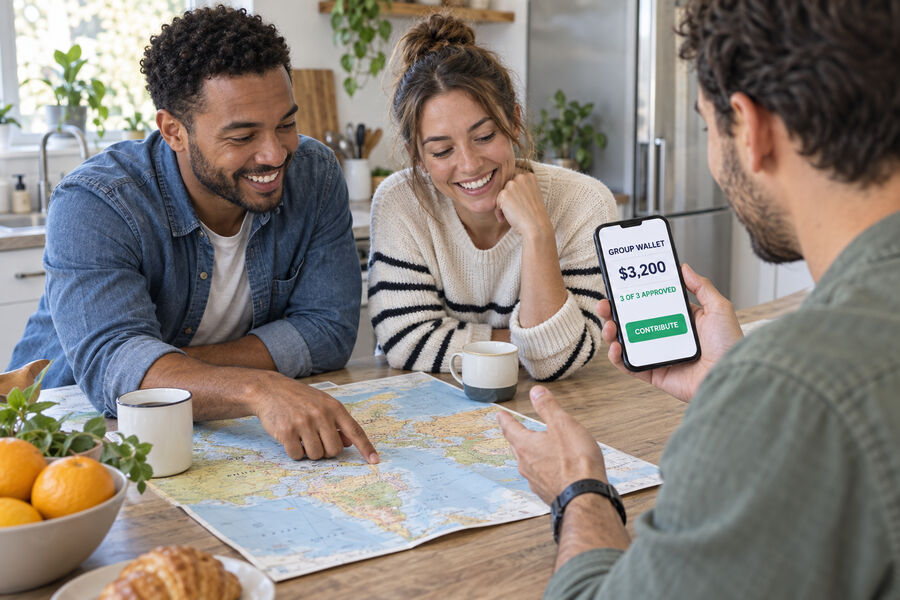
Every group that has ever tried to save money together eventually produces one person who becomes, informally and usually without ever agreeing to it, the treasurer. Someone has to book the vacation rental deposit before the group has actually collected enough money to cover it. Someone has to keep the spreadsheet of who paid for groceries during the family reunion and who still owes for the rental car. Someone has to be the name on the joint account, the person whose venmo balance briefly holds four other people’s rent money before it goes out the door to a landlord, or the sibling who ends up fronting a parent’s medical equipment bill while waiting for three other siblings to send their share. That person did not apply for the job. They were simply the one who was organized enough, or trusted enough, or simply present enough at the right moment, to end up holding everyone else’s money and everyone else’s expectations at the same time.
This arrangement works, most of the time, because most groups are made of people who genuinely like and trust each other. But it also quietly asks the treasurer to absorb a set of risks and burdens that the rest of the group rarely thinks about. If the treasurer’s personal bank account gets frozen, garnished, or simply overdrawn by an unrelated bill at the wrong moment, the group’s money is caught up in that mess along with it. If the treasurer forgets to log a payment, or miscounts a Venmo request, or simply loses track amid a dozen other financial obligations, the resulting confusion falls on everyone, and untangling it usually requires someone to have kept careful records that, in practice, few people actually keep. And if the group ever disagrees about how the money should be spent, there is no real mechanism for resolving that disagreement other than the treasurer’s own judgment, backed by whatever goodwill the group still has for them. None of this is a hypothetical concern reserved for large sums of money or formal organizations. It happens constantly in the ordinary, unglamorous context of splitting a beach house, saving toward a parent’s care, or pooling birthday money for a group gift, precisely because these are the situations where no one thought to set up anything more formal than a shared spreadsheet and a lot of trust.
A newer category of financial tool is emerging to address this specific gap, built on the same underlying technology that already secures tens of billions of dollars for decentralized organizations, crypto-native businesses, and blockchain protocol treasuries: the multi-signature wallet, or multisig for short. Instead of one person holding a group’s money in their own name, a multisig wallet places funds under the shared control of the group itself, structured so that no single person can move money alone and every group member can see, at any moment, exactly how much is in the pool and exactly what has been proposed, approved, or spent. A withdrawal only executes once a pre-agreed number of group members have approved it, and every contribution, proposal, and payout is recorded on a shared, tamper-evident ledger that nobody can quietly alter after the fact. Applied to a group of friends saving for a trip, a family pooling money for a shared expense, or a handful of people splitting the cost of a joint purchase, this removes the treasurer’s outsized burden and replaces it with something closer to genuine shared custody.
It is worth being direct from the outset about how early this specific consumer application actually is. The underlying multisig infrastructure this article examines, principally Safe, formerly known as Gnosis Safe, and Squads Protocol on Solana, is proven at real, independently documented scale, but that scale has been built almost entirely around decentralized autonomous organization treasuries, crypto-native businesses, and institutional or developer use, not around a specific consumer product for splitting a vacation fund with five friends. This article treats that gap honestly rather than glossing over it. What follows explains how a shared multisig wallet actually works, what a group of contributors, an organizer, and a recipient each see when they use one, the real benefits and real limitations of moving group money onto this kind of shared, transparent custody, and what the verified track record of the underlying technology does and does not tell us about whether it is ready for the ordinary, everyday work of a family savings pool or a friend group’s next trip.
The Problem: The Burden of Being “The Treasurer”
The treasurer problem begins with a basic asymmetry in how shared expenses actually get paid. Bookings, deposits, and large purchases rarely wait for a group to finish collecting money from every member at a convenient pace. A vacation rental typically requires a deposit weeks or months before the trip, often before everyone in the group has even confirmed they are coming, let alone sent their share. A family pooling money to help a relative with an unexpected expense cannot wait for the slowest contributor to get around to a bank transfer while a bill sits unpaid. In nearly every case, someone ends up paying first and collecting later, which means that person is temporarily, and sometimes not so temporarily, carrying the financial exposure for the entire group. If a member of the group backs out, sends less than agreed, or simply forgets, the treasurer is the one left holding the shortfall, often without a clean way to enforce repayment beyond an awkward conversation.
Layered on top of this timing problem is a tracking problem that turns out to be surprisingly difficult to solve with the tools most groups actually reach for. A shared spreadsheet requires someone to update it consistently, and the moment one contribution or reimbursement goes unrecorded, the whole document becomes suspect, since nobody else in the group has an independent way to verify whether the numbers are actually right. Payment apps built for peer-to-peer transfers were designed around one-to-one payments, not shared pools, so a group using them for a collective fund is typically stitching together a series of individual transfers into one person’s account and hoping that person’s own running total, kept in their head or in a separate note, stays accurate over weeks or months. None of these tools were built to answer the specific question a contributor actually wants answered, which is not “did I send my share” but “is the group’s money, all of it, still there, and can I see what it has been spent on.”
This is where the social cost of the arrangement becomes as significant as the financial one. Money problems among friends and family are uncomfortable to raise even when everyone involved is acting in good faith, and the structure of a single-custodian shared fund all but guarantees that questions will eventually arise: whether a payment was actually made on time, whether an expense was fairly allocated, whether the person holding the money spent it exactly as agreed. Raising these questions requires either trusting the treasurer’s word entirely or asking them to produce records that may or may not exist in a form anyone else can independently verify, and either path can strain a relationship that the shared goal was supposed to strengthen rather than test. A family pooling money for a parent’s care, in particular, often carries an additional layer of emotional weight, where a sibling who feels excluded from visibility into how shared funds are being spent can develop resentment that has little to do with the actual figures and everything to do with the opacity of the arrangement itself.
Even when a treasurer is scrupulously honest and organized, the arrangement still concentrates risk in a way that has nothing to do with anyone’s character. A treasurer’s personal bank account is subject to that individual’s own financial life: an overdraft fee triggered by an unrelated transaction, a fraud hold placed by the bank, a dispute with an ex-partner over a jointly held account, or simply the treasurer’s own unrelated bills competing for the same balance, can all delay or complicate a group’s money without any member of the group having done anything wrong. Group funds sitting inside one person’s individual account also blur the line, both practically and sometimes legally, between that person’s own money and the group’s, which becomes a real problem if the treasurer passes away unexpectedly, faces a legal judgment, or simply needs to close that account for reasons that have nothing to do with the group at all. What ties all of these problems together is the absence of a structure where the group’s money is genuinely the group’s, visible and controlled collectively, rather than sitting inside a single, ordinary bank account that one person happens to control on everyone else’s behalf.
What a Shared Multisig Wallet Actually Means
A multi-signature wallet, at its core, is a shared account that requires more than one authorized party to approve a transaction before it executes. Rather than a single private key or a single login controlling the funds, a multisig wallet is configured with a defined group of signers and a threshold, commonly written as “M-of-N,” meaning that any M signers out of the total N authorized members must approve a given transaction before it goes through. A group of five friends might set up a wallet requiring three of the five to approve any withdrawal, meaning no individual member, including whoever originally set up the wallet, can move the group’s money alone, and no small minority of the group can either. This is the property that most directly answers the treasurer problem: custody of the funds belongs to the group as a structure, not to any one person’s individual account or judgment.
Because a multisig wallet typically runs on top of a blockchain, every contribution, every proposed transaction, and every approval or rejection is recorded on a shared ledger that every member of the group can independently check at any time, rather than relying on one person’s spreadsheet or memory. This is the same tamper-evident property that makes blockchain-based systems useful in other financial contexts: once a transaction is confirmed and added to the record, altering it after the fact would require rewriting that entry across the distributed network validating the ledger, which becomes impractical as more independent participants are involved. Applied to a group fund, this means that when a contributor sends money into the shared wallet, that contribution becomes a permanent, visible part of the fund’s history that no other member, including whoever manages the wallet’s interface, can quietly edit or delete later.
It is worth being precise, in the same way this article has been about other financial technologies, regarding what this property does and does not guarantee. A multisig wallet can guarantee that funds only move when the agreed threshold of the group’s members has approved the transaction, and that the resulting record of contributions, proposals, and payouts cannot be silently altered afterward. It cannot guarantee that the group agreed on sensible spending rules in the first place, that every member understands how to use the wallet’s interface correctly, or that a dispute over whether a particular expense was fair will resolve itself simply because the underlying transaction history is transparent. The technology solves the specific problem of concentrated, unverifiable custody; it does not solve the separate, harder problem of a group actually agreeing on how their shared money should be spent. That still depends on the group setting clear expectations up front, in much the same way a well-run informal fund would benefit from clear expectations even without any blockchain technology involved at all.
Given that limitation, the genuine value of a shared multisig wallet comes from combining threshold-based approval with a transparent, continuously visible record that every contributor can check without needing to ask anyone’s permission or trust anyone’s private accounting. A well-designed consumer wallet built on this infrastructure does not require every member of a friend group or family to understand private keys, gas fees, or blockchain terminology directly; in the products actually built on top of Safe and Squads, a typical user’s experience is closer to a familiar app interface, showing a running balance, a history of contributions, and a simple approve-or-reject prompt when a payment has been proposed, with the underlying signing and ledger mechanics handled behind the scenes. The tradeoff is that the group still has to agree, at setup, on who the signers are and what threshold to require, and a poorly chosen threshold, whether too strict or too loose, can recreate some of the same friction the wallet was meant to eliminate, which is why understanding how approval actually works in practice matters before any group adopts one of these tools for a real shared goal.
How Multisig Approval Works Step by Step
Consider a concrete example: five friends decide to save toward a shared vacation rental, and they set up a multisig wallet requiring three of the five to approve any transaction before it executes. The first step is funding, where each friend sends their contribution into the shared wallet at whatever pace suits them individually, rather than routing that money through one person’s personal account first. Each contribution appears immediately in the wallet’s shared transaction history, visible to all five friends at once, so nobody has to ask whether a particular person has paid their share yet; the record already shows it, along with the date and amount, in a form none of the five can alter after the fact.
When the group is ready to pay the rental deposit, any one of the five friends can initiate, or “propose,” the transaction, specifying the amount and the recipient. This proposal does not move any money by itself. It sits in a pending state, visible to the whole group, until enough of the other signers review and approve it. In this example, two more of the five friends, in addition to whoever proposed it, need to approve the transaction before it actually executes and the funds leave the wallet. If a friend disagrees with the proposed payment, perhaps they think the amount is wrong or the timing is premature, they simply do not approve it, and if the transaction cannot gather the required three approvals, it never executes at all. This is a meaningful structural difference from a single-custodian account, where the person holding the funds could, in principle, make a payment the rest of the group disagreed with and the group would only find out after the fact.
Once the threshold of approvals is reached, the transaction executes automatically according to the wallet’s programmed rules, and the payment goes out to the specified recipient, whether that is a vacation rental company, a family member needing reimbursement, or a vendor for a group purchase. The completed transaction then becomes a permanent part of the wallet’s shared history alongside the original contributions, so that at any later point, any member of the group can review exactly when the deposit was paid, how much it was, who proposed it, and which three of the five members approved it. This creates a complete, auditable trail from the first dollar contributed to the last dollar spent, something that virtually no informal group fund arrangement can produce without significant, ongoing manual effort from whoever happens to be keeping the records.
The threshold itself is a deliberate design choice that groups have to make when setting up the wallet, and getting it right matters for how smoothly the arrangement actually functions day to day. A threshold set too low, such as requiring only one approval out of five, defeats much of the purpose, since it recreates a situation where a small number of people, or even one person if the group is careless about who holds signing rights, can move funds without genuine group consensus. A threshold set too high, such as requiring approval from all five members for every transaction, can make the wallet frustratingly slow to use in practice, since it only takes one unavailable or unresponsive member to stall a routine payment. Most groups using these tools in practice settle on a threshold requiring a clear majority, enough to ensure no small minority can act unilaterally, but not so high that ordinary transactions become hostage to a single member’s availability.
What Contributors, Organizers, and Recipients Each See
For an ordinary contributor to a shared fund, the underlying multisig mechanics are largely invisible; what they interact with is typically a simple balance view showing the current total in the pool, a running history of contributions from every member, and, when relevant, a notification that a payment has been proposed and needs their review. Because this view is drawn directly from the same record that governs the actual movement of funds, rather than a summary someone else compiled by hand, a contributor checking their group’s wallet has a genuinely verifiable answer to the question an informal fund almost never answers cleanly: exactly how much money is in the pool right now, and exactly what has it been spent on so far. This alone addresses much of the quiet anxiety that builds up around informal group funds, where contributors are otherwise left trusting a running mental tally that only one person actually maintains.
For whoever takes on the informal organizing role, which still exists in a multisig arrangement even though that person no longer has unilateral control over the money, the experience shifts from being solely responsible for the group’s funds to being one proposer and approver among several. An organizer can still take the lead on suggesting when a deposit should be paid or drafting a proposed transaction, but they no longer carry the full weight of the group’s trust on their own, since the wallet’s own rules, rather than their personal judgment alone, determine whether a transaction actually executes. This is a meaningful psychological shift for the person who would otherwise default into the treasurer role, since it converts a position of sole responsibility and exposure into one of shared stewardship, where a mistaken or disputed proposal simply will not gather the approvals needed to go through.
For a recipient outside the group, such as a vacation rental company, a family member receiving reimbursement, or a vendor being paid for a group purchase, the multisig structure is generally invisible altogether; they simply receive a payment once the group’s internal approval process has run its course, with no need to understand or interact with the underlying wallet at all. This matters because it means the added transparency and shared control benefiting the group internally does not create any additional friction or complexity for the outside party being paid, which is part of why these tools can slot into existing group financial habits, such as paying a deposit or settling a shared bill, without requiring the vendor on the other end to change anything about how they accept payment.
Taken together, these different vantage points, a simple reassuring balance view for contributors, a shared proposal-and-approval workflow for whoever organizes the group’s spending, and an unchanged, ordinary payment experience for outside recipients, are what a shared multisig wallet actually looks like in daily use. What unites all three is that they draw from the same underlying, tamper-evident record rather than from one person’s private account and private memory, which is the structural shift that moves a group fund from depending on individual trust to depending on a transparent, collectively controlled system.
Benefits Across the Group
For ordinary contributors, the most immediate benefit of a shared multisig wallet is the elimination of the specific anxiety that comes from sending money into someone else’s account and simply hoping it is being tracked correctly. A contributor no longer has to ask a friend or family member to confirm receipt of a payment, or wonder whether a Venmo transfer sent weeks ago was properly logged against the group’s shared expenses, because the wallet’s own record already answers that question definitively and immediately. This shift, from relying on another person’s bookkeeping to checking a shared, independently verifiable record, is the single most direct improvement multisig wallets offer to the person who is neither organizing the fund nor receiving payments from it, and it applies whether the group in question is five friends splitting a vacation or four adult siblings pooling money for a parent’s expenses.
For whoever would otherwise default into the treasurer role, the benefit is more structural than emotional, though it carries an emotional dimension as well. That person no longer personally absorbs the financial exposure of fronting money before the group has fully contributed, since the wallet only pays out what has actually been collected, and they no longer carry sole legal and practical responsibility for funds that technically belong to the whole group. This matters in ways that go beyond convenience: if a dispute ever arose over how shared money had been handled, a person who had been informally serving as treasurer under a conventional arrangement would have very little to point to beyond their own word and whatever records they happened to keep, whereas a multisig arrangement produces an objective, shared record that protects the organizer from being unfairly blamed for a decision the whole group actually participated in approving.
Families managing multi-generational shared goals, such as a fund set aside for a parent’s long-term care or a pool of money multiple adult children contribute to on an ongoing basis, gain a benefit that is particularly relevant given how emotionally charged money conversations within families can become. A transparent, jointly controlled fund removes the specific and common source of family friction where one sibling, often the one geographically closest to an aging parent, ends up managing shared money and inevitably faces questions, fair or not, about whether every dollar was handled appropriately. Because every contribution and every expenditure is visible to every participating family member in real time, the kind of slow-building suspicion that can develop around an opaque, single-custodian family fund has much less room to take root, since any family member can check the actual record rather than relying on secondhand summaries or periodic updates.
Vendors, recipients, and anyone else being paid out of a shared fund benefit indirectly but genuinely from the reliability this structure creates on the group’s side. A group using a multisig wallet with a sensible threshold is less likely to experience the kind of internal breakdown, a treasurer who becomes unreachable, a dispute that stalls payment entirely, or a simple bookkeeping error that delays a deposit, that can otherwise disrupt a scheduled payment to an outside party. Across every participant in this arrangement, contributors, organizers, family members managing shared care costs, and the outside parties ultimately being paid, the underlying benefit is structurally consistent: a transparent, collectively controlled record substitutes for the concentrated trust and informal bookkeeping that has defined shared group funds for as long as people have pooled money together, and that substitution reduces friction differently for each participant while adding up to a calmer, less disputed process overall.
Documented Case Studies in Multisig Infrastructure
The distance between the theoretical appeal of a shared, transparent group wallet and what has actually been built and used at real scale deserves the same honest treatment this article has applied to every other claim it makes. It is worth being direct: the “friends and family vacation fund” application specifically is a genuinely thin, nascent category, and there is no single, large-scale, independently documented consumer product built exclusively for splitting vacation costs or family savings pools with the kind of multi-year, audited track record that would let this article point to it the way it can point to more mature technologies elsewhere. What does exist, and what deserves careful examination, is the underlying multisig infrastructure that any consumer group-wallet product would necessarily be built on top of, and that infrastructure has been tested at a scale and duration that few blockchain technologies can match.
Two projects in particular illustrate this underlying infrastructure at genuine, independently verifiable scale: Safe, the dominant multisig and smart-account standard on Ethereum and other EVM-compatible chains, and Squads Protocol, the leading equivalent on Solana. Both have published, dated, independently reportable figures rather than vague claims of adoption, and both have track records spanning years rather than months. Neither was built specifically for consumer friend groups or family savings pools. Both have been proven overwhelmingly through decentralized autonomous organization treasuries, crypto-native businesses managing operating funds, and institutional or developer use, which is a meaningfully different proof point than evidence of mainstream consumer adoption for the vacation-fund and family-pool use cases this article is centrally concerned with. That distinction matters, and this article draws it explicitly rather than letting the scale of the underlying infrastructure imply a level of consumer adoption it has not actually demonstrated.
The value of examining these two cases carefully is not that they prove multisig wallets are already popular among friend groups and families. It is that they demonstrate the specific technical claims this article has made about multisig wallets, threshold-based approval, tamper-evident shared records, and resistance to unilateral tampering, have been tested against real money, at real scale, under real audit scrutiny, for long enough that the underlying mechanism can reasonably be described as proven infrastructure. Whether that proven infrastructure eventually supports a genuinely popular consumer application for group goals is a separate, and still open, question that this article returns to directly in the sections that follow.
Safe: The Infrastructure Layer Behind Billions in Shared Custody
Safe, known until 2022 as Gnosis Safe, is the most widely used multisig and smart-account infrastructure in the Ethereum ecosystem and across other EVM-compatible blockchains, and its own published reporting gives a clear, dated picture of its scale. According to Messari’s “State of Safe” report covering the third quarter of 2024, Safe held more than seventy-two billion dollars in assets across over twenty-five million deployed smart accounts at the close of that quarter, with 1.6 million weekly active accounts, a figure that had declined 22 percent quarter over quarter as broader crypto market activity cooled. That same report noted Safe had reached an all-time high of one hundred and six billion dollars in secured assets earlier in 2024, illustrating how closely Safe’s reported figures track the broader volatility of crypto markets rather than representing a steadily climbing line.
More recent, and independently published, figures come directly from the Safe Ecosystem Foundation’s own Q1 2026 quarterly report, released on April 23, 2026. As of that report, Safe secured 35.25 billion dollars in assets, described by the foundation as more than one-third of total decentralized finance value locked across EVM-compatible chains, across a cumulative total of 61.11 million deployed accounts, with 2.21 million net new accounts created during the first quarter of 2026 alone. The same quarter saw 122.9 million total transactions processed through Safe accounts, and the foundation specifically noted that March 2026 set two records in the protocol’s history: the largest single-month increase in new accounts, at 852,000, and the highest monthly transaction volume, at 50.9 million transactions. The foundation reported this growth as occurring specifically during a broader market downturn, framing sustained account creation and transaction volume during a bear market as evidence of Safe’s role as durable, structural infrastructure rather than activity that only appears during speculative market peaks. Over its full operating history, Safe has processed more than 1.4 trillion dollars in cumulative transaction value.
It is worth being precise about what these figures do and do not demonstrate for the consumer group-goals application this article is centrally about. Safe’s own public materials and its adoption pattern, reflected in Messari’s reporting on which specific blockchain networks drove the majority of its active users and asset growth, describe a tool built overwhelmingly for decentralized autonomous organizations managing treasuries, crypto businesses safeguarding operating funds, and increasingly institutional users moving traditional financial products on-chain, including a euro-denominated yield product Safe’s commercial arm launched in partnership with a subsidiary of Société Générale in early 2026. None of Safe’s own published reporting describes meaningful, measured adoption specifically by informal consumer groups pooling money for vacations, family savings, or shared purchases, and this article does not claim otherwise. What Safe’s track record does demonstrate, credibly and at a scale few competing technologies can match, is that the specific mechanism this article has described, multiple independent signers jointly controlling shared funds through a tamper-evident, threshold-based system, functions reliably with tens of billions of dollars in real assets under real, sustained, multi-year usage, which is the necessary technical foundation any consumer-facing group wallet product would have to build on.
Squads Protocol: Multisig Security Proven at Institutional Scale on Solana
Where Safe represents the dominant multisig standard across Ethereum and other EVM-compatible chains, Squads Protocol occupies the equivalent position on Solana, and its development history offers a particularly clear, dated illustration of how seriously this category of infrastructure has been tested before being trusted with meaningful sums of money. Squads launched its third major version of its multisig program and, after roughly six months of live, monitored operation, made that version’s code immutable in February 2023 by permanently burning the upgrade authority that would have allowed Squads Labs or anyone else to alter the deployed program afterward. This is a meaningful and verifiable security commitment specifically because it is irreversible: once the upgrade authority is burned, not even the team that built the software can quietly patch or modify the contract governing users’ funds, which is a stronger guarantee against insider tampering than a conventional software product, where the operating company generally retains the ability to push changes unilaterally.
Squads subsequently built a fourth version of its protocol that expanded well beyond basic threshold approval, adding time-locked transactions that impose a mandatory delay before certain payments execute, sub-accounts that let a single multisig manage several separated pools of funds under one shared governance structure, and granular roles distinguishing who can propose a transaction, who can vote to approve it, and who can execute an already-approved transaction, along with configurable spending limits for routine, lower-risk payments. This version underwent seven separate security audits from established blockchain security firms including OtterSec, Neodyme, and Trail of Bits, and in late 2023, Certora completed a formal verification report on the Squads v4 program, using mathematical proof techniques to rule out entire categories of possible contract bugs rather than relying solely on manual code review. Certora’s own reporting describes this as the first formally verified smart contract program on the Solana network, a distinction that reflects a materially higher bar of scrutiny than a standard security audit alone, and Certora conducted additional verification passes on the protocol in December 2024 and January 2025 as the codebase continued to evolve.
Squads’ own published materials describe the protocol as securing more than fifteen billion dollars in assets and having processed more than five billion dollars in stablecoin transfers, serving more than four hundred and fifty teams along with a large number of individual users. In April 2026, Squads announced an eighteen million dollar strategic funding round led by Solana Ventures, with participation from Coinbase Ventures, Haun Ventures, and several other established crypto-focused investment firms, bringing the protocol’s total funding to just under forty-three million dollars, with the company describing the new capital as accelerating a business finance product built on top of its existing multisig infrastructure. As with Safe, it is important to describe this adoption accurately rather than overstate its relevance to the specific consumer application this article examines: Squads’ own public framing of its growth centers on decentralized autonomous organizations, developer teams, and increasingly business and stablecoin-banking use cases, not on consumer friend groups or family savings pools, and its most recent funding round was explicitly directed toward expanding institutional and business-facing products rather than a consumer group-goals offering. What Squads’ verified history does establish is that the underlying mechanism, a multisig architecture audited repeatedly and formally verified by independent security specialists, has operated without a major exploit while securing billions of dollars for hundreds of organizations over several years, which is a rigorous, independently confirmed foundation for any application layer that might eventually build a genuinely consumer-facing group wallet on top of it.
Limitations, Costs, and Open Questions
The most significant limitation facing shared multisig wallets for the specific use cases this article is centrally about, vacation funds, family savings, and group purchases among friends and relatives, is the gap between the proven, institutional-scale infrastructure examined in the case studies above and the comparatively thin, early evidence of genuine consumer adoption for these exact applications. Safe and Squads have each demonstrated, convincingly and at real scale, that the underlying multisig mechanism works reliably with large sums of money over sustained periods. Neither has demonstrated, at anything close to the same scale or duration, that ordinary consumer groups are actually adopting purpose-built products for splitting a beach house or saving toward a family goal. A handful of newer applications built on top of this infrastructure, including consumer-facing tools that describe themselves as offering shared “squad wallets” for splitting group expenses on Solana, illustrate that a genuine application layer is beginning to form, but this remains a small, early, and largely unproven category compared to the DAO-treasury and institutional use that Safe and Squads have actually built their track records on. It would be dishonest to present the billions of dollars secured by that underlying infrastructure as evidence that mainstream consumers have embraced multisig wallets for their vacation funds specifically, and this article does not make that claim.
A second, more practical limitation involves key management and account recovery, which matters enormously for a technology being proposed for non-technical users managing money with friends and family rather than developers or institutional treasury managers accustomed to handling cryptographic credentials carefully. In a multisig arrangement, each signer typically controls their own private key or, in more consumer-friendly implementations, a passkey or similarly managed credential, and losing access to that credential without a well-designed recovery mechanism can mean losing the ability to participate in approving the group’s transactions at all. A well-built consumer product built on top of Safe or Squads can mitigate this through modern account-recovery methods, but the underlying risk, that a group member becomes locked out of a shared fund through no fault of the group’s design, is real and distinct from the risks associated with a conventional bank account, where a forgotten password is a routine customer-support matter rather than a potential loss of funds.
Cost and complexity present a related, if smaller, obstacle. Transactions on most blockchain networks carry a network fee, and while fees on networks like Solana are generally minimal and fees on Ethereum-based networks have fallen substantially as scaling technology has matured, a group unfamiliar with the concept of network fees at all may find even a small, unexpected charge confusing or off-putting compared to a bank transfer or payment app they already understand intuitively. Groups holding funds in cryptocurrency rather than a stable, dollar-pegged asset also take on price volatility risk that a conventional savings pool never has to consider, since the value of a vacation fund denominated in a volatile asset could shrink meaningfully between the time it is contributed and the time it is spent, though many consumer-facing products address this specifically by denominating balances in dollar-pegged stablecoins rather than more volatile assets.
Finally, there remains a genuinely open question about dispute resolution that a transparent ledger does not, by itself, resolve. A multisig wallet can guarantee that a transaction only executes with sufficient approval and that the resulting record cannot be quietly altered, but it cannot determine whether a proposed expense is fair, whether a member who has stopped responding to approval requests should be removed from the signer group, or how a fund should be wound down and returned if the group’s shared goal falls apart entirely, such as a trip that gets canceled after money has already been pooled. These are exactly the kinds of judgment calls that still require the group to have agreed on ground rules in advance, and the technology’s transparency, while it removes ambiguity about what has already happened, does not by itself resolve a genuine disagreement about what should happen next. Groups adopting these tools benefit most when they treat the wallet as a structure that enforces agreed-upon rules rather than as a substitute for actually agreeing on those rules together beforehand.
Final Thoughts
Shared multisig wallets address a problem that is fundamentally social rather than technological: groups of friends and family have always been capable of pooling money toward a common goal, but they have rarely had a way to do it that did not require concentrating trust, risk, and administrative burden onto one person who never really volunteered for the job. A threshold-based, transparent wallet does not replace the underlying relationships or the goodwill that makes any group financial arrangement work in the first place. What it offers is a structural correction to an arrangement that has, for as long as people have pooled money together, quietly asked one person to carry a disproportionate share of the risk and the responsibility, and it replaces that concentration with a shared, verifiable record that every contributor can check for themselves rather than take on faith.
The broader significance of this shift extends beyond the convenience of any single friend group booking a vacation rental without incident. Financial trust between people who care about each other is built cumulatively, through many small interactions, and money is one of the few domains where even well-intentioned people can genuinely disagree about what happened or what is fair, precisely because informal arrangements rarely produce a record either side can point to with confidence. A tool that lets a family say, with real and verifiable confidence, exactly how much has been contributed toward a parent’s care and exactly how every dollar has been spent does more than streamline a logistical task; it removes a specific, recurring source of quiet family strain that has nothing to do with how much anyone actually cares about the person they are supporting and everything to do with the absence of a shared, trustworthy accounting. This has a genuine accessibility dimension as well, since the groups least equipped to absorb a treasurer’s mistake or a disputed expense, families operating on tight budgets, friend groups where a lost or delayed contribution creates real hardship rather than minor inconvenience, are disproportionately served by a system that removes ambiguity rather than depends on everyone having the cushion to absorb an error and move on.
None of this should be mistaken for a claim that shared multisig wallets have already become a mainstream way for ordinary people to manage group money. The underlying infrastructure examined in this article, Safe and Squads chief among it, is real, extensively audited, and proven at a scale spanning tens of billions of dollars, but that scale has been built almost entirely by decentralized organizations, crypto-native businesses, and increasingly institutional finance, not by friend groups saving for a beach trip or families pooling money for a shared goal. The application layer that would bring this same mechanism to those specific, everyday consumer use cases is still small, still new, and still has to prove that non-technical groups will actually adopt it over the spreadsheets, group chats, and single-custodian accounts they already know how to use. What has genuinely changed is that the hard technical problem, building a shared custody system that multiple independent people can trust without trusting each other individually, has been solved and independently verified at real scale. Whether that solved technical problem translates into something an ordinary family or friend group actually reaches for the next time they need to pool money together will depend less on the underlying cryptography, which has already been tested rigorously, and more on whether someone builds a genuinely simple, trustworthy consumer product on top of it and gives ordinary people a reason to leave the group chat and the spreadsheet behind.
FAQs
- What is a shared multisig wallet, in plain terms?
It is a shared account for a group’s money that requires more than one person’s approval before any funds can move. Instead of one person, such as a designated treasurer, holding and controlling a group’s pooled funds alone, the wallet is set up so a defined number of the group’s members, out of the total who hold signing rights, must approve any withdrawal or payment before it executes, and every contribution and transaction is recorded on a shared, tamper-evident ledger everyone in the group can see. - Does a multisig wallet guarantee a group will never disagree about money?
No. It guarantees that no transaction can execute without the agreed number of approvals, and that the resulting record cannot be silently altered afterward, which removes ambiguity about what has already happened. It does not resolve genuine disagreements about what should happen next, such as whether a proposed expense is fair, which still requires the group to have agreed on clear ground rules when they set the wallet up. - Are there real, proven examples of this technology working at scale, or is it still mostly theoretical?
The underlying multisig infrastructure is proven at real scale, though not specifically for consumer vacation funds. Safe, formerly Gnosis Safe, reported securing 35.25 billion dollars in assets across more than 61 million accounts in its Q1 2026 quarterly report, and Squads Protocol on Solana, whose v4 architecture was formally verified by Certora as the first such program on Solana, reports securing more than 15 billion dollars in assets. Both figures come primarily from decentralized organization treasuries and institutional use rather than consumer friend-group or family-fund adoption. - If Safe and Squads are built mainly for treasuries and businesses, why are they relevant to a friends-and-family vacation fund?
Because any consumer product offering a shared group wallet for vacations, family savings, or group purchases is almost certainly built on top of this same underlying multisig infrastructure rather than inventing a new custody mechanism from scratch. Examining Safe and Squads shows how thoroughly the core mechanism, threshold-based approval and a tamper-evident shared record, has been tested and audited, even though the specific consumer application built on top of it is much newer and far less proven. - Do all the members of a group need to understand cryptocurrency or blockchain technology to use one of these wallets?
Not in a well-built consumer product. In the underlying infrastructure this article examines, the technical signing and ledger mechanics run behind the scenes, and a typical user’s experience is closer to a familiar app showing a balance, a contribution history, and a simple approve-or-reject prompt when a payment is proposed, rather than requiring anyone to manage private keys or understand blockchain terminology directly. - What happens if one member of the group loses access to their account or stops responding?
This depends on the wallet’s configuration and the specific product built on top of it. A sensible signing threshold, such as requiring three approvals out of five rather than requiring unanimous agreement, prevents one unavailable member from freezing the whole group’s ability to transact. Losing access to a signing credential without a well-designed recovery method is a real risk in this technology, which is a meaningful difference from a conventional bank account where a forgotten password is typically a routine support issue rather than a potential loss of access to funds. - Is money held in a shared multisig wallet safe from being stolen or lost to a hack?
The specific infrastructure examined in this article has strong, independently verified security credentials, including Squads’ formal verification by Certora and its immutable, unalterable v3 codebase, and Safe’s multi-year history securing tens of billions of dollars. No financial technology is entirely without risk, and consumer-facing products built on this infrastructure still depend on sound key management and careful account setup by the group using them. - How is this different from just using a shared bank account or a payment app group chat?
A conventional joint bank account still typically requires trusting a bank’s own back-end systems and often does not require every group member’s approval for every transaction, while a payment app group chat is not really a shared account at all, just a series of individual transfers that someone has to track manually. A multisig wallet is specifically designed so no individual signer can move funds alone and every transaction is recorded on a record every member can independently verify, without relying on one person’s bookkeeping. - Is this technology actually being used by ordinary friend groups and families today, or is it mainly used by businesses and crypto organizations?
Today, the overwhelming majority of documented, large-scale usage of Safe and Squads comes from decentralized organizations, crypto businesses, and increasingly institutional finance, not from consumer friend groups or family savings pools. Purpose-built consumer applications for group expense-splitting and shared savings are beginning to appear on top of this infrastructure, but this remains a small and early category rather than a proven, widely adopted consumer use case. - What should a friend group or family actually expect if they try one of these tools for a shared goal?
They should expect a transparent, continuously visible record of every contribution and expenditure, along with the reassurance that no single person can move the group’s money without the agreed number of approvals. They should also expect to need to agree on practical ground rules in advance, such as who the signers are, what threshold to require, and how disputes will be handled, since the technology enforces agreed-upon rules rather than substituting for the group actually agreeing on them.