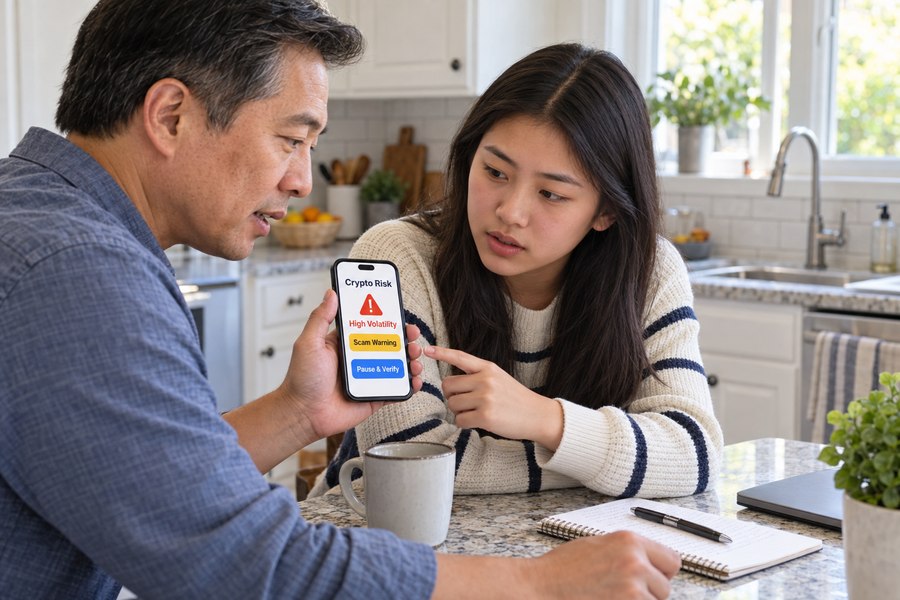
Somewhere between a TikTok video promising to turn fifty dollars into five thousand and a group chat where a classmate is bragging about a meme coin that tripled overnight, most teenagers today have already formed an opinion about cryptocurrency, whether their parents have said a single word about it or not. This is the reality that makes silence the riskiest option available to a parent right now. A teenager who hears nothing at home about digital assets does not simply remain neutral on the subject; they fill that vacuum with whatever a stranger on the internet, an algorithm optimized for engagement, or a slightly older friend with a strong opinion and no real expertise happens to be saying, and none of those sources have any obligation to mention the part where people lose money.
Crypto occupies an unusual place in a teenager’s financial education because it arrived without waiting for anyone’s permission. Stocks, savings accounts, and even student loans tend to enter a young person’s awareness gradually, often introduced by a parent, a school course, or a first job that requires a paycheck to be deposited somewhere. Cryptocurrency, by contrast, spread through gaming platforms, streaming culture, and social media first, reaching teenagers through channels that have nothing to do with formal financial education and everything to do with entertainment, community, and status. A fifteen-year-old can watch a livestreamer casually mention buying a token, see a highlight reel of someone’s crypto portfolio doubling, and absorb a set of assumptions about how money and risk work before ever sitting through a single lesson on compound interest or the difference between saving and speculating.
The stakes extend beyond any single teenager’s bank balance. A young person who loses money to a fraudulent crypto scheme, or who watches a friend do so, often absorbs a broader and more damaging lesson than the specific financial one, concluding either that all investing is a rigged game not worth trying or that recovering losses simply requires taking a bigger, riskier bet the next time. Both conclusions can shape financial behavior well into adulthood, long after the specific token or platform involved has been forgotten. The relationship between parent and teenager is also on the line in a quieter way: a teenager who feels dismissed or lectured the first time they bring up crypto is unlikely to bring up the next financial question that actually matters, whether that concerns a student loan, a first credit card, or a job offer that sounds too good to be true, making the tone set in this first conversation about crypto a template for every subsequent money conversation the family will have.
This guide is built on a simple premise: parents do not need to become blockchain experts to have a genuinely useful conversation with their teenager about crypto. What they need is a framework for approaching the topic with curiosity instead of alarm, enough grounding in the fundamentals to ask good questions, and an honest accounting of what has actually gone wrong when young people have gotten involved with digital assets without guidance. That last piece matters enormously. Vague warnings that something is “risky” tend to bounce off a teenager who has already seen someone their own age post screenshots of real gains, but a specific, well-documented account of how a real scheme worked, who it targeted, and what it cost the people involved tends to land very differently, because it replaces a lecture with a story that has consequences a teenager can actually picture.
The approach here also treats teenagers as capable of nuance rather than needing to be steered entirely away from a subject that genuinely interests them. Cryptocurrency is not purely a scam, and treating it as one in conversation will likely cost a parent their credibility the moment their teenager encounters a counterexample, whether that is a legitimate blockchain-based project, a friend who did make money, or simply accurate information contradicting an oversimplified warning. At the same time, the technology’s genuine complexity, its extreme price volatility, and the sheer volume of fraud built specifically to target inexperienced, emotionally invested newcomers make it a poor fit for a teenager to explore entirely on their own, without any adult perspective in the mix.
What follows moves from context to action. It starts by examining why crypto has become such a fixture in teenage online culture in the first place, grounded in real survey data about how young people actually encounter and think about digital assets. It then turns to the harder material: a documented case in which a teenager’s involvement with cryptocurrency theft produced a settlement worth tens of millions of dollars, alongside the everyday scam tactics that specifically target young, online, financially inexperienced people. From there, the guide shifts toward what a parent can actually do, offering a practical structure for opening the conversation, a plain-language walkthrough of the concepts a teenager needs in order to think critically about crypto, and an honest look at how one major family finance platform has chosen to handle the subject for millions of young users. The goal throughout is not to produce a teenager who avoids cryptocurrency forever, but one who can recognize hype, ask sharper questions, and understand risk well enough to make decisions, about crypto and about money more broadly, with their eyes open.
Why Crypto Already Lives in Your Teen’s World
Long before most teenagers have any disposable income to invest, they have already been marketed to, informed, and in many cases persuaded about cryptocurrency through channels that have nothing to do with a bank or a brokerage. Gaming platforms popularized the idea of digital items with real monetary value years before most people had heard the word blockchain, normalizing the underlying concept that something existing only as data on a screen could still be bought, sold, and treated as genuinely valuable. Streaming platforms and social video apps layered a second influence on top of that foundation, turning crypto price movements into a genre of content in their own right, complete with dramatic reaction videos, screenshotted gains, and a steady stream of creators whose entire audience-building strategy depends on convincing viewers that they, too, could be early on the next big opportunity.
The research bears out just how central this pathway has become for the youngest adult cohort now entering financial markets. In a survey fielded in November and December of 2022 among Gen Z respondents ages eighteen to twenty-five, the FINRA Investor Education Foundation and the CFA Institute found that cryptocurrency ownership among young American investors had reached 55 percent, with even higher figures reported among Gen Z investors in Canada at 57 percent, according to the resulting report, “Gen Z and Investing: Social Media, Crypto, FOMO, and Family,” released in May 2023. For a significant share of this generation, the report noted, crypto was not a supplementary bet layered on top of a more conventional portfolio of stocks and retirement accounts; it was the very first thing they ever invested in, meaning an entire cohort of young adults is learning the basic emotional and financial rhythms of investing, the excitement of a gain, the sting of a loss, the pull to check a balance constantly, through one of the most volatile asset classes available rather than through a more measured starting point.
The same research sheds useful light on where these young investors are actually getting their information, and the answer should reframe how parents think about their own role in the process. Social media ranked as the leading source of financial information for Gen Z investors in the United States, cited by 48 percent of respondents, narrowly ahead of general internet searches at 47 percent, with parents and family members trailing in third place at 45 percent. Fear of missing out, commonly abbreviated as FOMO, was cited by 41 percent of Gen Z investors surveyed in both the United States and Canada as a factor in their decision to start investing at all, and a striking 82 percent of American respondents said they had begun investing before turning twenty-one, meaning the habits, instincts, and information sources they build during the teenage years, well before this survey’s eighteen-to-twenty-five sampling window even begins, are likely already shaping how they will behave once they are old enough to be counted in the data.
Beyond broad platform trends, the specific communities where teenagers spend their time online tend to reinforce crypto’s normalization in ways that are easy for parents to miss entirely. Discord servers built around a specific game or content creator frequently include dedicated channels for discussing token prices or trading strategies, treated with the same casual, ongoing familiarity as a channel for sharing gameplay clips or scheduling matches. Group chats among classmates function similarly, turning a market move into a piece of social currency, something to reference, joke about, or use to establish status within the group, independent of whether anyone involved actually understands what they are discussing. This ambient, peer-driven exposure means a teenager can develop strong opinions and a working vocabulary about crypto entirely through channels a parent has little visibility into, reinforcing why an open conversation at home functions less as an introduction to a brand-new topic and more as a chance to check, correct, and build on a foundation that has often already been laid.
This pattern is not unique to any single country, though the specific platforms and figures involved vary by region. Financial regulators and consumer protection agencies in multiple countries have raised similar concerns about social-media-driven crypto promotion reaching young audiences, reflecting a broader, cross-border pattern rather than an issue confined to any one market. What stays consistent across these different regional pictures is the underlying mechanism: a young person’s financial information increasingly arrives through entertainment and social channels optimized to maximize attention and engagement rather than accuracy or balance, meaning the most emotionally compelling content, a dramatic gain, a confident prediction, a countdown-style sense of urgency, tends to spread furthest regardless of how sound the underlying reasoning actually is. Recognizing this dynamic does not require a teenager to abandon social media or gaming communities as sources of information entirely, which would be both impractical and unnecessary, but it does make a strong case for treating any single crypto claim encountered this way as a starting point for further questions rather than as a finished, trustworthy conclusion in its own right.
Taken together, this research paints a picture that should reassure rather than alarm most parents about their own relevance to the conversation, even while making clear how much competition they face. Parents and family are not absent from the list of information sources young investors consult; they simply rank below social media and internet searches rather than ahead of them, which suggests that a parent who engages early and stays engaged has a real chance of becoming a trusted voice in the mix rather than being crowded out entirely. What the data does not offer is any reason for complacency, since a teenager who has already absorbed the emotional logic of FOMO-driven investing from a social feed, well before any adult in their life raises the subject, is arriving at that first family conversation with assumptions already formed, making the timing and framing of that conversation considerably more important than it might otherwise be.
The Real Risks: Scams, Hype, and Hard Lessons
Understanding why crypto appeals to teenagers only tells half the story; the other half involves being honest about what has actually gone wrong when young people, whether as victims or as unwitting participants, have gotten tangled up in the crypto world without adult guidance or adequate skepticism. The risks here are not hypothetical or exaggerated for effect. They show up in court filings, in investigative journalism, and in the enforcement data compiled by federal agencies that track fraud, and they involve real names, real dollar amounts, and real consequences that followed people well past their teenage years.
It is worth separating these risks into two related but distinct categories before going further. The first involves teenagers or young people as direct targets of scams built specifically to exploit their inexperience, their trust in online communities, and their fear of missing out on a fast-moving opportunity. The second, less commonly discussed but arguably more sobering, involves teenagers themselves becoming participants in schemes that cause serious financial harm to other people, sometimes without fully grasping the scale of the consequences until much later. Both categories deserve a place in any honest conversation a family has about crypto, because both illustrate, in very different ways, how quickly a technology built around anonymity, speed, and irreversible transactions can turn a young person’s curiosity into a genuinely serious problem.
What makes these particular stories useful for a family conversation, rather than simply frightening, is their specificity. A generic warning that “crypto scams exist” is easy for a teenager to file away as background noise, similar to being told that strangers on the internet cannot always be trusted, a fact so often repeated it has lost most of its emotional weight. A documented account of exactly how a specific scheme worked, who was involved, how old they were, and what ultimately happened to them carries a different kind of weight entirely, because it replaces an abstraction with a sequence of concrete, ordinary-seeming decisions that a listener can imagine making themselves.
When a Teenager Became the Attacker: The Ellis Pinsky Case
One of the most extensively documented cases connecting a teenager directly to large-scale cryptocurrency theft involves Ellis Pinsky, who was fifteen years old and a tenth-grade student at Irvington High School in suburban New York in 2018 when he participated in an elaborate scheme known as SIM swapping, a technique in which an attacker tricks or bribes a mobile carrier’s employees into transferring a victim’s phone number onto a device the attacker controls. Once Pinsky and his associates gained control of entrepreneur and crypto investor Michael Terpin’s phone number, they were able to intercept the text-message-based security codes protecting his accounts and ultimately drain cryptocurrency holdings that Terpin valued at approximately 24 million dollars.
The case did not end with the theft itself, and its long aftermath is precisely what makes it so instructive. Terpin pursued a civil lawsuit against Pinsky years after the theft, and according to a court filing made public in the Southern District of New York in October 2022, Pinsky agreed to a settlement requiring him to pay back 22 million dollars, an amount reflecting nearly the entirety of what had been stolen years earlier when he was still a minor. As part of the broader case, reporting also indicated Pinsky had separately repaid an initial 2 million dollars to Terpin at an earlier point. A detailed Bloomberg investigative feature published in August 2023, drawing on extensive interviews and court records, traced how a loosely connected group of teenage gamers, using online forums and gaming-community connections rather than any specialized hacking infrastructure, assembled the knowledge and access needed to pull off a theft of this scale, illustrating that the barrier to committing serious cryptocurrency crime was, and arguably remains, far lower than most parents would assume.
The Pinsky case is also notable for what it reveals about how such schemes recruit participants in the first place. According to the Bloomberg reporting, the network Pinsky operated within relied on other teenagers, some recruited through shared interest in a popular online game, who divided tasks such as gathering personal information on targets, executing the actual carrier-employee deception, and converting stolen assets into usable funds, a division of labor that let any individual participant convince themselves they were only playing a small, disconnected role in something larger. That psychological distancing, the sense that a narrow, technical task carries no real moral weight because someone else handles the rest of the scheme, is a dynamic worth naming directly in a family conversation, since it is precisely the kind of rationalization that can let a curious, technically capable teenager drift from an interesting puzzle into something that carries genuine legal and financial consequences years down the road.
The lesson here is not that every teenager who plays online games or spends time in crypto-adjacent internet communities is at risk of becoming a criminal; the overwhelming majority obviously are not. The lesson is narrower and, in some ways, more useful for a family conversation: cryptocurrency’s combination of irreversible transactions, minimal identity verification in many corners of the ecosystem, and communities that reward technical cleverness regardless of its legality can pull a teenager considerably further down a dangerous path than they may have initially intended, and the financial and legal consequences that eventually catch up, in Pinsky’s case, a settlement equal to nearly the full amount stolen, arriving years after the fact, do not disappear simply because the person responsible was a minor when the underlying conduct occurred.
Common Scam Tactics Aimed at Young People Today
While the Pinsky case represents an extreme and unusual outcome, the far more common risk facing teenagers is being targeted as a victim rather than becoming a perpetrator, and the tactics used against young, online, financially inexperienced people have grown increasingly sophisticated. Fraudulent giveaway schemes remain a persistent staple of this landscape, typically built around a fake social media account impersonating a celebrity, a well-known crypto figure, or occasionally a platform itself, promising to double or multiply any cryptocurrency sent to a particular wallet address as part of a supposed promotional event. The scheme relies entirely on urgency and social proof, often padded with fake comments and testimonials, to short-circuit the healthy skepticism a more experienced investor might otherwise apply, and it disproportionately succeeds against newcomers who have not yet learned that no legitimate promotion works this way.
A second major category involves influencer-driven promotion of tokens or platforms that the influencer has been paid to endorse, frequently without clear disclosure that the endorsement is a paid advertisement rather than a genuine personal recommendation. Younger audiences, who often follow creators with a level of parasocial trust closer to friendship than to traditional celebrity endorsement, are especially vulnerable to this dynamic, since the recommendation arrives through a voice they already trust for gaming tips, entertainment, or lifestyle content, with no obvious signal that a financial incentive sits behind the message. Regulatory bodies in multiple countries have taken enforcement action against undisclosed crypto promotions in recent years specifically because this blurred line between entertainment and advertising has proven so effective at reaching younger, less experienced audiences who are unaccustomed to scrutinizing a recommendation the way they might scrutinize a traditional advertisement.
A third pattern, increasingly documented in federal fraud statistics, involves romance and relationship-based scams that begin on a dating app or, notably for younger targets, a social media platform or gaming service, and gradually pivot toward a request to invest in cryptocurrency together. According to the Federal Bureau of Investigation’s Internet Crime Complaint Center, cryptocurrency-related fraud losses reported to the agency exceeded 5.6 billion dollars in 2023, a 45 percent increase over the prior year, and climbed further still in 2024, when complaints involving cryptocurrency investment fraud alone totaled 5.8 billion dollars in reported losses. While the largest dollar losses in this data are concentrated among older adults, who tend to have more savings available to lose, the underlying tactics, manufactured urgency, a trusted-seeming relationship, and a request to move funds into an unfamiliar wallet, are increasingly aimed at younger targets as well, particularly through gaming-adjacent platforms and social media direct messages where a teenager might reasonably assume they are simply talking to another fan of the same game or show.
A closely related tactic involves scammers directing targets, including teenagers active in gaming marketplaces, toward converting cryptocurrency into gift cards or in-game currency as a supposed verification step or fee before a payout can be released, a pattern that mirrors older gift-card scam schemes but adds a layer of unfamiliarity that makes it harder for a young target to recognize the red flag. Because these transactions typically move through platforms a teenager already trusts for legitimate purchases, the surrounding context feels safe even when the specific request, sending value first with a promised return to follow, is a hallmark of fraud regardless of which currency or platform carries it. Financial counselors who work with young fraud victims frequently note that the presence of a familiar, everyday platform, rather than an obviously suspicious one, is often what allows an otherwise cautious teenager to lower their guard long enough to complete a transaction they would likely question in a less familiar setting.
A fourth, increasingly common tactic involves fraudulent mobile apps or browser extensions designed to closely mimic legitimate cryptocurrency exchanges or wallet providers, often distributed through search engine advertisements or unofficial app stores rather than a platform’s official channels. A teenager searching for a well-known exchange by name can, without realizing it, land on a convincing imitation designed purely to capture login credentials or wallet keys the moment they are entered, with no functioning trading service behind the interface at all. Because these fake apps frequently replicate a legitimate platform’s branding, layout, and even customer support messaging in close detail, verifying that a download link or website address matches the exchange’s official, verified source before entering any credentials has become one of the more important habits a young crypto user can develop, alongside the broader rule against ever sharing a private key or seed phrase with anyone.
Recognizing these patterns matters more than memorizing any single scam, because the tactics themselves evolve constantly while the underlying psychological levers, urgency, trust borrowed from a familiar face, and a fear of missing a rare opportunity, remain remarkably consistent across nearly every variation. A teenager who understands why these tactics work, rather than simply which specific scams have been reported so far, is considerably better equipped to recognize the next one, whatever new form it happens to take by the time it reaches their own feed.
Starting the Conversation: A Framework for Parents
Armed with an honest picture of both the appeal and the risks, the practical question most parents actually want answered is simpler: how does a conversation like this actually begin. The first and most important principle is timing it around genuine curiosity rather than around a crisis. Waiting until a teenager has already lost money, joined a group chat pushing a questionable token, or asked to borrow funds for an “opportunity” means the conversation starts from a defensive posture on both sides, with the parent alarmed and the teenager already invested, emotionally and possibly financially, in defending a decision they have already made. A far more productive entry point is a neutral moment, prompted by a news story, a video the teenager mentions, or simply a parent asking what they have been seeing online lately about crypto, before any money or ego is on the line.
Tone matters as much as timing. A teenager who senses that a parent has already decided crypto is foolish, or worse, that they themselves are foolish for being interested in it, will typically respond by disengaging or by quietly continuing to explore the subject without any further input from that parent, since the conversation has been made to feel like a dead end rather than an open exchange. A more effective posture treats the teenager’s interest as legitimate and worth taking seriously, even while being clear-eyed about the risks, an approach closer to a coach evaluating a genuinely interesting strategy than a referee simply blowing a whistle. Asking a teenager to explain what they find interesting about a particular project or why they think a certain token has value, and then listening carefully to the answer, accomplishes two things at once: it signals genuine respect for their perspective, and it usually reveals fairly quickly how much or how little research actually sits behind their enthusiasm.
The framework that tends to work best unfolds in stages rather than as a single exhaustive lecture. An initial conversation might focus entirely on understanding what a teenager already believes and where those beliefs came from, without introducing much new information at all, since correcting misconceptions is far more effective once a parent actually knows what those misconceptions are rather than guessing. A second conversation can introduce foundational concepts, ideally framed as things the parent is curious to understand together with their teenager rather than facts being handed down from an authority, which tends to invite more open, two-way engagement than a format that feels like a quiz. Subsequent conversations can revisit real examples, including the documented cases discussed earlier in this guide, and can gradually shift toward practical questions about whether, when, and how a teenager might actually be allowed to engage with cryptocurrency in a supervised way, a topic covered in more detail later in this guide.
It is also worth preparing, in advance, for the possibility that a teenager reveals during this conversation that they have already invested money, joined a questionable community, or even lost a modest sum without previously mentioning it. Reacting with anger or panic in that moment tends to guarantee that any future financial mistake gets hidden rather than disclosed, while a calmer response, focused on understanding what happened and what can still be done, preserves the very openness a parent is trying to build. Treating a modest, already-absorbed loss as a genuinely valuable, low-cost lesson, rather than as evidence of poor judgment requiring punishment, tends to produce a teenager who is more willing to ask for help the next time something feels off, which is precisely the outcome every part of this framework is ultimately designed to encourage. This same calm, curious posture applies equally well to a teenager who has not lost money but is eager to get started, since dismissing that enthusiasm outright tends to push the activity underground rather than eliminating it, while channeling it toward a supervised, educational approach, discussed later in this guide, keeps a parent meaningfully involved in decisions that would otherwise happen entirely out of view.
Throughout this staged approach, a few ground rules tend to keep the conversation productive rather than adversarial. Avoiding absolute statements, such as insisting cryptocurrency is nothing but a scam, preserves credibility, since a single well-known counterexample, a legitimate use case or a friend who genuinely profited, can undo an oversimplified claim instantly and make every subsequent warning less believable by association. Focusing on decision-making processes rather than outcomes also helps, since a teenager who buys a token that happens to rise in price after an impulsive, poorly reasoned decision has not actually made a good decision, even though the outcome looks good, and a parent who can separate the quality of a decision from its result is better positioned to reinforce sound thinking regardless of how any particular investment performs. Finally, treating the conversation as ongoing rather than a single milestone to check off matters enormously in a space that changes as quickly as cryptocurrency does, since whatever specific platforms, tokens, or scams are relevant at the moment this guide is read will likely have shifted considerably by the time a teenager is old enough to make independent financial decisions.
Teaching the Fundamentals Without the Jargon
Once a parent has established an open, low-pressure channel for discussing crypto, the next practical task is building enough shared vocabulary to have a genuinely substantive conversation rather than one built entirely around vague impressions. This does not require a parent to master the technical details of distributed systems or cryptography; it requires a working grasp of a handful of core ideas, explained clearly enough that a teenager can connect them to what they are already seeing online, along with enough comfort with the material to ask good follow-up questions rather than simply reciting definitions.
The starting point for nearly any productive explanation is helping a teenager understand what actually makes cryptocurrency different from the money and financial accounts they already interact with every day. A checking account balance exists because a bank maintains a private ledger and vouches for its accuracy; a cryptocurrency balance exists because a decentralized network of computers maintains a shared, public ledger that many participants verify simultaneously, an approach designed specifically so that no single company or government controls or can unilaterally alter the record. Framing the explanation this way, as a difference in who keeps the books rather than as an entirely alien financial concept, tends to make the underlying idea feel far less mysterious and far more like a variation on a system the teenager already understands.
From that foundation, the conversation naturally extends into the practical mechanics teenagers need in order to evaluate what they encounter online with real judgment rather than guesswork, which is where the more specific building blocks, the technology’s basic architecture, the tools used to store and access it, and the price behavior that makes it so visible online in the first place, become worth walking through in more detail.
Blockchain, Wallets, and Volatility Explained Simply
A blockchain, at its core, is best explained to a teenager as a shared notebook that thousands of computers around the world keep an identical copy of, with every new transaction added as a new entry that everyone with a copy of the notebook can see and verify, making it extremely difficult for any single person to secretly alter an entry after the fact without every other copy immediately showing a mismatch. This framing avoids getting lost in cryptographic detail while still capturing the essential property that makes the technology useful: no single company, bank, or government controls the notebook, which is precisely why cryptocurrency transactions cannot be reversed by calling customer service the way a fraudulent credit card charge often can be, a point worth emphasizing directly, since the absence of a safety net is exactly what many scams depend on.
A crypto wallet is the second concept worth explaining clearly, since confusion here is often what leads directly to theft. A wallet does not store cryptocurrency the way a physical wallet stores cash; it stores the cryptographic keys that prove ownership of assets recorded on the blockchain, meaning that whoever controls those keys controls the assets, in a very literal, immediate sense with no separate identity check required. This is the direct technical thread connecting back to the earlier discussion of SIM swapping and phishing, since an attacker does not need to breach some heavily fortified vault to steal cryptocurrency; they simply need to obtain the keys or the credentials protecting them, whether through a fake login page, a compromised phone number, or a teenager persuaded to voluntarily share information they did not realize was sensitive.
Volatility, the third essential concept, refers to how dramatically and rapidly a cryptocurrency’s price can move compared to more traditional assets like established company stocks or government bonds, and it is worth explaining not just as a fact but as a specific psychological trap. A teenager who buys a token and watches it double within days is not just experiencing a financial gain; they are experiencing a genuinely powerful emotional reward that can reshape how they think about risk going forward, making a subsequent, much larger loss feel like an acceptable price for chasing that same feeling again. Explaining volatility through this emotional lens, rather than purely as a statistical property, helps a teenager understand why so many experienced investors describe crypto trading as feeling closer to gambling than to conventional investing during its sharpest price swings, a comparison that tends to resonate more than any purely technical description of price variance ever could.
One additional detail worth walking through directly is the distinction between a wallet’s public address, which functions similarly to a bank account number and can be shared freely with anyone sending funds, and its private key or recovery seed phrase, which functions more like the combination to a safe and must never be shared with anyone under any circumstances, including someone claiming to offer customer support. A significant share of the phishing and social-engineering attempts documented in fraud reports rely entirely on convincing a target to voluntarily reveal this private information, often by impersonating a wallet provider or exchange and manufacturing a false sense of urgency around a supposed account problem. A teenager who understands clearly that no legitimate company will ever ask for a private key or seed phrase over a message, email, or phone call has absorbed one of the single most protective pieces of knowledge available in this entire subject, since it closes off the specific mechanism behind a large share of the theft cases discussed earlier in this guide.
Together, these three concepts, the shared and unchangeable ledger, the keys that grant total and irreversible control, and the emotional pull of extreme price swings, give a teenager the minimum vocabulary needed to ask sharper questions about anything crypto-related they encounter online, whether that means questioning why a supposed giveaway would ever ask for payment first, understanding why losing access to a wallet’s keys means losing the assets permanently with no customer service line to call, or recognizing the specific emotional high that keeps pulling them back to check a price they have already checked ten times that day.
Choosing Tools and Setting Guardrails
With a shared vocabulary in place, many families eventually reach the practical question of whether, and how, a teenager might be allowed some form of supervised exposure to investing, crypto included, rather than being kept entirely on the sidelines until adulthood. This is a reasonable question, and the honest answer is that the options available to families vary considerably in how directly they allow a minor to engage with cryptocurrency itself, since most regulated financial products built for young people have made deliberate, carefully considered choices about where to draw that line.
Custodial investment accounts, structured under long-standing legal frameworks that allow a parent or guardian to manage assets on a minor’s behalf until they reach adulthood, represent the most common entry point families use for any kind of youth investing, crypto-related or otherwise. These accounts generally allow a parent to approve or restrict specific trades, review activity regularly, and use the account itself as an ongoing teaching tool rather than a one-time setup task, which aligns well with the staged, conversational approach to crypto education described earlier in this guide. What families quickly discover, however, is that many of the platforms built specifically for younger investors have chosen not to offer direct cryptocurrency trading at all, even while acknowledging and responding to the very real interest young people have in the space, a design choice worth examining closely because of what it reveals about how a well-resourced, regulated company weighs the same risks this guide has covered.
Families ultimately land in different places along this spectrum depending on their own comfort level, their teenager’s demonstrated maturity, and how much hands-on financial experience they want to offer before adulthood removes the option for close supervision entirely. Some parents choose to allow no direct crypto exposure whatsoever until their teenager is legally an adult and managing their own accounts, relying instead on conversation and case studies like the ones covered earlier in this guide to build understanding without any real money involved. Others prefer a supervised, hands-on approach specifically because they believe a teenager who has never felt the real emotional pull of a fluctuating balance will be less prepared to manage that feeling responsibly once they gain full independent control of their own finances. Neither approach is objectively correct, and the right choice depends heavily on factors specific to each family and each teenager, but understanding the actual tools available, and how thoughtfully designed platforms have approached the same tradeoffs, gives any family a more informed starting point than guessing.
How One Regulated Family App Handles Crypto: The Greenlight Example
Greenlight, a family finance and debit card platform used by more than 6.5 million parents and children according to the company’s own December 2024 year-in-review report, offers a useful real-world illustration of this tension between demand and caution. The platform’s investing feature, offered through an SEC-registered investment advisor and built around custodial accounts that require parental approval on every trade, deliberately limits young investors to stocks and exchange-traded funds rather than allowing direct purchases of cryptocurrency itself, a design decision the company has described publicly as letting kids learn core investing principles without what it calls the high-risk guesswork of buying crypto directly.
That restriction has not stopped crypto-related curiosity from showing up clearly in the platform’s own data. According to Greenlight’s December 2024 year-in-review report, total investing activity on the platform more than doubled, rising from 20 million dollars in 2023 to 43 million dollars in 2024, with the report specifically citing strong interest in emerging technology, artificial intelligence, and cryptocurrency as contributing trends. Notably, that crypto-adjacent interest showed up entirely through instruments the platform does support rather than through direct coin purchases: the report highlighted rising activity in the iShares Bitcoin Trust, an exchange-traded fund that gained regulatory approval from the Securities and Exchange Commission in January 2024, along with growing interest in MicroStrategy, a business analytics company whose stock price has become closely tied to its large corporate holdings of bitcoin.
The custodial structure underlying Greenlight’s investing product also illustrates a broader legal framework many families rely on regardless of which specific platform they choose. Assets held in this type of account remain legally owned by the minor from the outset, even though a parent retains control over trading decisions until the account holder reaches the age of legal adulthood in their state, at which point full control transfers automatically. This structure means the supervised period is not merely a technical restriction imposed by the platform but a deliberate, legally recognized bridge between a teenager having no financial autonomy at all and having complete control over a portfolio they may have already spent years learning to manage, a bridge that a platform’s decision to exclude direct crypto trading effectively extends a little further into early adulthood than it might otherwise, buying additional time for judgment and experience to develop before the highest-risk instruments become available without any oversight at all.
This pattern offers a genuinely instructive model for families weighing their own approach. Rather than treating crypto interest as something to be either fully indulged or entirely blocked, a platform built and regulated specifically around the needs of young investors chose a middle path, allowing exposure to crypto-adjacent price movements through instruments that carry the standard investor protections of regulated public markets, while withholding direct access to unregulated coin purchases and the wallet-security risks that come with them. A parent building their own household approach can draw a similar lesson without needing to use any particular platform: supervised, indirect exposure through well-understood, regulated instruments can satisfy a teenager’s genuine curiosity about crypto’s price movements far more safely than handing them a wallet address and an exchange account with no oversight at all, preserving the educational value of watching an investment move in real time without the specific risks, irreversible transactions, unregulated platforms, and wallet-security failures, that this guide has spent considerable time documenting.
Final Thoughts
Teaching a teenager about cryptocurrency is, at its core, an extension of teaching them about money and risk more broadly, and the families that handle it best tend to be the ones who resist treating it as an entirely separate, exotic subject requiring its own specialized rulebook. The same instincts that help a teenager avoid a predatory payday loan, recognize a pyramid scheme disguised as a business opportunity, or understand why a credit card’s minimum payment is a trap rather than a convenience apply directly to recognizing a fraudulent crypto giveaway or an undisclosed influencer promotion. A parent who has already built general financial literacy with their teenager has a considerable head start, and one who has not yet done so will find that crypto conversations are actually a reasonably engaging entry point into that broader project, since few subjects capture a teenager’s attention quite as reliably as the promise of turning a small amount of money into a large one quickly.
What this guide has tried to demonstrate throughout is that the most effective response to crypto’s presence in a teenager’s life is neither prohibition nor uncritical encouragement, but sustained, honest engagement grounded in real information rather than either fear or hype. The documented cases examined here, a teenager’s direct involvement in a multimillion-dollar theft that followed him into adulthood with lasting financial and legal consequences, verified survey data showing just how deeply crypto ownership and FOMO-driven decision-making have already taken root among the youngest adult investors, and a major family finance platform’s own considered choice to allow indirect exposure while withholding direct access, all point toward the same underlying conclusion: this is a subject with genuine stakes, genuine complexity, and genuine teachable moments, not simply a fad to be dismissed or a shortcut to be chased.
The broader financial-inclusion promise sometimes attached to cryptocurrency, that it might offer people without access to traditional banking a new path to financial participation, is worth acknowledging honestly even within a guide focused mainly on risk, since it helps explain why the technology has attracted so much serious attention beyond pure speculation and why dismissing it outright would leave a teenager poorly equipped to evaluate the subject with any nuance. At the same time, that broader promise does not erase the very immediate, well-documented harms facing young people who engage with this technology without preparation, and a responsible family conversation needs room for both realities simultaneously, respecting the technology’s genuine ambitions while refusing to look away from its very real costs.
As cryptocurrency continues to evolve, and as the specific platforms, scams, and cultural touchpoints discussed in this guide inevitably shift and change, the core skill parents are actually building in their teenagers, the ability to question a claim, trace where information is coming from, separate a sound decision from a lucky outcome, and recognize the emotional levers that hype relies on, will remain relevant regardless of what the next viral token or trending platform happens to be. That durability is the real reward of doing this work now, well before a teenager is managing their own full paycheck or facing a genuinely large financial decision on their own, and it is a far more valuable inheritance than any single piece of advice about a particular coin, platform, or trend could ever be.
FAQs
- At what age should parents start talking to their kids about cryptocurrency?
There is no fixed age, but many financial educators suggest starting as soon as a child begins encountering crypto references online, often around the same time they start using social media or gaming platforms independently, which for many families now happens well before high school. - Is it illegal for a teenager to own cryptocurrency?
Most cryptocurrency exchanges require account holders to be at least eighteen due to identity-verification and contract-law requirements, so teenagers generally cannot open their own exchange accounts directly, though some families use custodial arrangements where a parent legally holds assets on a minor’s behalf. - What exactly is a SIM-swap scam, and why should families know about it?
A SIM-swap scam occurs when an attacker convinces or bribes a mobile carrier into transferring a victim’s phone number to a device the attacker controls, allowing them to intercept security codes and access financial accounts. It was the technique used in the widely documented 2018 theft of roughly 24 million dollars from investor Michael Terpin. - Why do so many teenagers own cryptocurrency compared to other generations?
Research from the FINRA Investor Education Foundation and CFA Institute found that 55 percent of young American investors aged eighteen to twenty-five already owned cryptocurrency as of their November-December 2022 survey, with many citing social media, rather than parents or schools, as their primary source of investing information. - What does FOMO have to do with crypto investing among young people?
Fear of missing out, or FOMO, was cited by 41 percent of Gen Z investors surveyed in the United States and Canada as a factor in why they started investing at all, reflecting how social pressure and visible peer gains, rather than research, often drive a first investment decision. - Do any regulated apps let kids buy cryptocurrency directly?
Major regulated youth investing platforms, including Greenlight, generally do not allow direct cryptocurrency purchases, instead limiting young investors to stocks and exchange-traded funds, some of which, like bitcoin-linked funds, offer indirect exposure to crypto price movements under standard market regulation. - What is a crypto wallet, and why does losing access to one matter so much?
A crypto wallet stores the cryptographic keys proving ownership of blockchain-based assets rather than the assets themselves, and because blockchain transactions cannot be reversed, losing those keys or having them stolen generally means permanently losing access to the associated funds with no customer service recourse. - How can a teenager tell a legitimate crypto opportunity from a scam?
Warning signs include promises of guaranteed or doubled returns, pressure to act immediately, requests to send funds first as a condition of a giveaway, and recommendations from influencers without any disclosure of a paid partnership, all of which are patterns documented extensively in federal fraud data. - How much money have cryptocurrency scams actually cost people recently?
According to the FBI’s Internet Crime Complaint Center, reported cryptocurrency fraud losses exceeded 5.6 billion dollars in 2023, and cryptocurrency investment fraud complaints alone accounted for 5.8 billion dollars in reported losses in 2024, figures that continue trending upward year over year. - What is the single most useful thing a parent can do if their teenager is already interested in crypto?
Engaging directly and consistently tends to matter more than any single piece of advice, since research shows parents already rank as a meaningful information source for young investors, and staying part of an ongoing conversation gives a parent real influence that disappears entirely if the topic is avoided altogether.