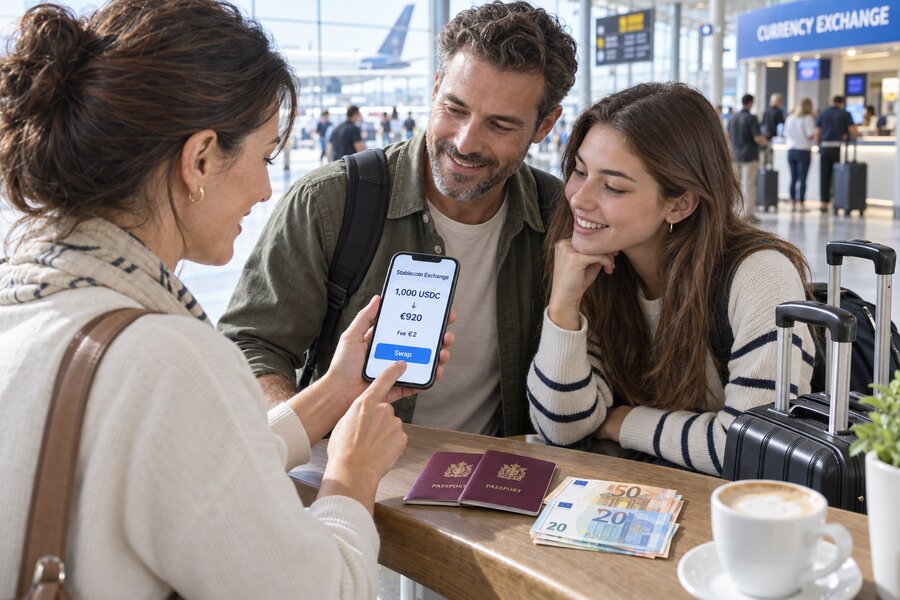
Every year, millions of travelers arrive at a foreign airport, tired from a long flight, and walk directly past a currency exchange kiosk glowing with a rate that looks almost reasonable until it is compared with what the money was actually worth an hour earlier. That gap between the rate a traveler is offered and the rate banks and financial institutions actually trade at, known as the mid-market or interbank rate, has existed for as long as people have needed to convert one currency into another while away from home, and it has proven remarkably resistant to the kind of competitive pressure that tends to erode inefficient pricing in most other consumer markets. Airport kiosks can charge what they charge in part because a traveler standing in an arrivals hall, holding a suitcase and needing local cash to get to a hotel, is not in a strong bargaining position and rarely has the time, energy, or information to shop around for a better rate before making a decision.
This has never been simply a story about kiosks. A traveler who avoids the airport exchange counter entirely and instead pays with a card at a restaurant or hotel abroad still runs into a second, subtler version of the same problem: a foreign transaction fee tacked onto the receipt by the card issuer, a dynamic currency conversion prompt at the payment terminal offering to charge the purchase in the traveler’s home currency at a rate quietly worse than what the card network would have applied automatically, or an ATM withdrawal fee stacked on top of a conversion markup that is rarely disclosed clearly at the moment of the transaction. None of these costs are new, and none of them are hidden in the sense of being illegal or undisclosed in the fine print, but together they add up to a persistent tax on the simple act of spending money in a country that does not use a traveler’s home currency, one that a household on a two-week trip abroad can easily pay several times over without ever noticing a single obviously outsized charge.
What has changed more recently is the emergence of a genuinely different mechanism for moving value across currencies and borders: stablecoins, a category of cryptocurrency specifically designed to hold a stable value pegged to an existing currency, most commonly the U.S. dollar, rather than fluctuating in the way that bitcoin or other more speculative digital assets do. Because a stablecoin like USDC is designed to always be worth approximately one U.S. dollar, it can function as a kind of digital bridge currency, letting a person convert dollars into stablecoins, move those stablecoins nearly instantly across borders on a blockchain network, and then convert them into local currency somewhere else, often at a lower total cost than a traditional wire transfer, card network, or currency exchange counter would charge for the same underlying trip from one currency to another. This is not a hypothetical idea confined to cryptocurrency forums. Major payment networks, remittance companies, and card issuers have spent the past several years quietly building real infrastructure around this idea, some of it now handling billions of dollars a year in actual settlement volume.
This article looks specifically at what that infrastructure means for an ordinary traveling household rather than for institutional finance. It walks through why the traditional cost of converting money abroad has stayed so persistently high, how on-chain currency exchange actually works in practical terms for someone who is not a cryptocurrency specialist, and how real products, including a stablecoin-funded travel card and a major card network’s own stablecoin settlement rails, have begun putting this idea into practice at meaningful scale. It also works through a grounded, numbers-based comparison of what a family might actually spend converting a fixed travel budget through an airport kiosk, a conventional foreign-transaction-fee card, and a stablecoin-based approach, since the gap between these options only becomes meaningful once it is expressed in dollars a household would recognize from its own trip planning. Finally, it addresses the real limits of this approach honestly, since on-chain currency exchange solves some of the oldest problems in international travel spending without solving all of them, and a traveler weighing whether to use it deserves a clear picture of both sides before deciding what works for their own trip.
The Real Price of Foreign Cash: Kiosks, DCC, and Card Fees
The single most visible cost travelers encounter is the airport currency exchange kiosk, and the reason it remains so expensive has less to do with any single hidden fee than with the layered structure of the markup itself. A kiosk quotes a rate that already includes a spread above the mid-market rate, commonly somewhere in a range of roughly five to fifteen percent depending on the currency pair, the specific location, and how much competition exists nearby, and that spread is frequently widened further by a flat service charge or commission applied on top of the already-marked-up rate. Airport locations in particular tend to sit at the higher end of that range, since a traveler who has just landed and needs cash immediately for transportation or a first meal has little practical ability to walk to a competing exchange counter down the street, a captive-audience dynamic that airport retail spaces of all kinds, not just currency kiosks, are well known for exploiting. The same underlying dynamic shows up in a milder form at hotel front desks and other tourist-adjacent exchange points, where convenience is being sold alongside currency, and the price reflects that combination rather than a straightforward cost of doing the conversion itself.
Dynamic currency conversion, usually abbreviated DCC, represents a second and often less understood version of the same basic problem, one that shows up not at a currency counter but directly at a card payment terminal or ATM. When a traveler pays with a card abroad, a merchant’s payment system will sometimes ask whether the traveler would like the charge processed in their home currency rather than the local one, framing this as a convenience that lets the traveler see the price in dollars, euros, or whatever currency their card is denominated in, at the moment of purchase. What that prompt does not make clear is that accepting it hands control of the exchange rate to the merchant’s payment processor rather than to the card network, and that processor typically applies a rate meaningfully worse than the one the card network would have used automatically had the traveler simply declined and let the transaction settle in local currency. A 2023 study by researchers Dirk Gerritsen, Bora Lancee, and Coen Rigtering, published in the Journal of Public Policy and Marketing, examined exactly this dynamic and found that dynamic currency conversion disproportionately harmed less financially literate consumers, who were more likely to accept the home-currency option without recognizing the worse effective rate embedded in it, and the researchers went on to test and validate a specific intervention, changing how the choice was presented at the point of sale, that measurably reduced the rate at which consumers fell into the more expensive option. The finding underscores a point that runs through nearly every cost discussed in this article: the expense of converting money abroad is rarely a single dramatic fee that a traveler can spot and avoid, but rather a design choice embedded in the payment flow itself, one that benefits from a traveler’s unfamiliarity and time pressure in an unfamiliar country.
Card issuers add a third, more straightforward layer on top of both of these dynamics in the form of foreign transaction fees, typically somewhere around one to three percent of each purchase made abroad, charged regardless of whether DCC was involved, simply for the fact that the transaction crossed a currency boundary. Many issuers waive this fee on cards specifically marketed toward travelers, but a large share of everyday debit and credit cards still carry it, and it applies quietly to every single purchase across a trip rather than as one visible transaction the way an airport kiosk exchange does, making it easy for a household to underestimate its cumulative size across a week or two of ordinary spending. ATM withdrawals abroad frequently combine several of these costs at once: a flat withdrawal fee charged by the local bank operating the machine, a separate fee charged by the traveler’s own bank for the foreign withdrawal, and a conversion markup embedded in the exchange rate applied to the transaction, sometimes worsened further if the ATM itself offers a DCC-style prompt asking whether the withdrawal should be processed in the traveler’s home currency. Taken together, kiosk markups, DCC, foreign transaction fees, and stacked ATM charges do not represent four separate minor inconveniences so much as four overlapping mechanisms funneling money away from the same underlying trip budget, which is precisely the set of costs that stablecoin-based currency conversion has emerged to compete against.
How On-Chain Currency Exchange Actually Works
Understanding why stablecoin conversion can undercut these traditional costs requires understanding, in fairly plain terms, what actually happens when money moves through this system rather than through a bank or a currency counter. At its core, the process involves converting ordinary currency into a stablecoin, a type of digital token whose value is designed to track a real-world currency closely and predictably, moving that stablecoin across a blockchain network to wherever it is needed, and then converting it back into ordinary currency at the destination. The appeal of this structure is that the actual movement of value across borders happens on a shared, always-on digital network rather than through the slower, more intermediary-heavy correspondent banking relationships that traditional international transfers rely on, and because the value being moved is pegged to a stable currency rather than fluctuating like a typical cryptocurrency, the person sending it does not need to worry about the value changing meaningfully between the moment they convert into it and the moment they convert back out.
The two subsections that follow break this process down further, first explaining what a stablecoin actually is and why its price stability matters so much for this specific use case, and then walking through the practical steps and remaining friction points a traveler encounters converting cash into stablecoins and back again. Neither step is entirely frictionless yet, and understanding where the remaining costs and delays sit is just as important as understanding the basic mechanism, since the honest case for on-chain currency exchange rests on it being meaningfully cheaper and faster than the alternatives, not on it being perfectly free or instantaneous.
Stablecoins as a Dollar-Pegged Bridge Currency
A stablecoin is a type of cryptocurrency engineered specifically to avoid the price volatility that most digital assets are known for, typically by maintaining reserves, often in cash and short-term government securities, equal to the value of every token in circulation, so that one unit of the stablecoin can reliably be redeemed for one unit of the currency it tracks. USDC, issued by the financial technology company Circle, is among the most widely used examples and is designed to always be worth approximately one U.S. dollar, with the company publishing regular attestations of the reserves backing the tokens in circulation. Because a stablecoin’s entire design purpose is to not fluctuate the way bitcoin or other cryptocurrencies do, it functions less like a speculative asset a traveler might buy hoping its value will rise, and more like a digital representation of a dollar that happens to live on a blockchain network rather than in a traditional bank account, which is precisely the property that makes it useful as a bridge currency for cross-border payments rather than as an investment.
This distinction matters enormously for a traveler evaluating whether this approach makes sense for their own trip. A household converting money into bitcoin before a trip would be taking on real exposure to that asset’s price swinging significantly, potentially losing meaningful value in the days between converting into it and converting back out, an outcome that would defeat the entire purpose of trying to save money on currency conversion. A household converting into a well-established, dollar-pegged stablecoin is not taking on that same kind of exposure, at least not in the ordinary case, since the token’s whole design is to hold its value steady against the currency it tracks. This is also why stablecoins, rather than more volatile cryptocurrencies, are the specific technology underlying nearly every serious real-world product built around on-chain currency exchange for payments and remittances, including each of the case studies examined later in this article, since no payment network or card issuer building a product for ordinary consumers could responsibly build it around an asset whose value might swing ten percent in either direction between breakfast and dinner.
It is worth noting that stablecoins are not entirely without risk, a point this article returns to in more detail later, since a stablecoin’s stability depends on the reserves and management practices of the company issuing it, and the broader stablecoin market has, in isolated cases involving smaller or less rigorously managed tokens, seen instances of a coin failing to hold its peg. The stablecoins used in the mainstream payment products discussed in this article are, at the time of writing, among the largest, most established, and most heavily scrutinized tokens in the category, which meaningfully reduces but does not entirely eliminate this category of risk, a distinction worth keeping in mind rather than treating all stablecoins as interchangeable in terms of reliability.
On-Ramps, Off-Ramps, and Where Friction Still Lives
The practical process of using stablecoins to move money across a currency boundary involves what the industry generally calls on-ramps and off-ramps: the point where ordinary currency enters the blockchain-based system as a stablecoin, and the point where it exits again as ordinary, spendable local currency. A traveler or household preparing for a trip would typically convert dollars into a stablecoin through a licensed exchange, a bank partner, or increasingly a card or payment app that handles the conversion behind the scenes, a step that generally carries a modest fee, often well under one percent for a well-established platform working with a major stablecoin, though this varies by provider and by how the conversion is bundled into a broader product. Moving the resulting stablecoin across the underlying blockchain network to wherever it needs to go typically carries only a small network fee, often a fraction of a cent to a few dollars depending on which blockchain is used and how congested it is at that moment, a cost that is trivial compared to the percentage-based markups charged by kiosks and card networks precisely because it does not scale with the size of the transaction the way a percentage-based fee does.
The off-ramp, converting the stablecoin back into spendable local currency at the destination, is generally where more of the remaining friction and cost still lives, since it depends heavily on how well-developed the on-chain financial infrastructure is in the specific country a traveler has landed in. In markets with mature, well-integrated stablecoin off-ramps, conversion back into local currency can happen almost instantly through a partner exchange, a local payment app, or a card that spends directly against a stablecoin balance without requiring an explicit manual conversion step at all. In markets with thinner infrastructure, converting a stablecoin balance back into cash a traveler can actually use at a local restaurant or shop may require routing through fewer available exchanges, potentially at a less competitive rate, or simply not being a realistic option at all, which is precisely why most of the real-world products discussed in the next section have taken the more practical route of building a spendable card on top of a stablecoin balance rather than asking a traveler to manage on-chain conversions manually at every stop on a trip.
None of this friction is unique to stablecoins in the sense of being worse than the traditional alternative; a traditional international wire transfer or a currency exchange in a market with few competing kiosks carries its own version of the same problem, thin markets producing worse pricing and more friction regardless of which underlying technology is being used. What is different about the on-chain approach is that the on-ramp and off-ramp fees, even when they exist, tend to be transparent, quoted in advance, and structurally smaller than the layered markups discussed in the previous section, since a well-run stablecoin conversion is typically closer to the actual mid-market rate than a kiosk or DCC transaction is ever designed to be. That gap between a transparent, close-to-market conversion and an opaque, multiply-marked-up one is the entire economic case for on-chain currency exchange, and it is the case study evidence in the following section, rather than the underlying technology alone, that shows this gap actually holding up in real products used by real travelers.
Stablecoin Travel Cards and Payment Rails in Practice
The idea of converting money into a stablecoin and back again would matter very little to an ordinary traveler if it only existed as a manual, technically demanding process requiring a person to operate their own cryptocurrency wallet at every stop on a trip. What has changed the practical relevance of this technology for households rather than cryptocurrency enthusiasts is the emergence of mainstream financial products that handle the stablecoin layer invisibly, behind a card a traveler can simply tap or swipe the same way they would with any other card. Two developments in particular illustrate how far this has progressed in a short period of time: a consumer-facing card product that lets a traveler spend directly against a stablecoin balance, and a major card network’s own decision to settle transactions between banks in stablecoins rather than through the traditional, slower settlement rails that have underpinned international card payments for decades.
These two developments sit at different points in the payment chain, one facing the traveler directly at the point of sale and the other operating quietly in the background between financial institutions, but they are connected by the same underlying shift: large, established players in consumer payments have concluded that stablecoin-based rails are now mature and reliable enough to build real products on top of, rather than remaining a niche experiment confined to cryptocurrency-native companies. The two subsections that follow examine each development as a specific, dated, verifiable case study, since the value of this section lies less in the general concept, already covered above, than in demonstrating that the concept has moved from theory into products that travelers and banks are actually using today.
The Ether.fi Cash Card: A Stablecoin-Funded Spending Case Study
Ether.fi, a company built around decentralized finance infrastructure, announced its Cash Card, a Visa-branded card designed to let users spend directly against crypto and stablecoin holdings, with reporting on the announcement, including coverage by the cryptocurrency news outlet CoinDesk, dating to September 9, 2024, when the card was described as launching on the Scroll blockchain network. The card’s core design lets a holder spend against assets, including stablecoins such as USDC, without necessarily needing to fully liquidate a broader crypto portfolio first, using the stablecoin or borrowed value against staked holdings as the spendable balance that settles as an ordinary Visa transaction at the point of sale, meaning a merchant abroad sees a standard card payment with no awareness that the underlying funding source involved a blockchain-based conversion at all. Following its initial rollout, the card moved through a broader release across 2025, expanding into additional markets and tiers, with the free entry-level tier offering a cashback structure that included an enhanced rate specifically on travel-related spending such as hotel stays, a detail that reflects the product being deliberately positioned, at least in part, toward travelers rather than only toward cryptocurrency traders managing a portfolio.
What makes the Ether.fi Cash Card a genuinely useful case study for this article is not that it is the largest such product in the market, but that it demonstrates concretely how the theoretical advantage described in the previous section, avoiding layered currency conversion markups by spending against a stablecoin balance rather than routing a purchase through a traditional foreign-transaction-fee card, has been built into an actual consumer product rather than remaining a hypothetical. Because the underlying spending power is denominated in a dollar-pegged stablecoin rather than a traditional bank balance, a purchase made abroad on such a card can settle closer to the prevailing market exchange rate than a purchase on a card carrying the traditional one-to-three-percent foreign transaction fee layered on top of whatever markup the card network itself applies, though the precise savings depend on the specific card, the currency pair involved, and market conditions at the time of the transaction, a caveat that applies to every cost comparison discussed anywhere in this article. The broader significance of a card like this is less about any single company’s product and more about what its existence signals: that stablecoin-funded spending has moved from an idea to a shipping, Visa-network-compatible product that a traveler can apply for, load, and use at ordinary merchants abroad the same way they would use any other travel card.
Visa’s USDC Settlement Network and What It Means at Checkout
While the Ether.fi Cash Card illustrates stablecoin adoption at the consumer-facing edge of a transaction, Visa’s own infrastructure work illustrates the same shift happening on the institutional side of the payment chain, in the settlement process between banks that most travelers never see but that shapes the cost and speed of every card transaction they make. Visa became one of the first major payment networks to pilot settling transactions using a stablecoin, specifically USDC, in 2023, and the company expanded that pilot over the following two years into additional regions, including parts of Latin America, Europe, Asia-Pacific, and the broader CEMEA region covering Central Europe, the Middle East, and Africa. The most consequential milestone in that expansion arrived in December 2025, when Visa announced it was launching USDC settlement for banks in the United States itself, with Cross River Bank and Lead Bank becoming its first U.S. issuer and acquirer partners to begin settling transactions with Visa in USDC over the Solana blockchain network, a launch the company noted followed its monthly stablecoin settlement volume crossing a $3.5 billion annualized run rate as of November 30, 2025.
This development matters for ordinary travelers even though it operates almost entirely behind the scenes, because settlement, the process by which banks actually exchange funds with each other after a card transaction has already been approved at the point of sale, has traditionally been one of the slower and more operationally costly parts of running an international card network, particularly across weekends and holidays when conventional banking rails are closed. Visa has specifically cited faster funds movement, seven-day availability rather than being limited to conventional banking hours, and improved operational resilience as direct benefits of settling in USDC rather than through traditional correspondent banking channels, benefits that flow through to issuers and, over time, plausibly to the fees and rates issuers pass on to cardholders as this infrastructure matures and becomes more widely adopted across the network. Unlike a stablecoin-funded card a traveler applies for directly, Visa’s settlement shift does not require any action from a cardholder at all, and a traveler using an entirely ordinary Visa card abroad may already be benefiting, in some small part, from faster and more resilient settlement rails without any awareness that a stablecoin was involved anywhere in the chain, which is arguably the clearest sign that this technology has moved from a niche cryptocurrency experiment into genuine, if largely invisible, financial infrastructure.
Together, these two case studies show the shift happening from both directions at once: a consumer-facing card letting a traveler spend directly against stablecoin holdings, and the underlying network those cards and countless others run on shifting part of its own settlement infrastructure toward the same technology. Neither development means every card a traveler carries today already routes through stablecoin rails, and the traditional layered costs described earlier in this article remain the default experience for most travelers using most conventional cards, but both developments illustrate that the infrastructure enabling a genuinely lower-cost alternative is no longer speculative or experimental, and is instead already processing billions of dollars a year in real transaction volume.
Cross-Border Rails Beyond Cards: The MoneyGram-Stellar Case
Cards and point-of-sale settlement are not the only place stablecoin-based infrastructure has begun replacing traditional cross-border money movement, and a traveling household’s currency needs are not always limited to card swipes at a restaurant or hotel. Households often need to move a larger sum of money across a border before or during a trip, prefunding a local account, sending money ahead to a family member already at the destination, or simply converting a lump sum of a travel budget into local currency in a way that does not depend on card infrastructure at all, and this is the specific use case that MoneyGram, one of the world’s largest traditional money transfer companies, has built directly into its own network using stablecoin rails.
MoneyGram first announced a partnership with the Stellar Development Foundation, the nonprofit organization supporting the Stellar blockchain network, in October 2021, but the partnership moved from announcement to actual live service in June 2022, when the two organizations announced the initial rollout of a global on-and-off-ramp service connecting MoneyGram’s extensive cash network with USDC held in digital wallets, launching first in key remittance markets including Canada, Kenya, the Philippines, and the United States, with plans to expand cash-out availability more broadly by the end of that same month. The mechanism works in both directions: a person can walk into a MoneyGram location, hand over cash, and have it converted into USDC that lands in a digital wallet, or conversely, hold USDC in a wallet and walk into a MoneyGram location in another country to convert it back into local cash, a structure that effectively uses MoneyGram’s existing global network of physical retail locations, built up over decades of traditional remittance business, as the off-ramp infrastructure that a purely digital-native stablecoin system would otherwise lack in markets where digital banking penetration remains limited. MoneyGram also stated it would waive transfer fees on this service for its first year of operation as an adoption incentive, a detail that matters for evaluating the cost comparison later in this article, since it demonstrates that stablecoin-based transfer costs are not fixed at some inherent technical minimum but are, like traditional remittance pricing, shaped by deliberate business decisions about what a provider chooses to charge.
The significance of this case study for a traveling household is somewhat different from the two card-focused case studies discussed earlier, since it addresses a need that predates and sits alongside modern travel cards: moving a meaningful lump sum of money internationally, whether for a family member relocating temporarily, a household prefunding an account before a longer stay abroad, or simply converting savings into a form that can be accessed as cash in multiple countries during a single extended trip. MoneyGram’s approach also illustrates a broader pattern that shows up across nearly every serious real-world stablecoin payment product examined in this article: the technology succeeds commercially not by asking an ordinary user to become fluent in blockchain mechanics, but by wrapping the stablecoin layer inside familiar, trusted infrastructure, a retail counter, a card network, a bank settlement system, that a traveler or a family member already understands and already trusts, leaving the on-chain conversion working quietly in the background exactly as Visa’s settlement shift does in the previous section. The company has continued building on this foundation since the initial 2022 rollout, including announcing plans in September 2023 for a non-custodial digital wallet built on the Stellar network, extending the same underlying rails toward a more self-directed product rather than only the assisted, in-person cash conversion the original service was built around.
A Realistic Cost Comparison for a Traveling Household
With the mechanics and the real-world infrastructure established, the more useful question for an actual traveling household is what these differences add up to in practical terms across a real trip. Consider a household of four traveling internationally for two weeks with a discretionary spending budget of four thousand dollars set aside for meals, local transportation, incidentals, and a cash reserve for situations where cards are not accepted, a fairly ordinary travel budget for a mid-length international trip involving a family rather than a solo traveler. The way that four thousand dollars actually reaches the household’s hands and gets spent abroad looks meaningfully different depending on which of the three approaches described throughout this article the household relies on, and running through each one with real, defensible figures makes the earlier, more abstract discussion of markups and fees concrete in a way percentages alone rarely achieve.
A household relying primarily on airport kiosk exchanges for its cash needs and paying with a standard card carrying a typical foreign transaction fee for everything else faces the most layered version of these costs. If roughly half of that four-thousand-dollar budget, two thousand dollars, is exchanged for cash at an airport kiosk carrying a markup toward the higher end of the commonly cited five-to-fifteen-percent range, perhaps ten percent once the spread and any flat commission are combined, that single decision costs the household in the neighborhood of two hundred dollars compared with a conversion closer to the mid-market rate, money that simply evaporates into the kiosk’s margin before a single meal has been purchased. The remaining two thousand dollars, spent by card across the two-week trip, carries a more modest but still real foreign transaction fee, commonly around three percent on a card without travel-specific fee waivers, adding another sixty dollars in fees spread quietly across dozens of individual purchases small enough that no single one draws attention. If even a portion of those card transactions involve a dynamic currency conversion prompt accepted at a restaurant or shop, the effective cost rises further, since DCC markups documented in the academic literature discussed earlier in this article commonly run several percentage points worse than the rate the card network would have applied automatically. Added together, a household following this fairly ordinary path, an airport kiosk for cash and a standard card for the rest, can reasonably expect to lose somewhere in the range of two hundred fifty to three hundred fifty dollars of its four-thousand-dollar budget purely to currency conversion costs, money that bought the household nothing beyond the conversion itself.
A household that instead uses a stablecoin-funded card of the kind examined in the Ether.fi case study, converting a portion of its travel budget into USDC before departure and spending directly against that balance, faces a substantially flatter cost structure. The initial conversion from dollars into USDC on an established platform typically carries a fee well under one percent, and because the card spends directly against a dollar-pegged balance rather than routing through a foreign-transaction-fee structure, purchases abroad settle much closer to the prevailing market rate rather than absorbing a multi-percent markup on every transaction. Applied to the same four-thousand-dollar budget, the household’s total conversion-related cost under this approach might reasonably fall in the range of forty to eighty dollars, the bulk of it concentrated in the single upfront on-ramp conversion rather than spread invisibly across every purchase, with essentially no equivalent to the kiosk markup or the DCC risk built into the traditional path, since there is no kiosk transaction and no home-currency prompt to decline or accidentally accept at the point of sale. The gap between roughly three hundred dollars lost under the traditional approach and well under one hundred dollars lost under the stablecoin-card approach, on an otherwise identical four-thousand-dollar trip budget, illustrates the practical scale of what this article has been describing in more abstract terms throughout its earlier sections, though a household should treat these as illustrative figures rather than a guarantee, since actual costs shift with the specific provider, the currency pair involved, and market conditions on the day of travel.
A third scenario worth considering involves a larger lump-sum transfer rather than ordinary daily spending, closer to the MoneyGram case study discussed in the previous section, relevant for a household prefunding a longer stay abroad or supporting a family member already at the destination. Moving a substantial sum, say fifteen hundred dollars, through a traditional international wire transfer commonly involves a combination of a flat sending fee, an intermediary bank fee that is not always disclosed in advance, and an exchange rate markup embedded in the transfer itself, a combination that can plausibly cost a household somewhere between thirty and eighty dollars depending on the receiving country and the specific banks involved. The same transfer routed through a stablecoin-based on-and-off-ramp service, particularly one waiving transfer fees as an adoption incentive the way MoneyGram did during its first year of the Stellar-linked service, can meaningfully undercut that cost, though a household evaluating this option should confirm current fees directly with the provider, since promotional fee waivers are, by their nature, temporary rather than permanent features of a service.
Across all three scenarios, the consistent pattern is not that on-chain currency exchange eliminates the cost of converting money entirely, since a genuinely free conversion does not exist under any of the approaches examined in this article, but that it tends to compress a layered, opaque set of markups into a smaller number of more transparent, lower-percentage fees, disclosed closer to the time of conversion rather than buried inside a kiosk’s spread or a card’s fine print. A household’s actual savings will always depend on trip length, spending patterns, destination, and the specific providers involved, and this comparison should be read as an illustration of the general shape of the cost difference rather than a precise prediction for any individual trip.
Risks, Limits, and Who This Doesn’t Work For
None of the preceding cost comparison should be read as suggesting on-chain currency exchange is a strictly better replacement for every traveler in every situation, and a fair account of this technology has to address its real limits alongside its real advantages. The clearest limit is simply access: a household needs a smartphone, a reasonably reliable data or wifi connection, and comfort setting up and using a digital wallet or a stablecoin-linked card, none of which can be assumed universally, particularly for older travelers less accustomed to managing financial apps, or for trips to remote destinations where reliable connectivity itself cannot be taken for granted. A traveler who forgets a wallet password, loses access to a device holding the relevant app, or encounters a destination where the specific card or wallet simply is not accepted anywhere nearby is left in a meaningfully worse position than a traveler carrying physical cash and a widely accepted conventional card, since recovering from that kind of access failure abroad, away from familiar customer support channels and in an unfamiliar regulatory environment, can be considerably harder than replacing a lost traditional card.
The subsection that follows addresses three further, more specific categories of risk in more detail: the residual volatility that exists even at the edges of a system built around supposedly stable assets, the liquidity gaps that show up unevenly across different countries, and the patchwork, still-evolving regulatory treatment of stablecoins that varies significantly from one jurisdiction to another.
Volatility at the Edges, Liquidity, and the Regulatory Patchwork
Even a well-established, dollar-pegged stablecoin is not entirely free of the volatility risk this article described earlier as largely absent compared with a traditional cryptocurrency like bitcoin, since a stablecoin’s peg is only as reliable as the reserves and management practices backing it, and the broader stablecoin category has seen isolated instances of smaller or less rigorously managed tokens temporarily losing their peg under stress. A traveler relying on one of the large, well-established stablecoins used in the mainstream products discussed in this article faces meaningfully lower exposure to this risk than someone using a smaller, less scrutinized token, but the risk is not reduced to precisely zero, and a household evaluating this approach should understand that a stablecoin’s stability rests on the ongoing soundness of a private company’s reserve management rather than on a government guarantee comparable to deposit insurance on a traditional bank account.
Liquidity, the practical ability to convert a stablecoin balance back into usable local cash at a fair rate, remains genuinely uneven across the world, as the earlier discussion of on-ramps and off-ramps described in more general terms. A traveler visiting a country with well-developed digital financial infrastructure and an established local exchange or card partner is likely to experience the smooth, low-cost conversion described throughout this article, while a traveler visiting a smaller or less digitally developed market may find fewer off-ramp options, less competitive rates among the options that do exist, or, in some destinations, no practical off-ramp at all, functionally limiting a stablecoin-based approach to card-based spending at merchants that directly accept it rather than to converting a balance into physical cash. This unevenness is not a permanent, fixed feature of the technology so much as a reflection of where the underlying infrastructure, exchanges, licensed partners, integrated card programs, has been built out so far, but it is a real, present-day limitation rather than a purely theoretical one, and a household should research the specific availability of a given card or service at its actual destination before assuming the smooth experience described in the cost comparison above will hold everywhere.
Regulatory treatment of stablecoins also varies considerably by country and continues to shift, a dynamic distinct from, though related to, the liquidity question above. The United States moved to establish clearer federal rules for payment stablecoins with the GENIUS Act, signed into law in July 2025, which set out reserve, disclosure, and oversight requirements for stablecoin issuers and gave the card programs and settlement products discussed earlier in this article a clearer legal foundation to build on domestically. Other countries have taken different, sometimes more cautious or more restrictive approaches, and a traveler moving between jurisdictions with meaningfully different rules around stablecoin custody, taxation, or reporting should not assume that a product working smoothly and legally in one country will necessarily work the same way, or be treated the same way by local authorities, in another, a genuinely practical consideration alongside the cost savings this article has otherwise focused on.
Final Thoughts
On-chain currency exchange represents a real, structural shift in how the cost of moving money across a currency boundary can be organized, replacing a layered stack of largely opaque markups, an airport kiosk spread, a dynamic currency conversion prompt, a foreign transaction fee, an ATM surcharge, with a smaller number of more transparent conversions priced closer to the actual mid-market rate. That shift matters most immediately for the ordinary traveling household this article has focused on, the family converting a fixed travel budget for a two-week trip, the person sending money ahead to relatives already abroad, but its significance runs somewhat deeper than convenience or savings for any single trip. A payment system’s cost structure shapes who can participate in it comfortably and who is quietly taxed by their own lack of financial sophistication, and the 2023 research on dynamic currency conversion discussed earlier in this article, showing that less financially literate consumers were disproportionately harmed by an opaque point-of-sale choice, is a pointed reminder that traditional cross-border payment infrastructure has never been a neutral, evenly distributed cost for everyone who uses it.
The infrastructure enabling a genuinely different approach is no longer experimental or confined to specialized cryptocurrency platforms. A major card network settling billions of dollars a year through stablecoin rails, a consumer card letting a traveler spend directly against a stablecoin balance, and one of the world’s largest traditional remittance companies building a working cash-to-stablecoin bridge across major global markets are not proofs of concept; they are functioning products handling real transaction volume today, each with a specific, verifiable date attached to its launch or expansion. That maturity is itself the more significant development this article has traced, since a technology’s real-world impact on ordinary households depends far less on its theoretical elegance than on whether it has actually been built into products people can use without becoming financial technology specialists themselves, and each case study examined here shows a large, established institution making exactly that bet.
None of this erases the technology’s genuine limits, and this article has tried to be direct about those: uneven liquidity between countries, a regulatory landscape still being written in real time, and a residual, reduced form of the volatility risk that has always accompanied digital assets. A traveler weighing a stablecoin-funded card against a traditional one is not choosing between a flawless new system and a flawed old one, but between two systems carrying different tradeoffs, and the right choice for any household depends on where they are traveling, how comfortable they are managing a digital wallet under time pressure abroad, and how much of their budget the layered costs described throughout this article would otherwise consume.
What seems clear is that the direction of travel, in the most literal sense of the phrase, favors continued growth in this kind of infrastructure rather than its retreat, as more banks, card issuers, and payment companies conclude that stablecoin rails offer a faster, more transparent, and often cheaper way to move value across the exact currency boundaries that have quietly taxed travelers for as long as international travel has existed. Financial inclusion has always been partly a story about who bears the hidden cost of an inefficient system, and a genuinely lower-cost, more transparent way to convert money abroad has real value for exactly the households least able to absorb an unnoticed few hundred dollars disappearing into a kiosk’s spread or a card’s fine print over the course of a single trip.
FAQs
- What does “on-chain currency exchange” actually mean for a traveler?
It refers to converting money into a stablecoin, a dollar-pegged digital token, moving it across a blockchain network, and converting it back into local currency, typically through a card or app that handles the process automatically rather than requiring the traveler to manage a cryptocurrency wallet manually. - What is a stablecoin, and how is it different from bitcoin?
A stablecoin is a cryptocurrency designed to hold a steady value pegged to a currency like the U.S. dollar, typically backed by cash and short-term government securities held in reserve. Unlike bitcoin, which fluctuates significantly in price, a stablecoin like USDC is engineered specifically to avoid that volatility. - How much does an airport currency exchange kiosk typically mark up its rates?
Airport kiosks commonly charge somewhere between five and fifteen percent above the mid-market exchange rate, depending on the currency pair, the specific location, and how much nearby competition exists, often compounded further by a separate flat commission or service fee. - What is dynamic currency conversion, and why should travelers be cautious about it?
Dynamic currency conversion, or DCC, is a prompt at a card terminal or ATM asking whether a charge should be processed in the traveler’s home currency rather than the local one. Accepting it hands control of the exchange rate to the merchant’s payment processor, which typically applies a rate worse than the card network’s own default rate. - What is the Ether.fi Cash Card, and how does it relate to stablecoin travel spending?
The Ether.fi Cash Card is a Visa-branded card, announced in September 2024 and expanded through 2025, that lets holders spend directly against crypto and stablecoin balances, including USDC, avoiding the layered foreign transaction markups typical of conventional travel cards. - Has a major card network actually adopted stablecoin settlement, or is this still experimental?
It is no longer experimental. Visa piloted USDC settlement starting in 2023, expanded it across multiple regions, and launched USDC settlement for U.S. banks in December 2025 after its stablecoin settlement volume crossed a $3.5 billion annualized run rate. - How does MoneyGram’s stablecoin service work for someone sending money abroad?
MoneyGram’s service, built with the Stellar Development Foundation and live since June 2022, lets a person convert cash into USDC at a MoneyGram location and lets a recipient elsewhere convert that USDC back into local cash at another MoneyGram location, using the company’s existing retail network as the off-ramp. - How much can a household realistically save using stablecoin-based conversion instead of an airport kiosk and a standard card?
On an illustrative four-thousand-dollar travel budget for a two-week trip, a household using airport kiosks and a standard foreign-transaction-fee card might lose roughly two hundred fifty to three hundred fifty dollars to conversion costs, compared with roughly forty to eighty dollars using a stablecoin-funded card, though actual figures vary by provider, route, and market conditions. - What are the main risks or limits of relying on stablecoins while traveling?
Key limits include dependence on a smartphone and reliable connectivity, uneven off-ramp availability and liquidity in less digitally developed markets, a residual, reduced form of volatility risk if a stablecoin’s peg comes under stress, and a regulatory landscape that still varies significantly between countries. - Is on-chain currency exchange legal and regulated?
In the United States, the GENIUS Act, signed into law in July 2025, established federal reserve, disclosure, and oversight requirements for payment stablecoins. Regulatory treatment still varies by country, so travelers should confirm the rules that apply in any specific destination before relying on it there.