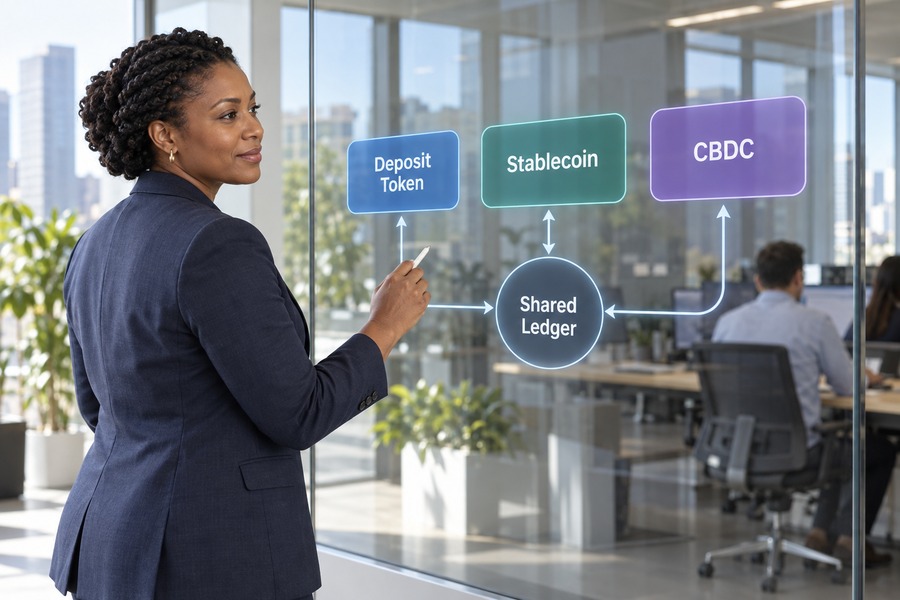
Most of the public conversation about digital money over the past several years has centered on stablecoins — tokens like USDT and USDC that trade around the clock, settle in seconds, and have grown into a market worth hundreds of billions of dollars. Regulators have written new laws for them, payment companies have built products around them, and crypto exchanges have made them the default unit of account for trading. Far less attention has gone to a quieter, parallel development happening inside the world’s largest commercial banks: the same institutions that stablecoins were partly designed to bypass have started issuing their own programmable, blockchain-based tokens, built not from reserve assets sitting in a separate trust but from the ordinary deposits their corporate clients already hold with them. These are called deposit tokens, and unlike a stablecoin, a deposit token is not a new kind of asset sitting alongside the banking system. It is a digital wrapper around a liability the bank already owes its client, moved onto a shared or distributed ledger so it can settle instantly, operate continuously, and carry programmable conditions the way a stablecoin can, without ever leaving the bank’s balance sheet or the regulatory perimeter that governs ordinary deposits.
The distinction matters more than it might first appear, because the three major forms of digital money now circulating in institutional finance — deposit tokens, stablecoins, and central bank digital currencies, or CBDCs — represent fundamentally different claims with fundamentally different risk profiles, even though all three can look similar on the screen of a corporate treasury dashboard. A deposit token is a claim on a regulated bank, subject to the same capital rules, supervision, and, in many jurisdictions, deposit insurance that already apply to the money sitting in a checking account. A stablecoin is typically a claim on a non-bank issuer, backed by a reserve of assets the issuer holds, managed under a newer and still-evolving set of rules that vary significantly by country and, in the United States, took a major step toward clarity only in 2025. A CBDC is different again: a direct liability of a central bank itself, the same institution that issues physical currency, carrying essentially no credit risk but raising its own separate questions about privacy, financial stability, and the central bank’s role in retail payments. Conflating these three, as casual coverage of “crypto” or “digital dollars” often does, obscures who actually bears the risk when something goes wrong and which set of laws and regulators actually govern the token in a person’s hand.
This article walks through why major banks have concluded that tokenizing their own deposits is worth the considerable engineering and regulatory effort involved, what a deposit token actually is and how it is structured under the hood, and how it stacks up against stablecoins and CBDCs on the specific dimensions that matter to anyone trying to understand where their money actually sits and who is on the hook if an institution fails. It examines three real, documented, and independently verifiable deployments — JPMorgan’s Kinexys platform and its JPM Coin deposit token, Citi’s Token Services platform and its trade-finance pilot with the shipping company Maersk, and Partior, the multi-bank settlement network built jointly by JPMorgan, DBS, and Standard Chartered — that show what deposit tokenization looks like once it moves beyond a whitepaper and into institutions moving real client money. It also takes seriously the open questions: how regulators are treating this new instrument relative to stablecoins, what happens when multiple banks each build their own token on different, incompatible ledgers, and whether deposit tokens can scale from a niche institutional tool into something that touches the broader economy. None of this suggests that deposit tokens will simply displace stablecoins or that banks have already solved the problem of moving money as fast as the internet moves information. It is a look at a specific, well-documented financial innovation, what it has actually achieved so far, and why it deserves a place in the conversation about the future of money alongside the more widely discussed alternatives.
Why Banks Are Tokenizing Deposits Now
The pressure driving banks toward deposit tokenization traces back to a mismatch that has become increasingly uncomfortable for large corporate clients: the world’s biggest companies now operate globally and continuously, moving goods, invoices, and payroll across time zones every hour of every day, while the core infrastructure banks use to move money between them still largely runs on a business-hours, batch-processing model built decades ago. A treasurer at a multinational shipping or manufacturing company who needs to move funds from a subsidiary in one country to a supplier in another is often still working within cutoff times, correspondent banking chains, and settlement windows that can take a full business day or more to clear, even though the underlying technology to move information instantly has existed for years. That gap between what modern digital infrastructure can do in other domains and what traditional payment rails still require has become a recurring source of friction, and increasingly a source of real financial cost, since capital sitting in transit or trapped behind a cutoff time is capital that a corporate treasury cannot deploy, invest, or use to meet an obligation elsewhere.
Stablecoins emerged as one answer to this mismatch, and their growth has not gone unnoticed inside the banks whose deposit base and payment fee revenue stablecoins compete with directly. When a corporate client can settle a cross-border payment in a stablecoin that clears on a public blockchain in seconds, at any hour, for a fraction of the cost of a traditional wire, that client has less reason to route the transaction through a bank’s correspondent network at all, and every dollar that moves into a stablecoin instead of a bank deposit is a dollar that no longer funds that bank’s lending book. This is not a hypothetical concern for bank management teams; it is a direct, balance-sheet-level threat, since commercial banks fund a significant share of their lending activity from the deposits clients keep with them, and a large-scale migration of corporate cash into stablecoins would represent exactly the kind of deposit flight that bank regulators and bank executives alike have started to study closely as stablecoin adoption has accelerated.
Rather than simply competing against this shift by improving marketing or lowering fees on existing payment rails, the largest global banks concluded that the more durable response was to offer their own version of what stablecoins provide — continuous, programmable, near-instant settlement — while keeping the underlying asset inside the regulated banking system rather than watching it migrate outside it. A deposit token lets a bank offer a client the same practical experience a stablecoin offers, a digital token that moves at any hour and can be embedded in smart contracts and automated payment logic, while ensuring that the money represented by that token remains a deposit liability on the bank’s own books, funding the bank’s lending activity exactly as it did before tokenization and remaining subject to the same prudential regulation and, where applicable, deposit insurance that governs conventional deposits. This is the strategic logic behind the deposit token projects examined later in this article: not an attempt to compete with blockchain technology, but an attempt to adopt its practical benefits without surrendering the deposit base and regulatory position that define what a bank actually is. The urgency behind this shift has only grown as regulatory clarity around stablecoins has improved, since a clearer legal framework for non-bank stablecoin issuers removes one of the barriers that previously slowed corporate adoption, giving banks a narrowing window to offer a comparably fast, comparably programmable alternative before corporate treasury workflows settle permanently around stablecoin rails instead.
What a Deposit Token Actually Is
Stripped of its technical wrapping, a deposit token is best understood as a digital certificate of ownership over a specific claim on a bank, issued and recorded on a shared ledger so that the claim can be transferred between authorized parties without the bank needing to manually process every movement through its traditional core banking system. When a corporate client deposits funds with a bank that offers this service, the bank can mint a corresponding token, denominated in the same currency and equal in value to the underlying deposit, and record that token on a permissioned ledger that the bank operates or participates in alongside other trusted institutions. The client can then transfer that token to another party — another division of their own company, a business partner, a counterparty in a trade transaction — and because the transfer happens on the ledger rather than through a traditional payment message routed between separate bank systems, it can settle in near real time, at any hour, including weekends and holidays when conventional interbank payment systems are typically closed.
Crucially, the deposit represented by that token never actually leaves the issuing bank. The bank still holds the underlying funds, still counts them as a deposit liability on its balance sheet, and still uses them to support its lending and investment activities exactly as it would with any other deposit. What changes is not where the money sits, but how the claim on that money can move: instead of requiring the bank to update separate ledgers on both the sending and receiving side of a transaction and reconcile them after the fact, often introducing delay and manual work, a deposit token allows ownership of the underlying claim to change hands directly on a shared record that every authorized party can see and trust. This is the feature that makes deposit tokens attractive for institutional treasury operations specifically: it offers the settlement speed and programmability of a blockchain-native asset while preserving the balance-sheet mechanics, legal status, and regulatory treatment of an ordinary bank deposit.
Two subsections below unpack this concept further. The first examines the actual mechanics of how a deposit token is created, transferred, and redeemed, and why concepts like atomic settlement and finality matter so much to the institutions actually using this technology. The second turns to the comparison that gives this article its title, working through exactly how a deposit token differs from a stablecoin and from a central bank digital currency, since understanding those differences is essential to understanding why banks, rather than fintech startups or central banks, are the ones building this particular piece of financial infrastructure.
How a Deposit Token Is Structured and Settled
The technical process behind a deposit token begins with a bank establishing a ledger-based representation of a client’s existing deposit account, typically on what is called a permissioned distributed ledger, meaning a shared database validated by a defined set of trusted participants rather than an open, anonymous network of the kind that underpins public cryptocurrencies. When a client instructs the bank to tokenize a portion of their deposit balance, the bank’s systems record a corresponding entry on this ledger, creating a token that represents a specific dollar or other currency claim against the bank, while simultaneously updating the client’s core banking record to reflect that the deposit is now represented in tokenized form. This dual bookkeeping, keeping the ledger token and the underlying core banking record synchronized at every step, is one of the more demanding engineering requirements behind a deposit token system, since any divergence between the two records would create exactly the kind of reconciliation problem tokenization is meant to eliminate.
Once minted, a token can be transferred to another party who holds an account on the same ledger, whether that party is a different division of the same corporate client, a separate company entirely, or in the case of multi-bank networks, a client of a different participating bank. The transfer itself is designed to be atomic, a technical term meaning that the transfer either completes in full or does not happen at all, with no intermediate state in which one party has sent funds but the other has not yet received them. This property matters enormously for institutional payments, particularly for transactions that involve exchanging a payment for a corresponding asset or service, since atomic settlement removes what is called settlement risk — the risk that one party fulfills its side of a transaction while the other fails to reciprocate, leaving the first party exposed with no recourse. Traditional payment systems generally cannot offer this guarantee across separate institutions without an intermediary absorbing that risk, which is one of the specific problems that shared deposit token ledgers, and the multi-bank networks built on top of them, are designed to solve directly.
Redemption works in the reverse direction: when a token holder wants to convert their tokenized claim back into an ordinary, non-tokenized deposit balance, or to withdraw it from the system entirely, the bank burns or retires the corresponding token on the ledger and updates the client’s core account balance accordingly, ensuring that the total value of tokens in circulation always matches the underlying deposits they represent. Because this reconciliation happens continuously and automatically rather than through periodic batch processing, a well-designed deposit token system can offer clients near-continuous visibility into their actual, current balance rather than a snapshot that may be hours or days out of date, which is itself a meaningful operational improvement for corporate treasurers managing liquidity across many accounts and currencies simultaneously.
Deposit Tokens vs. Stablecoins vs. CBDCs
The clearest way to understand the difference between these three forms of digital money is to ask a simple question in each case: whose liability is this, and what happens to the holder if that issuer runs into trouble. A deposit token is a liability of the commercial bank that issued it, exactly like an ordinary checking or savings deposit, which means it sits inside the same regulatory framework that has governed bank deposits for decades. The issuing bank must hold capital against its balance sheet, submit to prudential supervision from banking regulators, and in jurisdictions with deposit insurance schemes, such as the Federal Deposit Insurance Corporation in the United States, a deposit token representing an insured deposit type is generally understood to carry the same insurance protection, up to the applicable coverage limit, that the underlying deposit would carry in its non-tokenized form. If the issuing bank fails, a deposit token holder stands in the same position as any other depositor of that bank, protected by the same insurance and resolution framework, rather than facing a scenario unique to the token itself.
A stablecoin, by contrast, is typically issued by a non-bank entity — a company whose primary business is issuing and managing the stablecoin itself, rather than taking deposits and making loans the way a bank does — and its value is maintained not through banking regulation and deposit insurance but through a reserve of assets the issuer holds and pledges to redeem the token against, commonly short-term government securities, cash, and cash equivalents. The specific rules governing what a stablecoin issuer can hold in reserve, how often those reserves must be audited, and what happens to token holders if the issuer becomes insolvent are considerably newer and, in most of the world, less battle-tested than the century-old framework governing bank deposits. In the United States, this changed meaningfully in 2025 with the enactment of federal legislation establishing a licensing and reserve framework specifically for payment stablecoins, requiring issuers to hold reserves in high-quality, liquid assets on a one-to-one basis and to undergo regular independent audits, a framework intended to close the gap between stablecoin oversight and bank oversight but one that remains structurally different: a stablecoin holder’s protection comes from the adequacy and quality of the issuer’s reserve assets and the enforcement of that new regulatory regime, not from deposit insurance, since a stablecoin is generally not itself an insured deposit even when the reserve assets backing it happen to be held at an insured bank.
A CBDC occupies a third, distinct category entirely: it is a direct liability of the central bank itself, the same institution responsible for issuing a country’s physical currency and setting its monetary policy. Holding a CBDC is, in a meaningful sense, safer from a pure credit-risk standpoint than holding either a deposit token or a stablecoin, since a central bank cannot become insolvent in its own currency the way a commercial bank or a private company can. But this greater safety comes with tradeoffs that have made CBDCs considerably more contentious and slower to roll out than deposit tokens or stablecoins, particularly for retail use: a retail CBDC would let ordinary account holders move their money directly to a central bank liability, potentially draining commercial bank deposits at scale during periods of stress and raising serious questions about the central bank’s role in a space traditionally occupied by private banks, along with substantial privacy and surveillance concerns tied to a central bank having visibility into individual transaction histories. Partly for these reasons, most CBDC work to date, including in major economies exploring the concept, has moved more cautiously and, in several cases, focused on wholesale, interbank applications rather than retail deployment, which stands in contrast to the more commercially driven, already-operational deposit token projects examined later in this article.
Putting these three side by side clarifies why deposit tokens occupy a distinct middle position: they offer much of the technical experience that makes stablecoins attractive, near-instant and continuous settlement with programmable conditions, while remaining inside the same regulatory box and credit-risk profile as a conventional bank deposit, something a stablecoin generally cannot offer and a CBDC offers in a fundamentally different, centrally-issued form. That combination — blockchain-style functionality with bank-style regulatory and insurance protection — is precisely the value proposition banks are betting corporate clients will find compelling enough to justify the considerable cost of building this infrastructure in the first place.
Benefits Across Banks, Corporate Clients, and the Financial System
For corporate treasurers, the most immediate and tangible benefit of deposit tokens is the ability to move significant sums of money between accounts, subsidiaries, and counterparties at any hour of the day or night, without waiting for a correspondent bank’s cutoff time or a settlement window that only operates during standard business hours in a particular time zone. A multinational company managing cash across dozens of currencies and jurisdictions has historically had to hold larger cash buffers in multiple locations specifically to cover the gap between when a payment obligation arises and when funds can actually arrive through traditional channels, and continuous, near-instant settlement narrows that gap dramatically, freeing up capital that would otherwise sit idle purely to cover timing risk. Because deposit tokens can also be embedded in programmable logic, a treasury team can automate conditional payments — releasing funds automatically once a shipment is confirmed delivered, for instance — in a way that was previously only possible through custom-built systems layered awkwardly on top of traditional payment rails.
For the issuing banks themselves, the benefit is directly connected to the competitive pressure described earlier: a deposit token lets a bank retain a client’s deposit, and the lending capacity that deposit supports, while still offering that client a settlement experience competitive with what a stablecoin can provide. This matters for a bank’s core business model in a way that is easy to understate, since bank profitability depends heavily on the spread between what a bank pays depositors and what it earns lending out those same deposits, and any structural shift of corporate cash away from bank deposits and into stablecoins or other non-bank instruments represents a direct erosion of that funding base. By offering deposit tokens, large banks position themselves to keep participating in, and profiting from, the emerging infrastructure of programmable money rather than ceding that ground entirely to non-bank competitors, while also creating new fee-generating services around instant settlement, automated trade finance, and treasury management that did not exist in the same form before this technology matured.
The financial system as a whole gains a somewhat different benefit, one connected to the point made in the discussion of atomic settlement: a world in which large institutional payments settle instantly and irrevocably, without the multi-day settlement lag and associated counterparty risk that has characterized cross-border banking for generations, is a more stable and less fragile system in several specific respects. Settlement risk, the danger that one party to a transaction fulfills its obligation while the other does not, has historically required elaborate risk-management infrastructure, collateral arrangements, and in some cases outright losses when a counterparty failed mid-transaction; atomic settlement through shared deposit token ledgers removes a meaningful share of that risk mechanically, by design, rather than through additional layers of insurance or collateral. Regulators and central banks have taken a particular interest in this property specifically because it offers a way to modernize the plumbing of the financial system without introducing the novel credit risks that come from moving value outside the regulated banking perimeter entirely, which is a large part of why supervisory bodies have generally been more receptive to bank-led deposit tokenization than to unregulated stablecoin growth. Taken together, these overlapping benefits explain why deposit tokens have moved from a theoretical concept to a live, if still developing, piece of financial infrastructure at several of the world’s largest banks, each pursuing a broadly similar goal through a somewhat different technical and commercial approach, as the case studies that follow make clear.
Documented Case Studies in Bank-Issued Deposit Tokens
Because so much has been written about blockchain-based finance in the abstract, and because a fair amount of that writing describes pilots and proofs of concept that never advanced beyond a press release, it is worth grounding this discussion in projects that have specific, named institutions behind them, published timelines, and, where available, real reported figures rather than aspirational claims. Three deployments stand out for meeting that bar: JPMorgan’s long-running Kinexys platform and its JPM Coin deposit token, which has moved from an internal pilot to a publicly available product with reported transaction volumes in the trillions of dollars; Citi’s Token Services platform, launched commercially in 2023 and tested in a documented pilot with the shipping and logistics company Maersk; and Partior, a multi-bank settlement network jointly built and owned by JPMorgan, DBS Bank, and Standard Chartered, among others, that lets clients of different competing banks settle cross-border, multi-currency payments using tokenized deposits rather than the traditional correspondent banking chain.
These three examples were chosen specifically because each represents a different structural approach to the same underlying idea. JPMorgan’s project shows a single bank building and operating its own deposit token infrastructure, initially for internal and closely controlled institutional use before expanding to a broader base of clients on public blockchain rails. Citi’s project shows a single bank offering deposit tokenization as a discrete commercial product aimed at specific corporate treasury use cases, tested against a real operational problem faced by an actual client. Partior shows the more structurally ambitious model of multiple, otherwise competing banks jointly building and governing shared infrastructure, a model that more closely resembles how payment systems such as card networks or interbank settlement systems have historically been built. Examining all three together gives a more complete picture of how deposit tokenization is actually developing across the banking industry than any single case could provide on its own.
JPMorgan’s Kinexys and the JPM Coin (JPMD) Deposit Token
JPMorgan’s work on programmable, blockchain-based institutional payments dates back further than most of its competitors’ efforts, beginning with the original JPM Coin project under the bank’s blockchain division, previously called Onyx and later rebranded Kinexys. For several years, this earlier version of JPM Coin operated as a permissioned, bank-internal settlement mechanism, allowing large institutional clients to move US dollar value between their own accounts at JPMorgan around the clock, but without functioning as a broadly transferable token available on public blockchain infrastructure the way a stablecoin does. Reporting on the platform in late 2025 described Kinexys as having processed more than three trillion dollars in cumulative transaction volume since its inception, with daily transaction volume exceeding five billion dollars, figures that place it among the largest pieces of blockchain-based financial infrastructure operating anywhere, institutional or otherwise, even though the platform received comparatively little mainstream attention relative to public stablecoins processing similar or smaller volumes.
The more significant recent development came when Kinexys launched JPMD, a USD-denominated deposit token, first as a pilot in June 2025 and then, after completing that pilot, made available for near-instant, twenty-four-hour settlement on Base, a public blockchain network built on Ethereum-related technology. This step matters because it moved JPMorgan’s deposit token model from a purely internal, bank-to-bank settlement tool toward a token that institutional clients could hold and transfer on shared blockchain infrastructure alongside other digital assets, narrowing the practical gap between what a bank-issued deposit token and a public stablecoin can each do from a client’s perspective. Early participants in the JPMD proof of concept, reported at the time of its expanded rollout, included the crypton trading firm B2C2, the cryptocurrency exchange Coinbase, and the payments company Mastercard, each of which completed near-instant issuance and redemption of JPMD as part of testing the token’s practical functionality alongside real institutional counterparties rather than only in a closed internal environment.
Kinexys has continued to expand the technical footprint of its deposit token infrastructure since that initial public launch, announcing in early 2026 a plan developed jointly with the enterprise blockchain firm Digital Asset to deploy JPM Coin directly onto the Canton Network, a separate blockchain platform oriented toward regulated institutional finance, marking JPMorgan’s second public blockchain deployment for its deposit token after the initial launch on Base and signaling an intent to make the token accessible across more than one underlying ledger rather than committing exclusively to a single technical platform. What makes the Kinexys case particularly instructive for understanding deposit tokens generally is the sheer scale of documented volume behind it: this is not a demonstration project run for a conference audience, but an institutional payment rail processing an annualized volume that, by some reporting, already rivals or exceeds the real payment volume moving through public stablecoins, even though JPMD itself as a specific public-facing token launched considerably more recently than the underlying Kinexys settlement infrastructure that supports it.
Citi Token Services and the Maersk Trade-Finance Pilot
Citi took a somewhat different path toward the same broad goal, formally launching Citi Token Services in September 2023 as a commercial product built specifically for the bank’s institutional treasury and trade finance clients. The service tokenizes a client’s existing deposits held with Citi and allows those tokenized deposits to move across Citi’s global network of branches and accounts using the bank’s own private, permissioned blockchain infrastructure built on Ethereum-related technology, enabling continuous, round-the-clock liquidity movement between a corporate client’s accounts in different countries without waiting for the settlement windows that traditional correspondent banking and cross-border wire transfers depend on. Citi explicitly framed the service around two connected use cases at launch: continuous cross-border payments and liquidity management for treasury teams operating across time zones, and automated trade finance, in which smart contracts programmed on top of the tokenized deposit infrastructure can trigger payments automatically once predefined conditions in a trade transaction are satisfied.
The clearest documented illustration of that second use case came through Citi’s pilot with Maersk, the global shipping and logistics company, which tested the platform’s smart contract capability against a specific, previously slow operational process: the issuance of a bank guarantee to a canal authority as part of the shipping process. Under the traditional process, arranging this kind of guarantee typically required days of manual coordination between the shipping company, its bank, and the receiving authority, a delay that can have real operational consequences for a shipping company coordinating vessel schedules and cargo movements across a tightly choreographed global logistics network. Using Citi’s tokenized deposit infrastructure and programmable smart contracts, the pilot demonstrated that the same guarantee and payment process could be executed in minutes rather than days, a reduction Citi and Maersk both described publicly at the time, with a Maersk treasury representative specifically crediting the collaboration for successfully testing this guarantee solution using tokenized deposits and smart contracts under real operational conditions rather than a simulated environment.
What distinguishes the Maersk pilot from a purely theoretical demonstration is that it addressed a concrete, previously documented pain point in an industry, trade finance and shipping logistics, that has historically relied on paper-based guarantees, manual verification, and multi-party coordination measured in days rather than minutes. Citi’s broader Token Services platform has continued to operate as a live offering for institutional clients beyond this specific pilot, with the bank describing the underlying tokenized deposit infrastructure as extending to continuous liquidity management use cases across its institutional client base more broadly, positioning Citi’s approach as one built around integrating deposit tokenization into specific, already-painful corporate treasury and trade workflows rather than launching a general-purpose token first and searching for use cases afterward.
Partior: A Multi-Bank Deposit Token Settlement Network
Where the JPMorgan and Citi projects each represent a single bank tokenizing its own deposits for its own clients, Partior represents a structurally more ambitious attempt to let clients of different, competing banks settle payments directly against one another using tokenized commercial bank money, without routing every transaction through the layers of correspondent banks that traditional cross-border payments typically require. Partior was founded in 2021 as a joint venture between JPMorgan, Singapore’s DBS Bank, and the Singapore state investment company Temasek, with the network’s underlying technology drawing on earlier work from Project Ubin, a multi-year initiative by the Monetary Authority of Singapore that had explored blockchain-based interbank settlement and, at various points, central bank digital currency concepts before that research was redirected toward the commercial deposit token model Partior eventually adopted. Standard Chartered joined as an investor and settlement bank in late 2022, expanding the network beyond its original three founders and adding another globally significant bank to the group of institutions jointly operating the shared settlement infrastructure.
The practical function Partior performs is to let a payment initiated by a client of one member bank settle directly against a receiving client at a different member bank, using tokenized deposits denominated in the relevant currency on each side of the transaction, with the settlement itself happening atomically on the shared ledger rather than through the sequential, multi-day process of correspondent banking, in which a payment message and an underlying value transfer move through one or more intermediary banks before finally reaching the beneficiary. As of the most recently reported network activity, Partior supported settlement in US dollars, Singapore dollars, and euros, with the founding banks having stated an intention to add further currencies over time, and Deutsche Bank, participating alongside DBS, completed what was reported as its first euro-denominated cross-border payment on the network, extending Partior’s currency and bank participation beyond its original founding group.
Partior’s structure highlights a genuinely distinct model for deposit tokenization compared to the single-bank approaches at JPMorgan and Citi: rather than each bank building a closed system that only serves its own clients, Partior functions as shared, jointly governed infrastructure that competing banks collectively own and operate, more closely resembling how existing interbank payment and card network infrastructure has historically been built and governed. This structure raises its own distinct set of questions, particularly around how competing shareholder banks agree on governance, fees, and access rules for a shared utility they jointly control, but it also offers a path toward the kind of broad, cross-institutional interoperability that a single bank’s deposit token, however successful, cannot achieve on its own, since a token that only moves between a single bank’s own clients is inherently more limited than one that can settle directly against a different bank entirely. The network continued to attract new investment following its initial build, closing a sixty-million-dollar Series B funding round in 2024 explicitly framed by its backers around transforming global clearing and settlement infrastructure, a sign that the multi-bank deposit token model has continued to draw both banking industry commitment and outside investor confidence well past its initial launch phase.
Considered together, these three case studies show deposit tokenization advancing along genuinely different paths rather than converging on one single template: a single global bank scaling its own token onto public blockchain infrastructure and racking up trillions in cumulative volume, a single global bank embedding tokenized deposits into a specific, previously slow corporate workflow and measurably compressing its timeline, and a jointly owned, multi-bank network built specifically to let competing institutions settle against each other without the delay and risk of traditional correspondent banking. Each approach carries different tradeoffs around control, interoperability, and the pace at which the technology can scale beyond its founding institutions, but all three point toward the same underlying conclusion: this is no longer a speculative concept confined to internal bank research divisions, but a category of financial infrastructure already handling real, measurable, and in some cases enormous volumes of institutional money.
Regulatory Treatment, Risks, and Open Questions
Banking regulators and international standard-setting bodies have generally approached deposit tokens with more comfort than they have shown toward stablecoins, precisely because a deposit token does not introduce a new category of financial institution or a new type of unbacked liability into the system; it simply changes the technical form in which an already-regulated deposit can be represented and transferred. Because the underlying claim remains a deposit at a supervised bank, existing capital requirements, liquidity rules, and consumer or institutional protections generally continue to apply without requiring an entirely new regulatory framework to be written from scratch, in contrast to stablecoins, which required new legislation, such as the federal framework enacted in the United States in 2025, specifically because no comparable regulatory structure previously existed for a non-bank entity issuing a widely circulating, asset-backed digital token. This relative regulatory comfort is part of why large, heavily supervised banks have been the institutions leading deposit token development, rather than fintech startups, since banks already operate within, and have deep institutional experience navigating, the supervisory relationships that continue to govern this new form of their existing liabilities.
That said, deposit tokens introduce their own set of risks and open questions that regulators, bank risk managers, and the institutions themselves are still working through. One significant question concerns deposit insurance specifically: while a deposit token representing an ordinary insured deposit is generally expected to carry the same insurance protection as the underlying deposit, the practical mechanics of verifying and paying out that protection in a bank failure scenario involving tokenized claims on a shared ledger are considerably less tested than the well-established process for conventional deposit accounts, since deposit insurance regimes were designed decades before blockchain-based claims existed and have only begun to be updated with tokenization specifically in mind. A related concern involves the treatment of deposit tokens on a bank’s balance sheet and in its liquidity planning: because a tokenized deposit can, in principle, move faster and more continuously than a traditional deposit, some banking supervisors have raised the question of whether tokenization could make deposit outflows more sudden and severe during a period of financial stress, compressing what has historically been a multi-day process of depositors withdrawing funds into something that could happen within minutes across an entire client base, a dynamic that has already drawn comparisons to the rapid, technology-accelerated deposit run that contributed to a major regional bank failure in the United States in 2023, even though that specific episode involved conventional digital banking rather than blockchain-based tokens.
A second major open question concerns interoperability between the different deposit token systems that separate banks and networks are building. JPMorgan’s Kinexys platform, Citi’s Token Services, and the jointly owned Partior network each rely on different underlying technical architectures, and a deposit token issued by one bank does not automatically move or settle against a deposit token issued by another bank outside of a shared network specifically built to connect them, the way Partior connects its member banks to one another. Absent broader industry-wide standards or a substantially larger number of interconnected networks, the practical reach of any single bank’s deposit token remains limited to that bank’s own client base and whichever partner networks it has specifically joined, which stands in some contrast to major public stablecoins, which, whatever their other tradeoffs, are generally transferable to any wallet on the relevant public blockchain regardless of which exchange or platform originally issued them to a given user. Resolving this fragmentation, whether through wider adoption of shared networks like Partior, through common technical standards that let different banks’ deposit tokens interact even without joint ownership, or through some other mechanism entirely, will likely determine how far deposit tokenization can realistically extend beyond the largest global banks and their most sophisticated institutional clients.
A further consideration involves how deposit tokens interact with anti-money-laundering and sanctions compliance obligations that banks already carry for conventional deposits, since regulators have generally required that the same client due diligence, transaction monitoring, and reporting obligations apply to tokenized deposit transfers as would apply to an equivalent conventional payment, meaning that the compliance burden banks already carry does not disappear simply because a transaction happens to settle on a blockchain-based ledger rather than through a traditional payment message. Some observers within the industry have also raised longer-term questions about market concentration, noting that the deposit token projects with the most documented scale and volume to date are concentrated among a small number of the world’s largest banks, which have the balance sheet strength, technical resources, and existing institutional client relationships to build and sustain this kind of infrastructure, raising a reasonable question about whether smaller and regional banks will ever be able to participate meaningfully in deposit tokenization or whether the technology will instead further consolidate institutional payment volume among an already-dominant group of global banks. None of these open questions amount to a reason to dismiss deposit tokens as a passing experiment, but they are a necessary corrective against treating the technology as a fully solved problem simply because the largest examples of it have already processed trillions of dollars in volume.
Final Thoughts
Deposit tokens represent something genuinely distinct in the broader story of digital money: an attempt by the existing banking system to absorb the technical advantages of blockchain-based settlement without surrendering the deposit base, the regulatory position, or the credit-risk profile that define what a bank actually is. That distinction is easy to lose in casual conversation about “crypto” and “digital dollars,” where a token moving on a blockchain can look functionally identical to an outside observer regardless of whether it represents a bank deposit, a reserve-backed stablecoin, or a central bank liability, even though the answer to who actually bears the risk if something goes wrong varies enormously between those three cases. Getting that distinction right matters not as an academic exercise but as a practical matter for anyone, from a corporate treasurer choosing a settlement rail to a policymaker drafting the next generation of financial regulation, who needs to understand what protections actually attach to a given digital claim before relying on it.
The documented scale behind this shift is no longer speculative. JPMorgan’s Kinexys platform has processed trillions of dollars in cumulative transaction volume, Citi has moved tokenized deposit infrastructure from launch announcement to a documented pilot that compressed a multi-day trade finance process into minutes, and Partior has grown from a three-bank joint venture into a multi-currency network attracting outside investment specifically because banks and investors alike see durable value in shared, tokenized settlement infrastructure. These are not proofs of concept awaiting their first real test; they are operating systems already handling the ordinary business of large corporations moving money across borders and time zones, built by institutions with every incentive to be conservative about claiming success before it is genuinely earned.
At the same time, deposit tokenization remains a fundamentally institutional phenomenon so far, concentrated among the largest global banks and their most sophisticated corporate clients, and the broader questions about interoperability between competing banks’ systems, the practical mechanics of deposit insurance in a tokenized failure scenario, and whether smaller banks can meaningfully participate at all remain genuinely unresolved rather than simply awaiting a known technical fix. The comparison to stablecoins that gives this article its framing is not a competition with an obvious winner already determined; stablecoins offer broader public accessibility and a more mature multi-platform ecosystem today, while deposit tokens offer the accumulated trust, regulatory integration, and balance-sheet stability of the existing banking system, and different use cases will likely continue to favor one over the other for reasons specific to the participants involved rather than a single verdict applying everywhere. What deposit tokens have demonstrated, concretely and at meaningful scale, is that the choice between modernizing money movement and staying inside the regulated banking system was never as binary as it once appeared, and the banks building this infrastructure have bet, with real client money and real engineering investment behind that bet, that depositors and corporate treasurers will continue to value the protections of the existing system even as they demand the speed and programmability that blockchain-based technology has shown is possible. Whether that bet continues paying off, at the scale these institutions clearly hope for, will depend as much on how regulators, competing banks, and corporate clients resolve the open questions still surrounding this technology as it will on any further improvement to the underlying ledger systems themselves.
FAQs
- What is a tokenized bank deposit in simple terms?
It is an ordinary bank deposit represented as a digital token on a shared or blockchain-based ledger, so that the claim on that deposit can be transferred instantly and around the clock. The underlying money never leaves the issuing bank’s balance sheet; only the technical form in which the claim can be moved and tracked changes. - How is a deposit token different from a stablecoin?
A deposit token is a liability of a regulated commercial bank, subject to existing banking rules and, where applicable, deposit insurance, the same as an ordinary account balance. A stablecoin is typically issued by a non-bank company and backed by a reserve of assets that company holds, governed by a separate and generally newer regulatory framework rather than by bank supervision and deposit insurance. - How does a deposit token differ from a central bank digital currency?
A deposit token is a liability of a commercial bank, while a central bank digital currency, or CBDC, is a direct liability of a country’s central bank, the same institution that issues physical cash. A CBDC carries essentially no credit risk to the holder, but retail CBDC proposals raise separate concerns about commercial bank deposit flight and financial privacy that have made them slower to roll out than bank-led deposit tokens. - Is money held as a deposit token insured the same way as a regular deposit?
In most cases a deposit token representing an insured deposit type is expected to carry the same deposit insurance protection as the underlying account, up to the applicable coverage limit. The practical process for verifying and paying out that protection in a bank failure involving tokenized claims is newer and less tested than the established process for conventional deposit accounts. - Who is actually using deposit tokens today?
Deployment so far is concentrated among large institutional and corporate clients of major global banks. JPMorgan’s Kinexys platform, Citi’s Token Services, and the multi-bank Partior network all serve corporate treasuries, financial institutions, and large multinational companies rather than individual retail bank customers. - What is JPM Coin, and how does it relate to JPMD?
JPM Coin began as an internal settlement mechanism under JPMorgan’s blockchain division, now called Kinexys, allowing institutional clients to move dollar value between their own accounts continuously. JPMD is a newer USD deposit token that Kinexys piloted in 2025 and then made available for near-instant settlement on public blockchain infrastructure, extending the same underlying deposit token concept to a broader base of institutional counterparties. - What did Citi’s pilot with Maersk actually demonstrate?
Citi tested its Token Services platform against a real trade-finance process, the issuance of a bank guarantee to a canal authority as part of a shipping transaction. Using tokenized deposits and smart contracts, the pilot compressed a process that traditionally took days into one completed in minutes, demonstrating a concrete operational benefit rather than only a theoretical one. - What makes Partior different from a single bank’s own deposit token?
Partior is jointly owned and operated by multiple banks, including JPMorgan, DBS, and Standard Chartered, rather than being built and controlled by a single institution. This lets clients of different, competing banks settle payments directly against one another using tokenized deposits, rather than being limited to transfers within a single bank’s own client base. - Can smaller or regional banks issue their own deposit tokens?
In principle yes, but in practice the most developed and widely reported deposit token projects have come from the largest global banks, which have the balance sheet scale, technical resources, and institutional client relationships needed to build this infrastructure. Whether smaller banks can meaningfully participate, whether through joining shared networks or through lower-cost technology providers, remains an open question for the industry. - Will deposit tokens eventually replace stablecoins?
Not necessarily, and the two are more likely to continue coexisting for different use cases than for one to fully replace the other. Stablecoins currently offer broader accessibility across a wide range of public blockchain platforms, while deposit tokens offer the regulatory integration and balance-sheet protections of the existing banking system, and different institutional and individual users will likely continue choosing between them based on which set of tradeoffs matters more for their specific purpose.