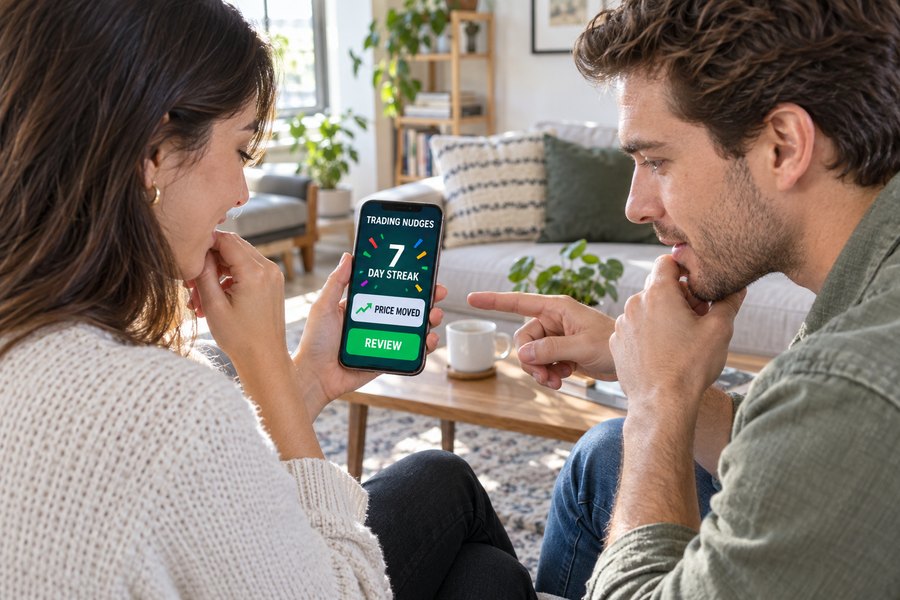
Open almost any modern investing app on a smartphone and the experience rarely feels like the paperwork-heavy, phone-call-driven world of a traditional brokerage. Instead, a completed trade might trigger a burst of animated confetti across the screen, a running streak counter might track how many consecutive days an account has logged in, and a notification might arrive minutes later celebrating a stock’s sudden price jump. These are not accidental design choices. They are deliberate applications of gamification, the practice of borrowing design elements from video games and social apps, points, rewards, progress bars, celebratory animations, and social comparison, and layering them onto a task that was never a game to begin with. The same techniques that keep people opening a language-learning app every morning or checking a fitness tracker’s step count have been imported wholesale into the world of buying and selling securities, and the question this raises is not a trivial one: does making investing feel fun and frictionless help newcomers build good habits, or does it push people toward the same compulsive, short-term behavior that casinos have spent a century perfecting?
The stakes of that question rose sharply once trading apps moved from a niche product used mostly by experienced investors to a mainstream one used by millions of first-time participants. Commission-free trading, fractional shares, and mobile-first design collectively removed most of the practical barriers that once separated casual curiosity from actually opening a brokerage account, and the same period saw an unprecedented wave of new account openings, disproportionately among young and financially inexperienced users. That growth did not happen by accident either. Fintech brokerages compete for attention in the same crowded app-store marketplace as every other consumer product, and the design patterns that keep people scrolling social media or completing daily gaming challenges turned out to translate remarkably well to an app that involves real money and real financial risk. The result is a genuinely new category of product, part financial infrastructure and part engagement platform, and the two halves of that combination do not always pull in the same direction.
This tension sits at the center of a debate that has moved well beyond internet commentary and into formal regulatory inquiry on both sides of the Atlantic. Securities regulators in the United States and the United Kingdom have both concluded, through separate investigations built on different methodologies, that specific game-like design features are measurably associated with riskier investment choices and, in some cases, behavior that closely resembles problem gambling. Academic researchers, working independently of any regulator, have found that the trading patterns of users on gamified platforms produce statistically negative returns compared to a simple buy-and-hold approach, precisely the kind of frequent, attention-driven trading that game mechanics are designed to encourage. At the same time, defenders of these features point out that any tool which gets more people, especially young people who have historically been underserved by traditional finance, comfortable with saving and investing is doing real good, and that the alternative, an intimidating and inaccessible brokerage experience, has its own well-documented costs in the form of wealth-building opportunities missed entirely.
This article works through that debate methodically, starting with a plain description of what gamification actually looks like inside a modern investing app and why fintech companies build it that way in the first place. It then turns to the evidence, examining a peer-reviewed academic study of actual trading data alongside a large-scale regulatory survey, both of which attempt to measure whether these design choices change behavior and outcomes rather than simply describing what the features look like. It covers Robinhood’s own reckoning with its most famous gamified feature, the confetti animation that became a symbol of the entire controversy and ultimately the subject of a multimillion-dollar regulatory settlement. It considers which investors are most vulnerable to these design patterns, weighs the counter-argument that some forms of engagement design serve investors well, and surveys how regulators and platforms alike have begun responding. None of this requires any prior familiarity with trading apps, behavioral design, or securities regulation; the goal is to leave a reader who has never opened one of these apps with a clear, evidence-based understanding of where the real disagreement lies.
What Gamification Looks Like Inside Investing Apps
Gamification did not originate in finance. It is a well-established discipline in software design more broadly, built on the observation that human beings respond predictably to certain psychological triggers: the satisfaction of visible progress, the pull of a reward that arrives unpredictably, the mild social pressure of seeing how one’s own activity compares to others. A language-learning app that shows a growing streak of consecutive practice days, a fitness tracker that awards a badge for reaching a step goal, and a social media platform that displays a running count of likes are all applying the same underlying toolkit, each adapted to its own product. What makes the application of this toolkit to investing apps distinctive, and controversial, is that the underlying activity being gamified involves placing real money at real risk, a category of decision that behavioral economists generally agree benefits from more deliberation and less impulsivity, not less.
The most visually recognizable gamification feature in trading apps is the celebratory animation that plays after a completed transaction, most famously the shower of digital confetti that Robinhood displayed on its app for several years. This kind of positive reinforcement, delivered immediately after an action a company wants a user to repeat, is a textbook operant-conditioning technique borrowed directly from slot-machine and video-game design, where an immediate, pleasurable feedback signal strengthens the association between an action and a reward, encouraging repetition regardless of whether the underlying outcome, in this case a stock trade, was actually a good decision. Streaks work on a related but distinct psychological principle, exploiting a documented human aversion to breaking a continuous pattern once it has been established, the same mechanism that keeps people opening a habit-tracking app daily even after the original motivation for the habit has faded. Badges and achievement markers add a layer of status and completionism, giving users a visible token for reaching a milestone, whether that milestone reflects sound financial judgment or simply frequent activity.
Social comparison features add another dimension entirely. Leaderboards that rank users by portfolio performance, or that highlight which stocks are being bought most heavily by other users on the platform in real time, introduce a competitive and herd-following element to what has traditionally been treated as an individual, private financial decision. Push notifications compound this effect by injecting the platform back into a user’s attention at moments the app itself chooses rather than moments the user initiates, often timed around specific stock price movements framed to generate a sense of urgency or opportunity. Even seemingly neutral design choices carry behavioral weight: default settings for investment amounts, order sizes, or the degree of leverage offered are frequently set higher than a cautious user might choose deliberately, exploiting a well-documented tendency, sometimes called default bias, for people to accept whatever option is pre-selected rather than actively choosing an alternative.
A subtler but arguably more powerful mechanism running underneath many of these individual features is the use of variable, unpredictable rewards rather than fixed, predictable ones, a design principle with deep roots in behavioral psychology research on operant conditioning dating back decades before any smartphone existed. A reward that arrives on an unpredictable schedule, a stock’s price suddenly spiking and triggering a notification, an unexpected badge for an activity threshold the user did not know existed, produces a stronger and more persistent behavioral pull than a reward delivered on a fixed, entirely predictable schedule, which is part of why slot machines and other games of chance are built around variable reward timing rather than fixed payouts. Applying this same principle to a financial app means that the unpredictability of markets themselves, ordinarily just an inherent feature of investing that a careful investor learns to tolerate rather than chase, can be woven directly into the app’s engagement design, turning ordinary price volatility into a stream of intermittent, unpredictable rewards and notifications that keep users checking back far more often than a long-term, buy-and-hold strategy would ever require. None of these individual features is unique to finance, and none is inherently deceptive in the way a fraudulent scheme would be; the concern that regulators and researchers have raised is about their cumulative effect when combined and applied to decisions involving real financial risk, a concern examined in detail in the sections that follow.
The Business Case: Why Fintechs Gamify
Understanding why these features exist at all requires understanding the business model underneath the app, because gamification in investing platforms is rarely, if ever, an aesthetic choice made in isolation. Commission-free trading apps disrupted an industry that had, for decades, charged a flat fee per trade, and eliminating that fee removed the most obvious source of brokerage revenue. Replacing it required finding other ways to monetize the relationship, and the resulting business models generally depend on some combination of user growth, account balances, and, critically, the volume and frequency of trading activity that flows through the platform. A user who opens an account, deposits money, and rarely trades again generates comparatively little ongoing value under several of these models, which creates a structural incentive to keep users opening the app, checking their portfolios, and, in many cases, trading more often than they otherwise would.
This incentive structure is not a hidden or speculative claim; it shows up directly in how these companies report their own performance to investors and regulators, where metrics like daily active users, average revenue per user, and trading volume feature prominently as indicators of business health. A company whose revenue scales with trading activity has a rational, entirely legal business reason to invest engineering and design resources into features that increase how often users open the app and place trades, independent of whether that increased activity serves the individual user’s financial interests. This is the same underlying dynamic that shapes engagement design across the broader technology industry, from social media to mobile gaming, where the platform’s growth metrics and the user’s own best interests are not always perfectly aligned, but the stakes are meaningfully different when the product in question involves real financial risk rather than simply attention or entertainment.
The competitive landscape of the fintech brokerage industry adds further pressure toward this kind of engagement-maximizing design. Once one major platform demonstrated that commission-free, gamified trading could attract millions of new accounts in a short period, competitors faced strong pressure to adopt similar design patterns simply to remain competitive for the same pool of new, often younger, investors, regardless of any individual company’s internal views on the wisdom of any specific feature. This dynamic mirrors patterns seen in other consumer technology sectors, where a single company’s success with an attention-capturing design choice tends to propagate quickly across an entire industry as competitors race to match it, and it helps explain why gamification features that first appeared on one platform were, within a relatively short window, adopted in some form across much of the broader trading app industry, making the phenomenon a structural feature of the competitive environment rather than the isolated choice of any single company.
Payment for Order Flow and the Incentive to Maximize Trades
The specific revenue mechanism most closely associated with this incentive tension is payment for order flow, an arrangement in which a brokerage routes its customers’ buy and sell orders to a market maker or trading firm in exchange for a per-trade payment, rather than executing the trades itself or charging the customer directly. This practice is legal and disclosed, and proponents argue it has allowed brokerages to offer commission-free trading to retail customers who previously paid a flat fee for every transaction, a genuine democratizing effect on access to markets. Under this model, however, the brokerage’s revenue from a given customer relationship rises directly with the number of trades that customer places, since each individual trade, regardless of its size or whether it made money for the customer, generates a payment from the market maker executing it.
This structural fact has drawn sustained scrutiny from securities regulators precisely because it creates a financial incentive for the brokerage that runs in a specific direction: more trades generate more revenue for the platform, independent of whether those additional trades represent sound decisions for the person placing them. A brokerage operating under this model has, in principle, a business reason to prefer a highly active trader placing many small transactions over a passive, buy-and-hold investor who trades rarely, even though most mainstream financial advice for long-term individual investors favors the latter approach. This does not mean every gamification feature was designed with this specific incentive in mind, but it explains why regulators examining these design patterns have paid close attention to the underlying revenue model rather than treating engagement features as a purely cosmetic or user-experience matter, since the alignment, or misalignment, between what keeps an app engaging and what actually serves the investor sits close to the center of the regulatory concern.
The U.S. Securities and Exchange Commission has itself acknowledged this tension publicly, opening a formal request for public comment in 2021 on what it termed “digital engagement practices,” explicitly naming behavioral prompts, game-like design elements, and payment-for-order-flow-linked business models as related concerns worth examining together rather than in isolation. That the securities regulator with primary jurisdiction over these firms chose to link its inquiry into engagement design directly to its inquiry into the payment-for-order-flow revenue model reflects an understanding, shared broadly across the research reviewed throughout this article, that the two are not separate issues but two sides of the same underlying incentive structure: a business model that profits from trading volume will tend, whether by explicit design or by the ordinary pressures of running a competitive consumer product, to build features that generate more of it.
The Evidence That Game Mechanics Change Investor Behavior
Describing what gamification looks like and why companies build it does not, by itself, prove that these features actually change how people invest or how much money they make or lose as a result. That question required empirical investigation, and over the past several years both academic researchers and financial regulators have conducted independent studies attempting to answer it using very different methodologies: one examining actual trading records to measure financial outcomes directly, the other surveying thousands of app users about their behavior and psychological responses. Taken together, these two bodies of evidence represent some of the most rigorous, large-scale attempts to move the gamification debate beyond anecdote and design critique into measurable, documented outcomes, and both point in a broadly similar direction.
What makes this evidence particularly significant is that it did not emerge from advocacy groups or competitors with a commercial interest in the outcome. One study was published in one of the most rigorously peer-reviewed journals in financial economics, subject to the standard academic vetting process that requires methodological transparency and reproducibility. The other was conducted directly by a national financial regulator with statutory authority over the firms it was studying, using a large primary survey rather than secondhand reporting. The sections below examine each in turn, including the specific figures each produced and what those figures do, and do not, establish about the relationship between gamified design and investor harm.
The two methodologies are worth distinguishing carefully before turning to their results, because each addresses a different half of the same underlying question and each carries its own limitations. Trading-record analysis, the approach taken by the academic researchers, has the advantage of measuring what people actually did with real money rather than what they say they did, sidestepping the well-known problem in behavioral research that people’s self-reported behavior does not always match their actual behavior. What it generally cannot do is directly measure the psychological experience behind a trade, whether a given purchase was driven by confetti-induced excitement, a push notification, genuine independent research, or some combination of all three. Survey-based research, the approach taken by the regulator, has the opposite strength and weakness: it can ask users directly about their psychological state, their awareness of specific design features, and their own sense of whether their behavior has become problematic, but it necessarily relies on self-report and cannot observe actual trading outcomes with the same precision as a direct analysis of account-level data. Considered together, rather than in isolation, the two approaches compensate for each other’s blind spots, which is part of why regulators in multiple jurisdictions have cited both bodies of work when explaining the basis for their own policy responses.
Attention-Induced Trading: What Academic Research Found
The most widely cited academic study on this topic is “Attention-Induced Trading and Returns: Evidence from Robinhood Users,” published in December 2022 in The Journal of Finance, authored by Brad M. Barber, Xing Huang, Terrance Odean, and Christopher Schwarz. The Journal of Finance is one of the most selective and heavily cited academic journals in financial economics, and the study’s authors include researchers with long-established track records studying individual investor behavior, giving the work substantial credibility within the field. Rather than surveying users about their intentions or opinions, the researchers analyzed actual trading data to test whether Robinhood’s distinctive interface design, which the paper notes draws users’ attention to the platform’s own most-purchased stocks, causes users to herd into the same securities at the same time in a way that differs measurably from trading patterns on more traditional platforms.
The study’s central finding directly addresses the practical consequences of attention-driven, herd-following trading behavior. The researchers documented that when Robinhood users engaged in intense, concentrated buying of a particular stock on a given day, likely driven by that stock’s prominent placement on the app’s most-purchased or most-active lists, the stocks receiving this surge in attention subsequently underperformed, producing average abnormal returns of negative 4.7% over the following twenty trading days. In plain terms, stocks that suddenly attracted a wave of coordinated buying interest from Robinhood users tended to lose value relative to the broader market in the weeks that followed, a pattern consistent with users piling into securities because of their visibility on the platform’s interface rather than because of any underlying change in the company’s fundamentals. The paper also found that outages on the platform, periods when users could not trade at all, disproportionately reduced trading specifically in the stocks that had been receiving heavy attention, further supporting the interpretation that the attention itself, rather than independent investment research, was driving the trading activity.
This finding matters for the gamification debate specifically because it demonstrates a measurable financial cost tied to design choices that direct user attention toward certain stocks, whether through most-purchased lists, trending tickers, or similar interface elements common across gamified trading apps. It is one thing to argue in the abstract that flashy design features might encourage impulsive trading; it is another to have a peer-reviewed study using actual trade-level data showing that the specific pattern of behavior these features encourage, concentrated, herd-following buying driven by what is visually prominent on the app, is associated with statistically negative returns for the investors engaging in it. The study does not claim that gamification features are the sole cause of this pattern, and the authors are careful academic researchers who frame their findings in terms of correlation between attention-drawing design and trading behavior rather than a simple causal indictment of any single feature, but the underlying mechanism it documents, attention captured by an interface translating into financially costly trading decisions, sits at the heart of what critics of gamified design have long argued happens in practice.
The study’s authors situate their findings within a much longer academic tradition studying what researchers call attention-driven trading among retail investors generally, a body of work that predates smartphone trading apps entirely and has consistently found that individual investors tend to buy stocks that have recently caught their attention, through news coverage, unusual trading volume, or extreme price moves, more than they buy stocks that have not, regardless of whether the underlying company’s fundamentals actually changed. What the Robinhood-specific research contributes to this longer tradition is evidence that an app’s own interface design can function as its own independent attention-drawing mechanism, arguably a more direct and immediate one than a news headline or a general market trend, since it places a curated list of the platform’s own most-active stocks directly in front of users each time they open the app, effectively manufacturing the same kind of concentrated attention that previous research had only observed arising organically from external market events.
The FCA’s Survey: Measuring Gambling-Like Behavior
The second major body of evidence comes from the United Kingdom’s Financial Conduct Authority, the country’s primary financial services regulator, which published a research article titled “Gaming trading: how trading apps could be engaging consumers for the worse” on November 21, 2022. Unlike the academic study, which relied on trading records, the FCA’s research combined a large-scale survey of more than 3,000 trading app users, drawn from customers of four different trading apps plus a comparison group using a more traditional investment platform without gamified features, alongside in-depth qualitative interviews with a smaller sample of 20 app users. This dual approach let the FCA connect specific design features directly to self-reported behavior and psychological indicators in a way that trading records alone cannot capture.
The FCA’s evaluation identified a consistent set of design features across the apps it reviewed, including celebratory messages and falling confetti after a completed trade, leaderboards ranking users against each other, frequent push notifications built around real-time market news, and default settings for investment amounts and leverage that were often set higher than a cautious user might select on their own. To measure the real-world impact of these features, the FCA adapted the Problem Gambling Severity Index, a clinically validated screening tool normally used to assess gambling behavior, applying it to investing activity for the first time in this context. The results were striking: among survey respondents, 1 in 27, or roughly 3.75%, scored high enough to be classified as exhibiting problem gambling behavior in relation to their investing activity, a rate the FCA noted was comparable to the rate of problem gambling among people who gamble online through conventional means. When the analysis widened to include respondents showing any elevated risk on the same scale, that figure rose to nearly 1 in 5, or over 20%, of trading app customers overall, with the highest rates concentrated among users of the apps that had the most gamification features present.
The survey also found that for two of the apps reviewed, both of which offered cryptocurrency trading alongside more gamified design features, almost 50% of surveyed customers reported investing in products that were potentially beyond their own stated risk tolerance, a figure that dropped substantially, though remained elevated relative to the non-gamified comparison platform, for apps that did not offer cryptocurrency. The FCA was careful to note that this survey design establishes a strong association between the presence of gamified features and these risky, gambling-adjacent behaviors rather than definitively proving that the features alone caused the behavior, since users who are drawn to riskier apps in the first place might also be predisposed toward riskier behavior generally. Even accounting for that caveat, the scale of the survey, more than 3,000 respondents surveyed directly by a national financial regulator with full access to the firms it examined, and the consistency of its findings across independent analytical methods make it one of the most substantial pieces of documented evidence in the entire gamification debate, and it directly informed the regulatory response detailed later in this article.
The FCA’s smaller qualitative component, twenty in-depth interviews conducted alongside the larger survey, added texture to the statistical findings that a survey alone could not capture. One participant, describing the cumulative effect of the design features present on their app, told researchers the experience felt “all very in your face and feels more like a sports betting app” than a conventional investment platform, a comparison the participant appears to have arrived at independently rather than in response to a leading question. Another participant, describing the effect of frequent push notifications specifically, told researchers they had developed what they themselves described as an “addiction habit” that required deliberately disabling notifications to manage, a self-diagnosis offered by an ordinary app user rather than a clinician, but one that closely echoes the language the FCA’s own adapted Problem Gambling Severity Index was separately designed to detect. These qualitative accounts do not carry the same statistical weight as the survey’s headline figures, but they illustrate, in participants’ own words, the same underlying pattern the numerical data documented at scale.
Robinhood’s Reckoning: Confetti, Regulators, and a $7.5 Million Fine
No single feature has come to symbolize the gamification debate more thoroughly than Robinhood’s confetti animation, a burst of colorful digital confetti that filled a user’s screen after completing certain trades or reaching milestones like upgrading to a premium account tier. The feature was, by any measure, a small piece of interface design, but it became an unusually potent public symbol of the broader concern that trading apps were designed to feel celebratory and game-like regardless of whether the underlying financial decision was actually a good one, since the app offered the same enthusiastic visual reward whether a trade turned out to be profitable or not. Robinhood removed the confetti feature from its app in March 2021, telling reporters at the time that the change was intended to strip away distractions from the company’s stated mission of expanding access to investing, a decision that came as the company faced mounting regulatory scrutiny and prepared for its own public stock offering later that year.
Removing the feature from the app, however, did not resolve the regulatory questions that had already been raised about the broader pattern of design choices it represented. The Massachusetts Securities Division, the state regulator with jurisdiction over securities firms operating in Massachusetts, had filed a formal administrative complaint against Robinhood in December 2020, alleging that the company had used aggressive tactics, including gamification strategies such as the confetti animation, digital scratch-ticket-style reveals, and free stock rewards, to attract and retain inexperienced investors in ways that failed to account for their actual investment objectives and risk tolerance, compounded by allegations concerning the platform’s history of service outages during periods of high market volatility. This case worked its way through Massachusetts’ administrative process over the following years rather than resolving quickly, reflecting the genuinely novel legal questions involved in applying existing securities-suitability and fair-dealing standards to app-based engagement design that had no direct precedent in traditional brokerage regulation.
The matter was ultimately resolved on January 18, 2024, when the Massachusetts Securities Division issued a consent order in which Robinhood agreed to pay a $7.5 million fine and to implement a substantial set of changes to its business practices concerning how it develops and deploys gamification and related design features going forward. The settlement represented one of the largest and most explicit regulatory actions taken anywhere in the United States specifically targeting the use of gamification techniques in a retail investment product, and it functioned as a formal, legally binding acknowledgment that specific engagement-design choices, not merely broader business practices like payment for order flow or account suitability screening in the abstract, could themselves constitute grounds for a securities enforcement action. For an industry that had treated engagement design largely as a product and marketing decision insulated from securities regulation, the Massachusetts settlement established a concrete, dollar-figure consequence for building certain categories of gamified features into a trading platform, and it remains the most direct example of a U.S. regulator formally penalizing a company specifically over gamification practices rather than over a more conventional securities violation like inadequate disclosure or unsuitable investment recommendations treated separately from the app’s design.
The nearly three-and-a-half-year gap between the original December 2020 complaint and the January 2024 consent order is itself instructive, reflecting how genuinely unsettled the underlying legal and regulatory questions were at the time the case was filed. Securities suitability law had developed over decades primarily around human-delivered investment recommendations, a broker or advisor explicitly suggesting a specific security to a specific client, and applying that same body of law to an automated app interface that never makes an explicit recommendation but nonetheless shapes behavior through design required Massachusetts regulators to build a novel legal theory rather than apply settled precedent directly. The extended timeline gave the case an outsized influence on how other regulators, including the FCA and the SEC, approached their own parallel inquiries into digital engagement practices, since Massachusetts’ evolving theory of the case was closely watched by securities regulators in other jurisdictions grappling with structurally similar products and the same absence of established precedent.
Who Gets Hurt Most: Age, Experience, and Financial Vulnerability
The evidence reviewed so far establishes that gamified design features are associated with riskier, more frequent, and in some cases gambling-adjacent investing behavior across trading app users generally, but the impact of these features is not evenly distributed across every type of user. The FCA’s research specifically examined this question by breaking down its survey results across demographic and experience-based subgroups, finding that the association between gamification exposure and problematic behavior was measurably stronger among certain populations than others, a pattern with direct implications for how platforms, regulators, and individual users should think about the risks involved.
Younger investors, broadly those in the 18-to-34 age range, showed a notably stronger relationship between exposure to gamified features and risky or gambling-adjacent investing behavior compared with older users on the same platforms. This finding aligns with a broader pattern the FCA had already documented in earlier research specifically focused on younger investors, which found that emotions like thrill and excitement, rather than long-term financial planning, were commonly cited as key motivations for investing among this demographic, a psychological profile that gamified design features are, almost by definition, built to amplify rather than temper. Younger investors are also more likely to be encountering investing for the first time through one of these apps rather than transitioning from an existing relationship with a traditional financial advisor, meaning they often lack a prior frame of reference for what a more measured, lower-friction investing experience might look like.
Financial literacy and general financial resilience emerged as similarly important factors in the FCA’s analysis, with users demonstrating lower financial literacy and lower resilience, meaning less capacity to absorb a financial loss without significant hardship, showing up disproportionately among those classified as at-risk on the adapted Problem Gambling Severity Index. This overlap is particularly concerning from a consumer-protection standpoint because it suggests the users most likely to be harmed by aggressive gamification are frequently the same users least equipped to recognize the pattern in the moment or to absorb the financial consequences if their trading activity turns out poorly, a combination that regulators have specifically flagged as warranting heightened protective attention. Women were also identified in the FCA’s research as showing a stronger association between gamification exposure and problematic behavior relative to men, though the underlying research is less developed on why this particular disparity appears and would benefit from further dedicated study before drawing firm conclusions about its cause.
It is worth noting that vulnerability in this context is not a fixed, permanent characteristic assigned to a category of person, but rather a description of circumstances, financial resilience, prior investing experience, and emotional relationship to risk, that can change over time and that any individual user might move in and out of across different periods of their life. A financially sophisticated professional investor exploring a gamified app out of curiosity faces a meaningfully different risk profile than a young, first-time investor with limited savings using the same app as their sole introduction to financial markets, even though both are technically using an identical product with identical features. This distinction matters directly for the discussion of responsible design and regulatory response that follows, since a genuinely effective approach has to account for this variation in vulnerability rather than treating every user of a gamified platform as facing an identical level of risk.
Can Gamification Be Used Responsibly?
The evidence documented throughout this article paints a largely critical picture of gamification in investing apps, but the debate is not one-sided, and dismissing engagement design entirely would ignore both the genuine benefits some forms of it have delivered and the more nuanced position taken by many researchers and even some regulators, who have generally targeted specific gamification techniques rather than condemning the broader practice of making financial products more engaging and approachable. The relevant distinction that emerges from a closer look at this research is not simply whether a feature is game-like, but what specific behavior it is designed to encourage and reward.
Consider the difference between a feature that celebrates a user for making their first-ever contribution to a retirement account and one that celebrates a user for placing their fifteenth trade in a single day. Both could technically be described as gamification, using a positive visual or social reward to reinforce a behavior, but the behaviors being reinforced point in opposite directions: one encourages the foundational habit of saving and investing consistently over time, generally recognized as sound financial behavior regardless of the specific investments chosen, while the other encourages exactly the kind of frequent, attention-driven trading that the academic and regulatory research reviewed above associates with worse financial outcomes. Several apps built around automated saving and long-term investing, rather than active trading, have used streaks, milestones, and progress visualizations specifically to encourage users to maintain consistent contributions over months and years, a use of the same underlying psychological toolkit aimed at an entirely different behavioral outcome than the trade-frequency-maximizing features scrutinized by the FCA and the Massachusetts Securities Division.
Financial education represents another area where gamification’s underlying mechanics have produced results that are harder to characterize as straightforwardly harmful. Interactive modules that use quizzes, progress tracking, and small rewards to teach basic financial concepts, budgeting, the difference between a stock and a bond, or how compound interest works over time, apply the same engagement principles toward building financial literacy rather than toward encouraging transactions, and the research literature on gamified education more broadly has generally found positive effects on engagement and knowledge retention compared with static, text-based instruction. The distinction researchers and regulators increasingly draw is between gamification applied to financial behaviors that are broadly beneficial regardless of frequency, saving consistently, learning foundational concepts, diversifying a portfolio, and gamification applied specifically to transaction frequency or exposure to high-risk products, where the same techniques that make an app engaging also directly increase a user’s financial exposure with every additional use.
This does not mean the responsible-design category is free of its own risks or that any company can simply relabel a feature as educational to escape scrutiny; regulators examining these products have generally looked past a feature’s stated purpose to its actual measured effect on user behavior, which is precisely the analytical approach the FCA’s survey and the academic research on attention-induced trading both took. A feature framed as helping users “stay informed” through frequent notifications about price movements, for instance, can function identically to a feature explicitly designed to maximize trading frequency if its practical effect on user behavior is the same, regardless of how the company describes its intent. The responsible path forward, several consumer advocates and researchers have argued, requires evaluating engagement features by their downstream effect on financial outcomes and behavior patterns, not by their surface-level framing or the benign intentions a company might genuinely hold when designing them.
What Regulators and Platforms Are Doing Now
The evidence and enforcement actions detailed throughout this article have not existed in a vacuum; they have prompted concrete regulatory responses on both sides of the Atlantic, along with corresponding changes to how platforms design and disclose their products. In the United Kingdom, the FCA’s gamification research fed directly into the broader Consumer Duty, a set of rules that came into force on July 1, 2023, establishing a higher overall standard of care that financial firms owe to their retail customers. The Consumer Duty specifically requires firms to design products and communications so that consumers can make effective, timely, and properly informed decisions, and it explicitly calls out “sludge” practices, a category of manipulative design that includes gamification techniques found to drive poor outcomes, as inconsistent with that standard. Following the rule’s introduction, the FCA stated publicly that it expected every firm offering stock trading to consumers in the UK to review its product design in light of the gamification findings and to make improvements where its own features were found to be contributing to problematic or gambling-like investor behavior, with particular emphasis on protecting customers in vulnerable circumstances.
In the United States, the regulatory response has moved somewhat differently, built more around enforcement actions targeting specific practices at specific firms, such as the Massachusetts settlement with Robinhood detailed earlier, combined with broader supervisory attention from federal regulators to what the U.S. Securities and Exchange Commission has termed “digital engagement practices,” a formal regulatory label capturing the same category of design features, behavioral prompts, game-like elements, and personalized recommendations, examined throughout this article. This regulatory attention pushed the largest fintech brokerages to reassess several of their most visible engagement features even in the absence of new blanket federal rules specifically banning them, since firms operating across multiple jurisdictions have practical business reasons to align their designs with the stricter standard, whether that standard originates from state-level enforcement, from the UK’s Consumer Duty, or from anticipated future action at the federal level.
Individual platforms have made their own visible adjustments as this scrutiny intensified, with Robinhood’s 2021 removal of its confetti feature standing as the most publicly recognized example, alongside subsequent changes to how the company and its competitors present risk disclosures, structure default settings for margin and leverage, and calibrate the frequency and framing of push notifications. These changes have not eliminated engagement design from trading apps altogether, and confetti, streaks, and notifications of various kinds remain common features across the industry in 2026, but the specific techniques most directly implicated in the academic and regulatory research, positive reinforcement immediately tied to trade completion, leaderboards ranking users by trading activity, and defaults set to maximize exposure rather than caution, have generally become less prominent or been redesigned with additional friction and disclosure compared to their form during the period these studies examined. Whether this represents a durable shift in how the industry approaches engagement design, or a temporary adjustment that could reverse as regulatory attention shifts elsewhere, remains an open question that will depend substantially on continued research, continued regulatory attention, and continued public scrutiny of a business model that still, in significant part, depends on how often users open the app.
Final Thoughts
The gamification debate ultimately asks a question that extends well beyond the specific mechanics of confetti animations or streak counters: what responsibility does a financial platform bear for the psychological effects of its own design choices, particularly when those choices touch people’s savings, their financial security, and in some documented cases, patterns of behavior that closely resemble compulsive gambling? The evidence assembled by academic researchers and financial regulators over the past several years has moved this question from a matter of speculation and design critique into one backed by peer-reviewed trading data and large-scale survey research, both pointing toward the same uncomfortable conclusion: features built to make investing feel more like a game measurably change how people invest, and not always for the better.
This matters enormously for financial inclusion, a goal that commission-free, mobile-first trading apps have genuinely advanced by lowering the practical barriers that once kept large segments of the population, particularly younger people and those without existing wealth or family financial guidance, out of markets that have historically rewarded long-term participation. The same accessibility that gamification helped create, however, carries a real cost when the specific design techniques used to sustain that accessibility also happen to encourage the kind of frequent, attention-driven trading that the research reviewed throughout this article associates with worse financial outcomes. A platform genuinely committed to financial inclusion has to reckon with the possibility that some of its most effective growth and engagement techniques are, at the same time, actively working against the financial interests of the very users it set out to serve, a tension that cannot be resolved simply by removing a single animated feature while leaving the underlying incentive structure unchanged.
The regulatory responses detailed in this article, the UK’s Consumer Duty, the Massachusetts settlement with Robinhood, ongoing scrutiny of digital engagement practices in the United States, represent a meaningful first step toward addressing this tension, but they are unlikely to be the final word. Financial technology moves quickly, and the same design ingenuity that produced confetti animations and trading leaderboards will likely produce new engagement techniques that current rules and enforcement actions have not yet anticipated, requiring ongoing vigilance from regulators, researchers, and platforms alike rather than a one-time fix. The distinction this article has tried to draw throughout, between engagement design that reinforces genuinely beneficial financial behaviors like consistent saving and design that reinforces frequent, high-risk trading, offers a useful framework for that ongoing work, but applying it in practice will require the same kind of rigorous, outcomes-focused research that produced the evidence reviewed here rather than judgments based on a feature’s surface appearance alone.
What makes this debate worth taking seriously, beyond the specific dollar figures and statistics involved, is what it reveals about the broader responsibility that comes with designing products that sit at the intersection of behavioral psychology and personal finance. Investing, unlike most of the other activities gamification has been applied to, carries genuine financial consequences that compound over time, and a generation of new investors is currently forming their first habits and instincts about markets inside products explicitly engineered to maximize engagement. Getting that responsibility right, building tools that make investing accessible and approachable without exploiting the same psychological vulnerabilities that casinos have long understood, may prove to be one of the more consequential design challenges facing the financial technology industry in the years ahead, with implications that will extend to whichever new engagement techniques replace the ones examined in this article.
FAQs
- What does “gamification” mean in the context of investing apps?
Gamification refers to the practice of applying game-design elements, such as points, badges, streaks, celebratory animations, and leaderboards, to a non-game activity like investing, with the goal of making the activity feel more engaging, rewarding, and habit-forming for the user. - Why did Robinhood remove its confetti animation?
Robinhood removed the confetti feature from its app in March 2021, stating the change was meant to reduce distractions from its investing mission, a decision that came amid growing regulatory scrutiny of gamification practices and ahead of the company’s own public stock offering later that year. - What was the outcome of the Massachusetts case against Robinhood?
The Massachusetts Securities Division issued a consent order on January 18, 2024, in which Robinhood agreed to pay a $7.5 million fine and implement changes to its practices, resolving a complaint originally filed in December 2020 over the company’s use of gamification strategies to attract inexperienced investors. - Does academic research actually show gamification causes people to lose money?
A 2022 study published in The Journal of Finance found that Robinhood users’ concentrated, attention-driven buying of specific stocks was followed by average abnormal returns of negative 4.7% over the next twenty trading days, a pattern consistent with attention-drawing app design leading to costly trading decisions. - What did the UK’s Financial Conduct Authority find in its research on trading apps?
In a November 2022 research article based on a survey of more than 3,000 trading app users, the FCA found that roughly 1 in 5 respondents showed signs of at-risk or problem gambling behavior when a version of the Problem Gambling Severity Index was applied to their investing activity, with rates highest among users of apps featuring the most gamification. - Are younger investors more affected by gamified design than older investors?
Yes. The FCA’s research found that the association between gamification exposure and risky or gambling-like investing behavior was notably stronger among users aged 18 to 34 than among older users, consistent with earlier FCA research finding that thrill and excitement are commonly cited motivations for younger investors. - What is payment for order flow, and how does it relate to gamification?
Payment for order flow is a practice in which a brokerage routes customer trade orders to a market maker in exchange for payment, generating revenue that scales with the number of trades placed rather than a flat commission, which creates a structural incentive for brokerages to encourage more frequent trading. - Is all gamification in financial apps harmful?
Not necessarily. Researchers and regulators have generally distinguished between gamification that reinforces beneficial behaviors, such as consistent saving or completing financial-education modules, and gamification that specifically encourages frequent trading or exposure to high-risk products, with the latter drawing the most regulatory concern. - What is the UK’s Consumer Duty, and how does it address gamification?
The Consumer Duty is a set of FCA rules that took effect on July 1, 2023, requiring financial firms to design products so consumers can make informed decisions and explicitly identifying manipulative “sludge” design practices, including harmful gamification techniques, as inconsistent with that standard. - Has gamification disappeared from trading apps since these regulatory actions?
No. Features like streaks and notifications remain common industry-wide, but the specific techniques most directly linked to harm in academic and regulatory research, such as trade-triggered celebratory animations, activity-based leaderboards, and high-risk default settings, have generally become less prominent or been redesigned with additional friction and disclosure since these findings were published.